


Caught Out By Yatsen's 70% Fall? Here's What Bears Saw
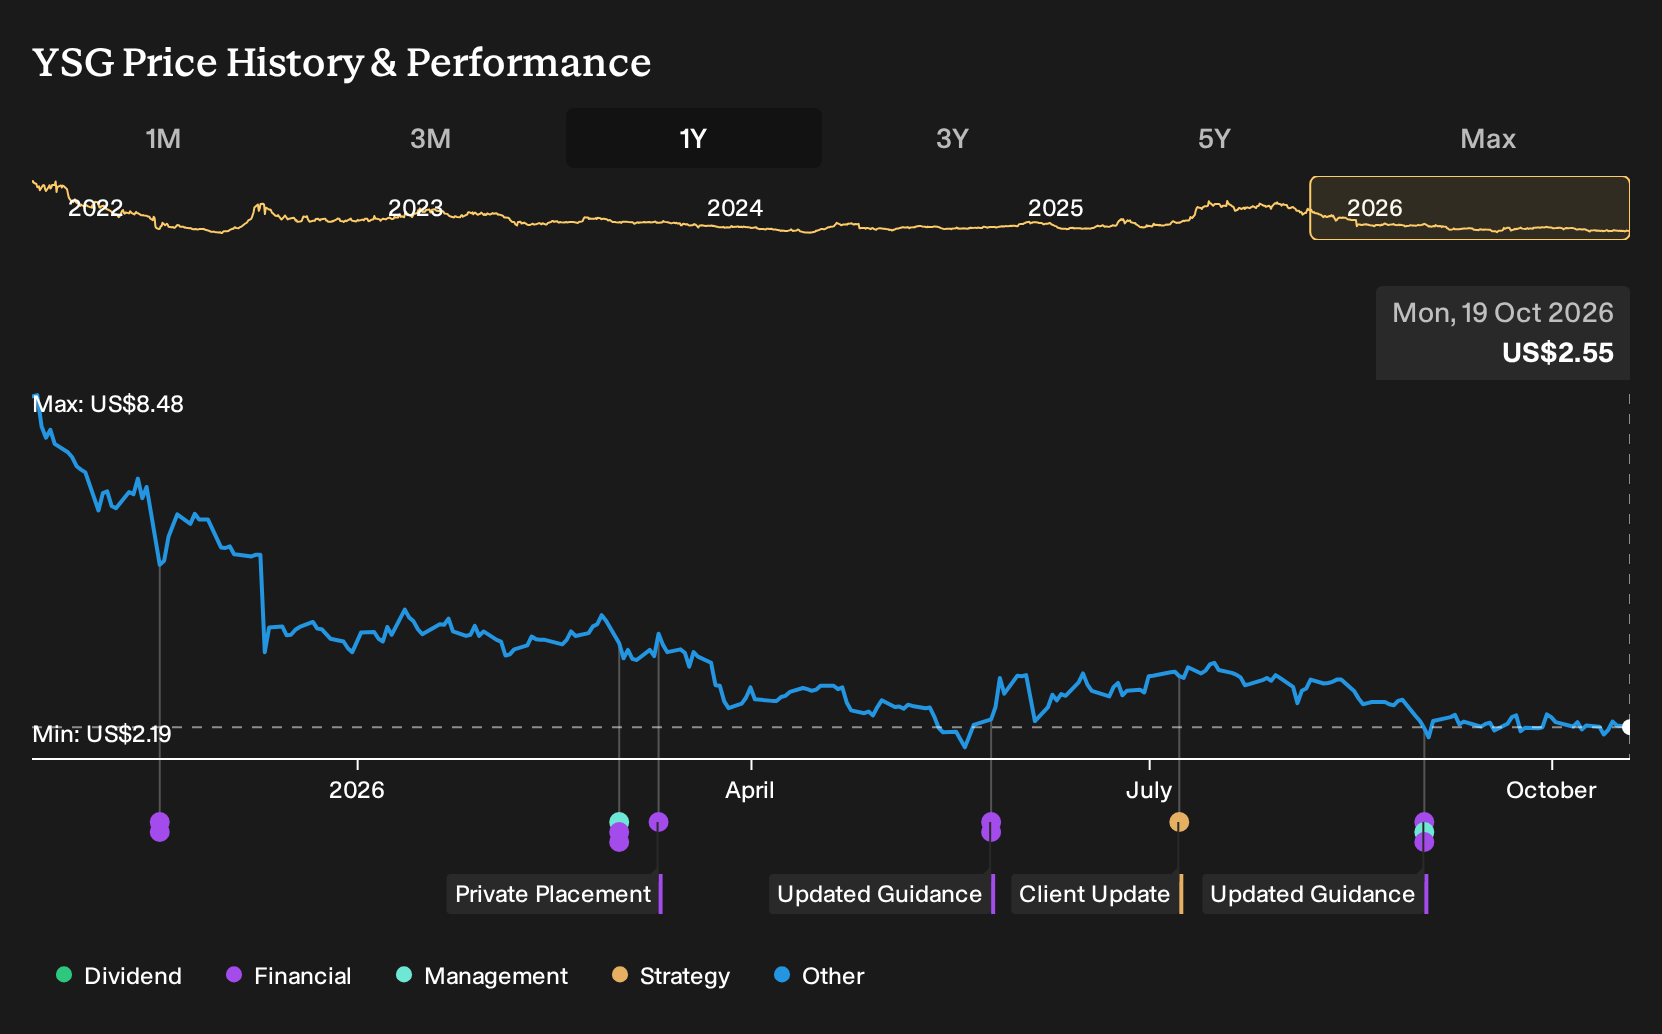
Yatsen entered the period with analysts split on its prospects, yet both sides still built their models on improving earnings and margin recovery. For Yatsen shareholders, the loss over the past year was 69.9%, including dividends. If you had bought on the back of that optimism, the gap between those forecasts and the eventual outcome would be hard to ignore. With revenue higher but net margin weaker, what early clues were already on the table?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
If the move has made Yatsen harder to judge, start where the gap is still open and scan 35 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Yatsen
The shares cost US$8.42 at the start of the period, and anyone looking at Yatsen then had to choose which future looked more plausible.
The bullish narrative put fair value at US$9.18, 9% above the start price. It relied on skincare revenue growing 15.5% a year and profit margin reaching 10.8% within three years.
The bearish view set fair value at US$3.40, 60% below the start price. It still used 18.4% revenue growth and a 10.9% margin, but focused on pressure from Chinese regulation and competition that would reduce the P/E assumption of 3.7x.
What The Results Changed For Yatsen Investors
Yatsen’s later filings showed revenue at CN¥1,142.18m in Q2 2026 versus CN¥1,086.73m a year earlier, while the loss widened from CN¥17.67m to CN¥90.83m and net margin moved from -1.6% to -8.0%. That challenged both the bullish and bearish profit assumptions that relied on a positive margin within three years. The evidence cut both ways.
The whole episode turned on one fragile belief: that higher sales would quickly translate into healthier net margin. When you assess another stock with a similar story, track the direction of reported net margin each year against any multi year margin target.
What Yatsen’s Price Drop Asks You To Believe Today
Yatsen trades at US$2.55 today, after a 69.9% loss over the past year. The selected Narrative still places its Fair Value above that level, anchored in the idea that skincare, R&D output and channel mix can eventually support stronger economics.
For that higher figure to be reached, a buyer today would need to assume that skincare led mix, scientific branding and tighter marketing spend can collectively support a durable shift into sustainable profitability.
"The main thing that has to go right is that Yatsen Holding turns its R&D platform and channel mix shift into sustainable profitability, keeping selling and marketing costs in check while competition and digital traffic costs remain intense. The current valuation implies that Yatsen Holding is priced as if its skincare-led growth, reinforced R&D credentials, and liquidity position will not translate into a durable improvement in earnings power for shareholders."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 41% below our estimate - turns complex safety challenges, regulatory oversight and AI risk into recurring advisory engagements.
- Company 2 - 45% below our estimate - converts a technology intensive backlog into higher margin mechanical and electrical installation work.
- Company 3 - 49% below our estimate - expands regulated betting platforms while reinvesting in compliance, responsible gaming tools and technology.
That is three of the list. See the full list of 25 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com