


Did Top SBA Lender Recognition Just Shift Live Oak's (LOB) Investment Narrative?
- Live Oak Bancshares was recently recognized by the U.S. Small Business Administration as the top SBA 7(a) lender by dollar volume, after approving 2,411 loans totaling more than US$2.58b for small business owners in fiscal 2026.
- This leadership in SBA 7(a) lending highlights how Live Oak Bancshares’ mix of sector expertise and technology platforms is contributing to meaningful real-world loan production for entrepreneurs across the country.
- Investors will be watching to see how this SBA 7(a) lending leadership influences Live Oak Bancshares’ investment narrative around technology-driven small business banking.
Live Oak Bancshares Investment Narrative Recap
To own Live Oak Bancshares, you need to believe the bank can keep scaling its tech heavy small business platform while holding credit and funding risks in check. The near term swing factor is whether Live Oak Express, SBA 7(a) lending and business checking can keep broadening customer relationships without pushing expenses much above the roughly US$85 million quarterly base.
The biggest risk sits in the combination of high bad loan levels at 4.2%, a 36% allowance coverage and concentration in government guaranteed programs. The new SBA 7(a) lending milestone is impressive, but it does not change that credit quality, any rule changes and funding costs remain the key near term watchpoints.
The recent recognition as the top SBA 7(a) lender lines up directly with the earlier catalyst around Live Oak Express and small dollar 7(a) production. Record volumes through these channels, together with US$744 million of checking and other DDA balances, show how Live Oak Bancshares is leaning into tech enabled small business banking rather than a branch heavy model.
That same announcement also connects to the secondary market gain on sale story. The small dollar SBA program has already produced US$19 million of cumulative gain on sale over six quarters, with a multi year production target of at least US$750 million annually. Execution against that target, while managing credit and keeping the efficiency ratio in the low to mid 50s, appears central to how this story progresses.
Live Oak Bancshares is tied to a narrative in which analysts are modeling revenue of US$1.0b and earnings of US$269.3 million by 2029, supported by an assumed 24.7% yearly revenue growth rate and an earnings increase of about US$137 million from current earnings of US$132.3 million.
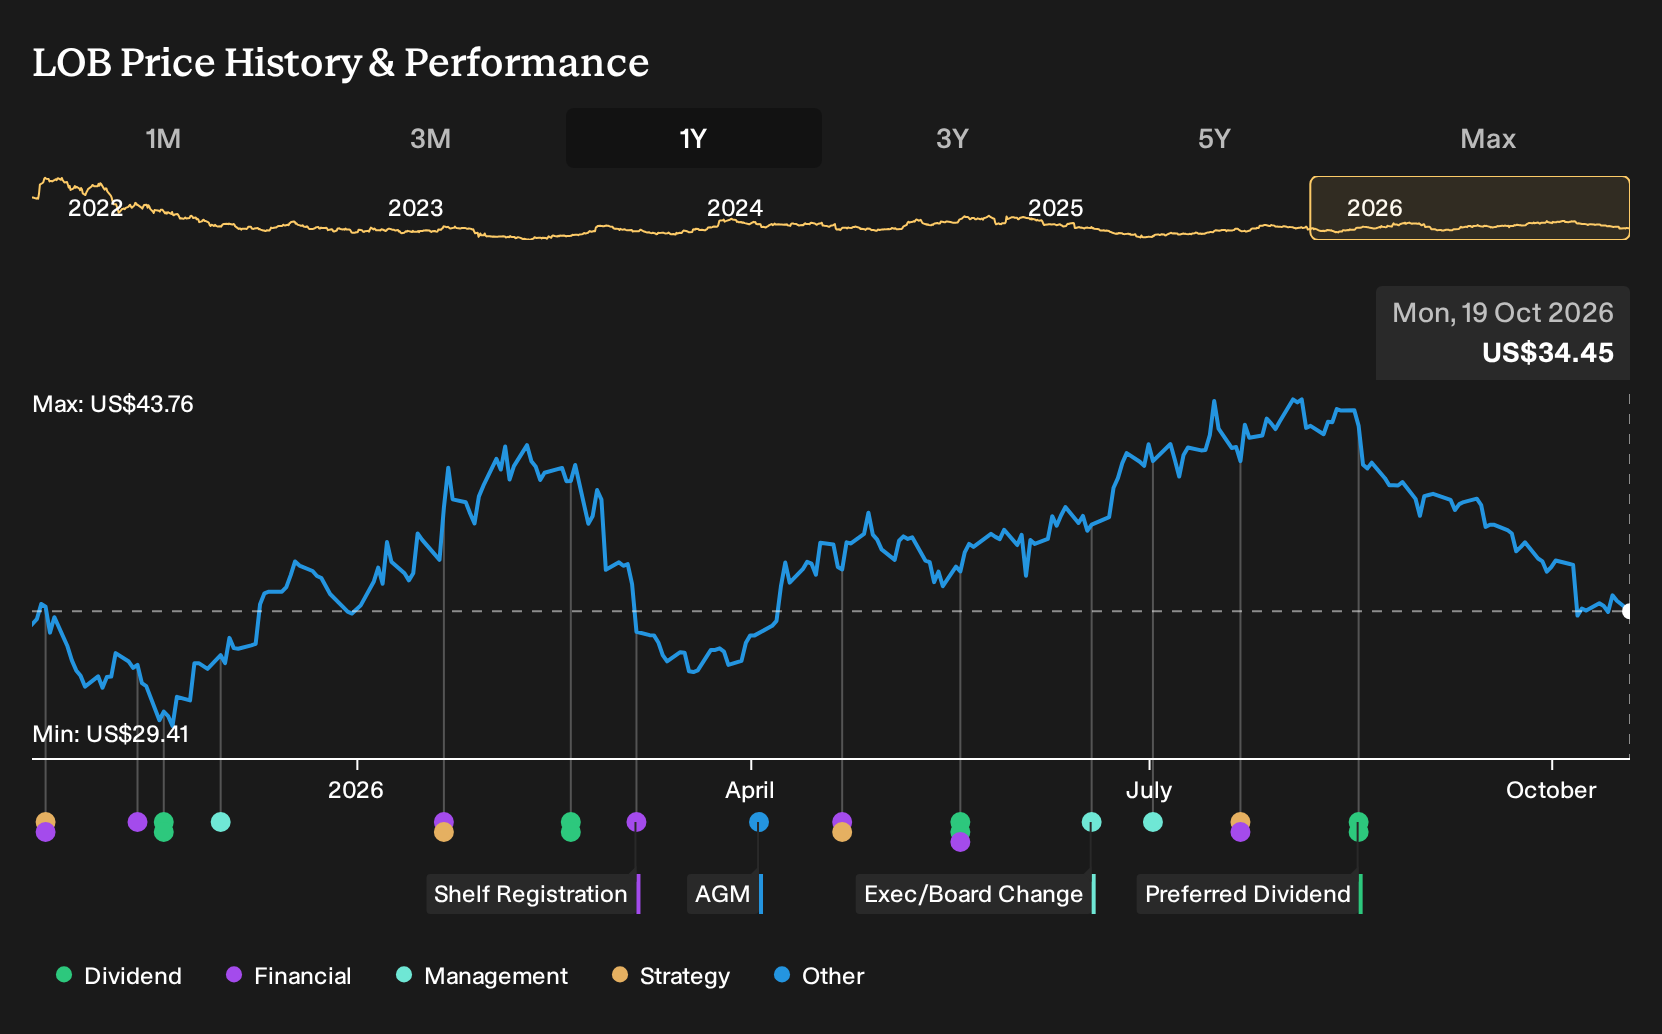
Uncover why Live Oak Bancshares' fair value indicates a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might see this SBA 7(a) lending milestone and focus on a different catalyst than the consensus. The most optimistic analysts lean into Live Oak Bancshares’ tech heavy model, arguing that faster efficiency gains could justify prior forecasts of US$1.1b revenue and US$316.2 million earnings by 2029. Their pre news narrative may shift as you weigh this update.
Explore 2 other Live Oak Bancshares fair value estimates, including one that suggests as much as 100% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Live Oak Bancshares research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Live Oak Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Live Oak Bancshares' overall financial health at a glance.
Looking for more investment ideas beyond Live Oak Bancshares?
If the Live Oak Bancshares story has sharpened your thinking about tech focused lenders, you can broaden your search by looking for other businesses that match your risk, quality and income preferences using the Simply Wall St Screener.
- For investors who want quality and value in the same place, you can review a curated list of companies that screen well on profitability and valuation through the 35 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you, you can filter for businesses with stronger balance sheets and lower risk scores via the 32 resilient stocks with low risk scores.
- When you are looking for underfollowed stories with solid fundamentals, you can sort through a focused group of lesser known opportunities using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com