


3 ASX Penny Stocks With At Least A$60M Market Cap
The Australian market is poised for a cautious start, with futures indicating a weaker opening following mixed signals from Wall Street and ongoing concerns about interest rates and inflation. Despite these challenges, certain investment opportunities continue to attract attention, particularly within the realm of penny stocks. Though often considered niche or speculative, penny stocks can still offer substantial growth potential when backed by solid financials. In this article, we explore three such stocks on the ASX that combine financial strength with promising prospects.
Underneath we present a selection of stocks filtered out by our screen.
Estrella Resources (ASX:ESR)
Simply Wall St Financial Health Rating: ★★★★☆☆
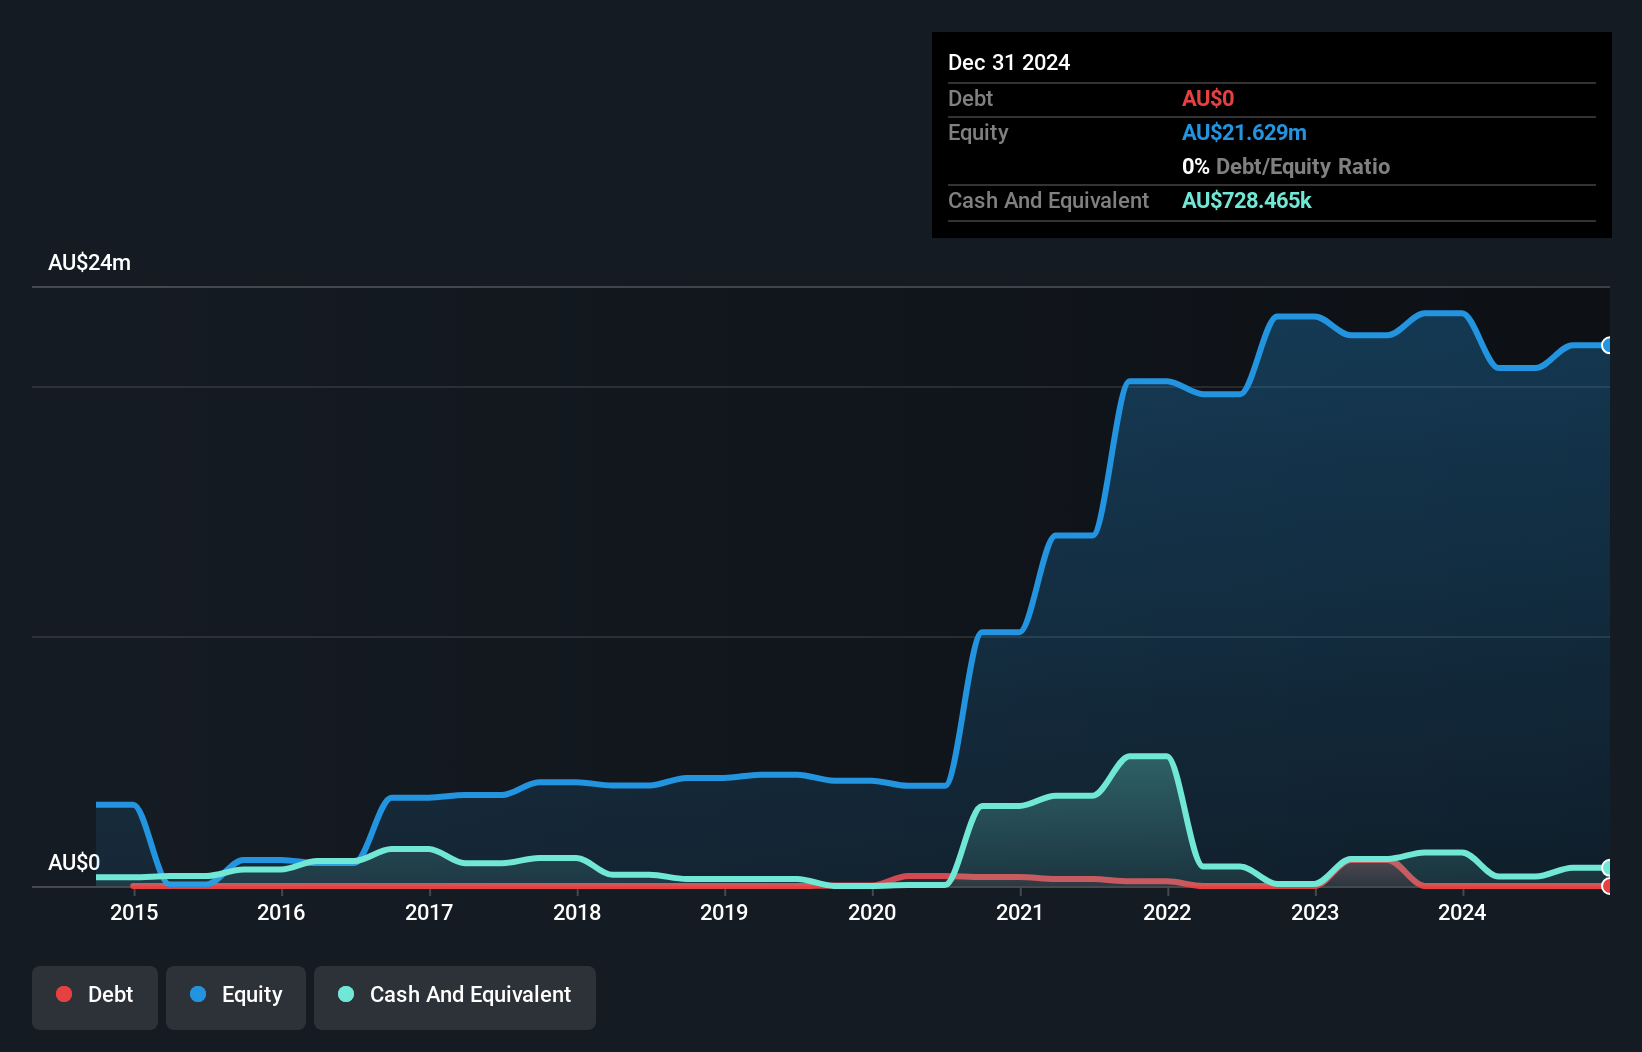
Overview: Estrella Resources Limited, with a market cap of A$63.04 million, is involved in the exploration of mineral resources in Australia and Timor-Leste through its subsidiaries.
Operations: Estrella Resources Limited does not report distinct revenue segments.
Market Cap: A$63.04M
Estrella Resources Limited, with a market cap of A$63.04 million, is currently pre-revenue and unprofitable. The company has experienced significant earnings declines over the past five years and reported a net loss of A$23.98 million for the year ended June 30, 2026. Despite having no debt and short-term assets exceeding liabilities, Estrella faces challenges with less than one year of cash runway if current cash flow trends continue. The management team is relatively new, with an average tenure of 1.9 years, indicating potential shifts in strategic direction as they navigate high volatility in share price performance.
- Dive into the specifics of Estrella Resources here with our thorough balance sheet health report.
- Examine Estrella Resources' past performance report to understand how it has performed in prior years.
LaserBond (ASX:LBL)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: LaserBond Limited is a surface engineering company in Australia that focuses on improving the performance and longevity of machinery components, with a market cap of A$63.06 million.
Operations: The company's revenue is derived from three segments: Products (A$17.46 million), Services (A$27.31 million), and Technology (A$3.40 million).
Market Cap: A$63.06M
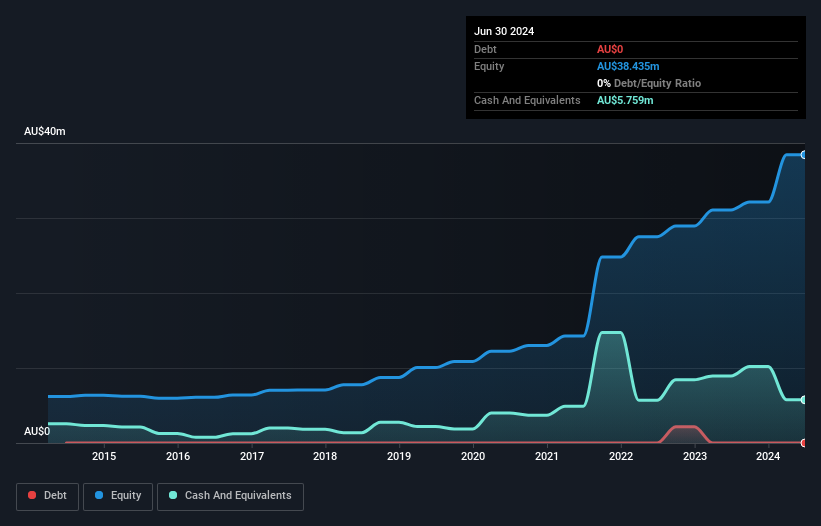
LaserBond Limited, with a market cap of A$63.06 million, reported annual sales of A$48.17 million and net income of A$4.91 million for the year ended June 30, 2026. The company has demonstrated strong earnings growth at 27.7% over the past year, surpassing its industry peers and maintaining high-quality earnings without incurring debt. Despite a relatively low return on equity at 11%, LaserBond is trading below estimated fair value by approximately 31%. Its dividend yield of 2.94% is not fully covered by free cash flow but remains sustainable given its stable financial position and seasoned board leadership.
- Get an in-depth perspective on LaserBond's performance by reading our balance sheet health report here.
- Assess LaserBond's future earnings estimates with our detailed growth reports.
PRL Global (ASX:PRG)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: PRL Global Ltd. operates in the mining, processing, and sale of phosphate rock, phosphate dust, and chalk across multiple continents including Africa, Asia, Europe, Australia, the United States, and Oceania with a market cap of A$161.70 million.
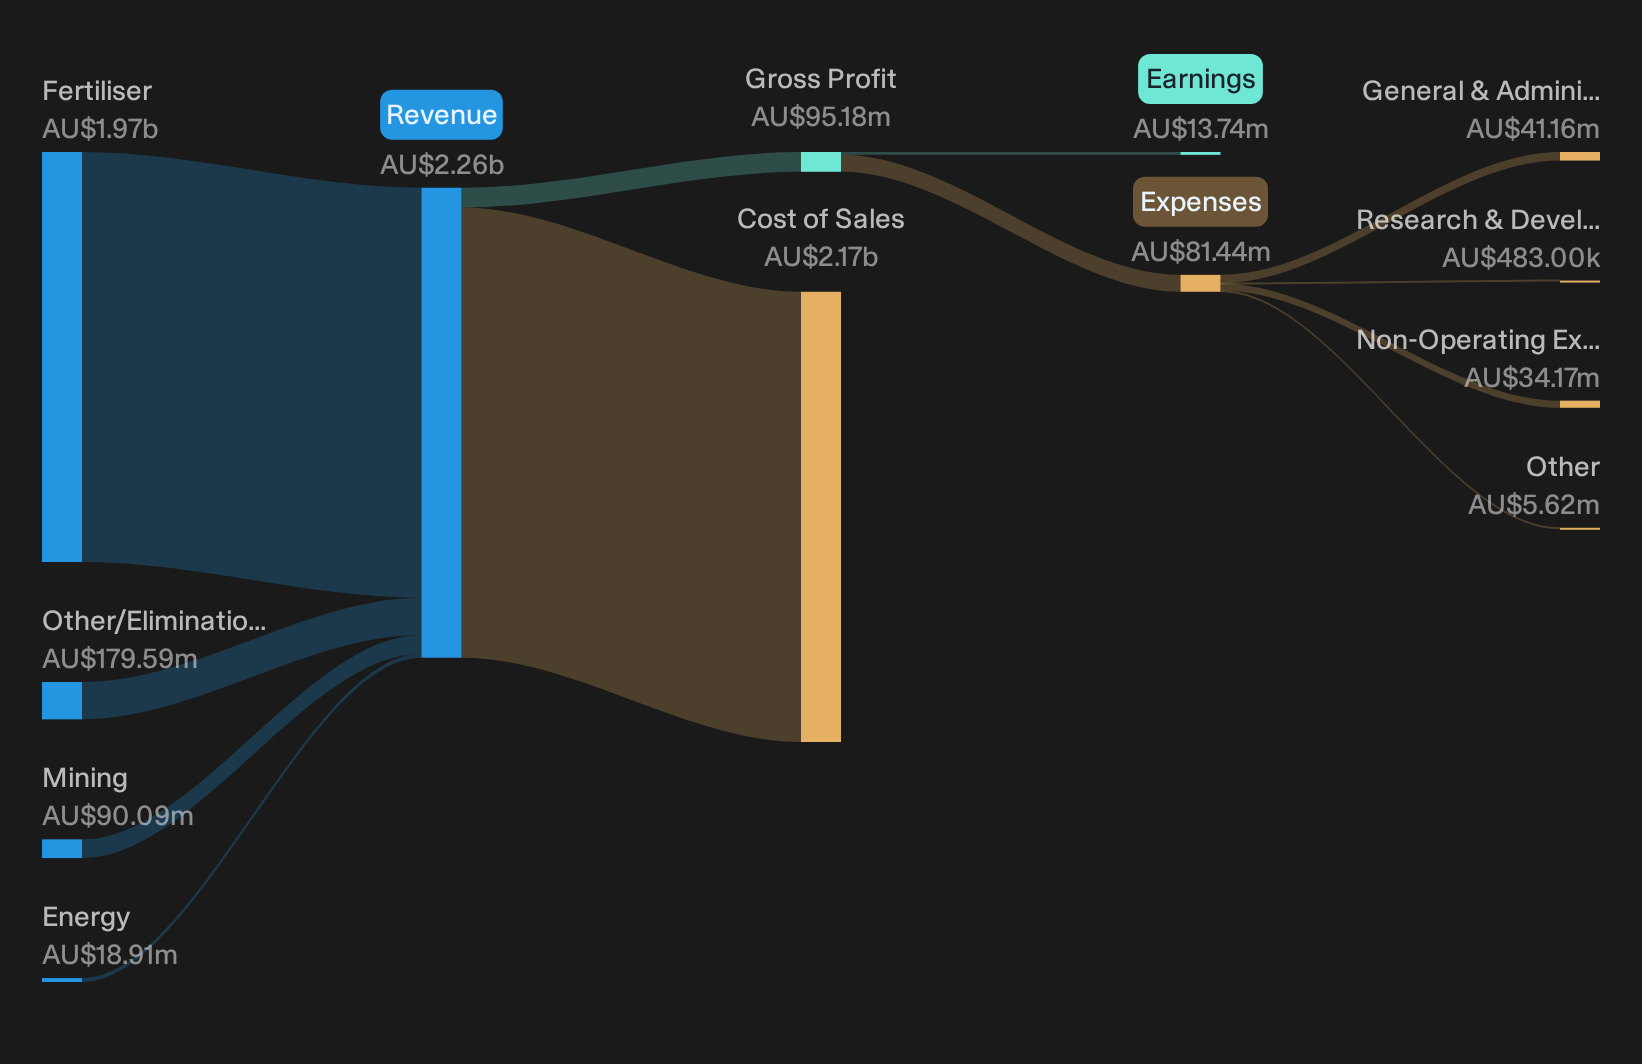
Operations: PRL Global's revenue is primarily derived from its Fertiliser segment, contributing A$1.97 billion, followed by Mining at A$90.09 million and Energy at A$18.91 million.
Market Cap: A$161.7M
PRL Global Ltd., with a market cap of A$161.70 million, reported sales of A$2.26 billion for the year ended June 30, 2026, primarily from its Fertiliser segment. Despite experiencing earnings growth of 26.1% over the past year and maintaining high-quality earnings, its net profit margin remains low at 0.6%. The company's debt is well covered by operating cash flow, though its net debt to equity ratio has increased to a satisfactory level of 20.2%. Recent changes include the passing of long-serving Director Dato’ Sri Tee Lip Sin which may impact board dynamics and strategic continuity moving forward.
- Click here to discover the nuances of PRL Global with our detailed analytical financial health report.
- Gain insights into PRL Global's historical outcomes by reviewing our past performance report.
Next Steps
- Jump into our full catalog of 415 ASX Penny Stocks here.
- Curious About Other Options? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com