


What Corning (GLW)'s Long Term Fiber Deals Mean For Shareholders
- Corning confirmed a quarterly dividend of US$0.28 per share payable on 11 December 2026 and presented its optical connectivity offerings at the OCP Global Summit 2026 in San Jose, highlighting its role in data center infrastructure.
- Long duration fiber and connectivity agreements tied to AI data centers and telecom networks, including Meta, Verizon and AT&T, underline how Corning is anchoring demand as supply shortfall forecasts tighten the specialized optical fiber market.
- This article examines how Corning's investment narrative is influenced by long term AI data center fiber demand that is associated with multiyear supply agreements.
Compare Corning's AI fiber story with other potential beneficiaries of the same build out by scanning our hand picked list of 55 AI infrastructure stocks today.
Corning Investment Narrative Recap
To own Corning, you need to believe the long Springboard plan and AI data center buildout can keep the Optical Communications engine and newer platforms like solar and photonics working in sync. The near term swing factor is whether long duration fiber contracts actually translate into consistent shipment volumes as capacity is added and customers phase their build schedules.
The biggest risk right now is execution across multiple high capital projects while carrying a meaningful debt load and accepting some equity dilution. Any stumble in ramping the solar business or disappointment around earnings quality, given the reliance on non GAAP metrics, could matter more to the stock in the short term than the latest AI headline.
The OCP Global Summit appearance is the announcement that matters most here because it puts Corning’s AI focused connectivity products directly in front of hyperscale buyers while TrendForce is flagging a fiber supply shortfall. Product demonstrations and technical roadmaps at that kind of industry forum feed into how buyers think about future rack designs and cabling choices.
That visibility ties back to the core catalysts investors are watching. Multi year Meta, Verizon and AT&T agreements already anchor demand into the late 2020s, and events like OCP are where those relationships can broaden into higher value connectivity and photonics content per data center. The payoff depends on Corning hitting production milestones and defending margins as volumes scale.
Corning's narrative projects US$29.4b revenue and US$5.7b earnings by 2029. This implies analysts are factoring in 20.1% yearly revenue growth and an earnings increase of US$3.8b from US$1.9b today.
Uncover why Corning's fair value indicates a 43% potential upside to its current price, a discount that could close sooner than expected.
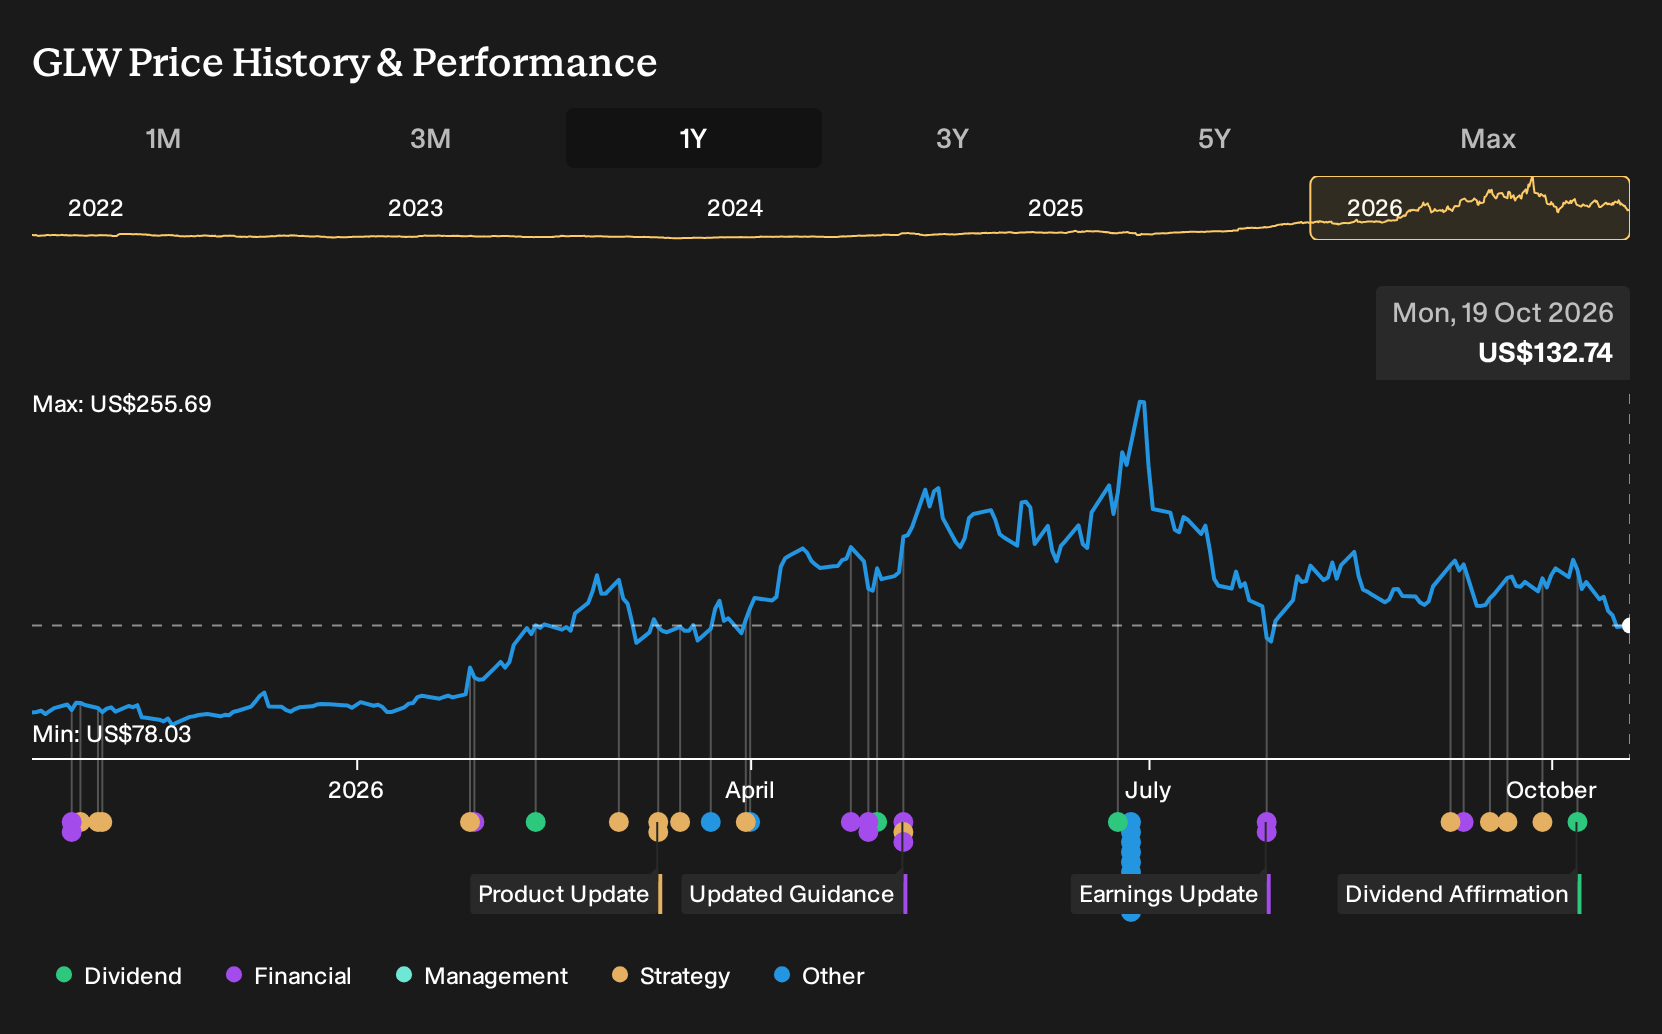
Exploring Other Perspectives
One bullish twist on Corning focuses on inside the box photonics as the real prize. That camp thinks the company could reach about US$33.0b in revenue and US$7.0b in earnings by 2029, far above consensus. These projections were set before the OCP Global Summit showing. You might see sentiment shift as analysts revisit both stories.
Explore 7 other Corning fair value estimates, including one that suggests as much as 79% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Corning research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corning's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corning?
Once you have a view on Corning, it can help to widen the lens and compare it with other companies that fit different risk and return profiles across the market.
- If you want potential mispricing with quality as a filter, scan a curated set of 35 high quality undervalued stocks that pair stronger fundamentals with appealing valuations.
- If income is your priority, focus on cash generation and payout strength by reviewing a shortlist of 8 dividend fortresses that offer higher yields with supporting fundamentals.
- If capital preservation matters most, concentrate on balance sheet resilience and earnings stability through a 32 resilient stocks with low risk scores that screens for sturdier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com