


Cloetta (OM:CLA B) Savings Story Keeps Undervaluation In Focus
Fresh interest in Cloetta (OM:CLA B) has been sparked by a recent Discounted Cash Flow assessment indicating its estimated intrinsic value sits well above the current share price. Operational savings and ongoing investments are reinforcing that valuation gap.
Cloetta’s recent strength has been hard to miss, with a 7 day share price return of 8.38% and a year to date share price gain of 39.30%. This performance lines up with growing interest in its cash flow profile.
Scan other potential mispriced opportunities alongside Cloetta by reviewing our hand picked list of 197 high quality undervalued stocks with solid cash flows and disciplined balance sheets.
Cloetta has rallied hard, yet the latest DCF work and analyst target still point to value well above the current SEK 56.25 price. How wide is the fair value range once those estimates are unpacked?
Most Popular Narrative: 4.7% Undervalued
Cloetta’s fair value in the most followed narrative is SEK 59, only slightly above the latest SEK 56.25 close. This keeps the focus on how durable its cash generation and brand investments really are over the next few years.
The analysts have a consensus price target of SEK59.0 for Cloetta based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be SEK9.6 billion, earnings will come to SEK904.7 million, and it would be trading on a PE ratio of 21.2x, assuming you use a discount rate of 5.3%.
See why 3 investors see Cloetta as 5% undervalued.
Result: Fair Value of SEK59 (UNDERVALUED)
Still, if confectionery pricing comes under political pressure or new formats like Lakerol MORE and Malaco Foamy Monkey lose steam, the Cloetta narrative could quickly look less comfortable.
Find out about the key risks to this Cloetta narrative.
Another View: Cloetta Through Market Ratios
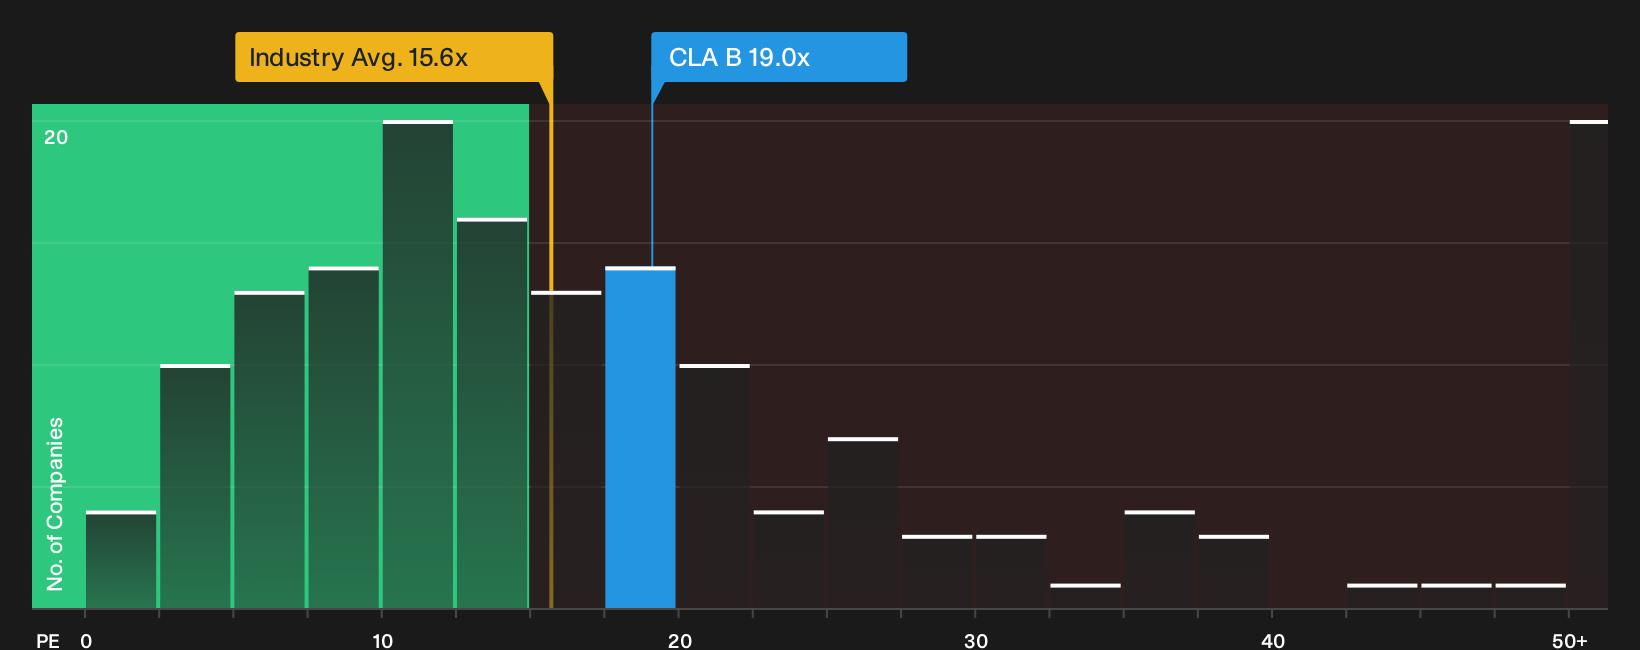
The cash flow work points to upside, but the market is telling a different story. Cloetta trades on a P/E of 19x, which is higher than the European Food group at 15.6x and above its own fair ratio of 16.1x. That premium can signal crowding rather than cushion. Which version of value do you trust more?
To see how that richer P/E plays out in practice, and where the market could move if sentiment cools, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on value and risk around Cloetta can be hard to read at speed, so move quickly, review the underlying data, and weigh both sides of the story by checking 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Cloetta?
Do not stop with Cloetta. Use the Simply Wall Street Screener to quickly surface other candidates that fit your criteria before the next move gets priced in.
- Target potential mispricing by reviewing companies that screen as high quality yet undervalued through the 197 high quality undervalued stocks.
- Protect the downside first by focusing on a 231 resilient stocks with low risk scores that highlights businesses with more resilient profiles.
- Get ahead of the crowd by scanning a 613 high quality undiscovered gems that surfaces under-followed stocks with strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com