


How Investors May Respond To CGN Mining (SEHK:1164) Premium P E Concerns
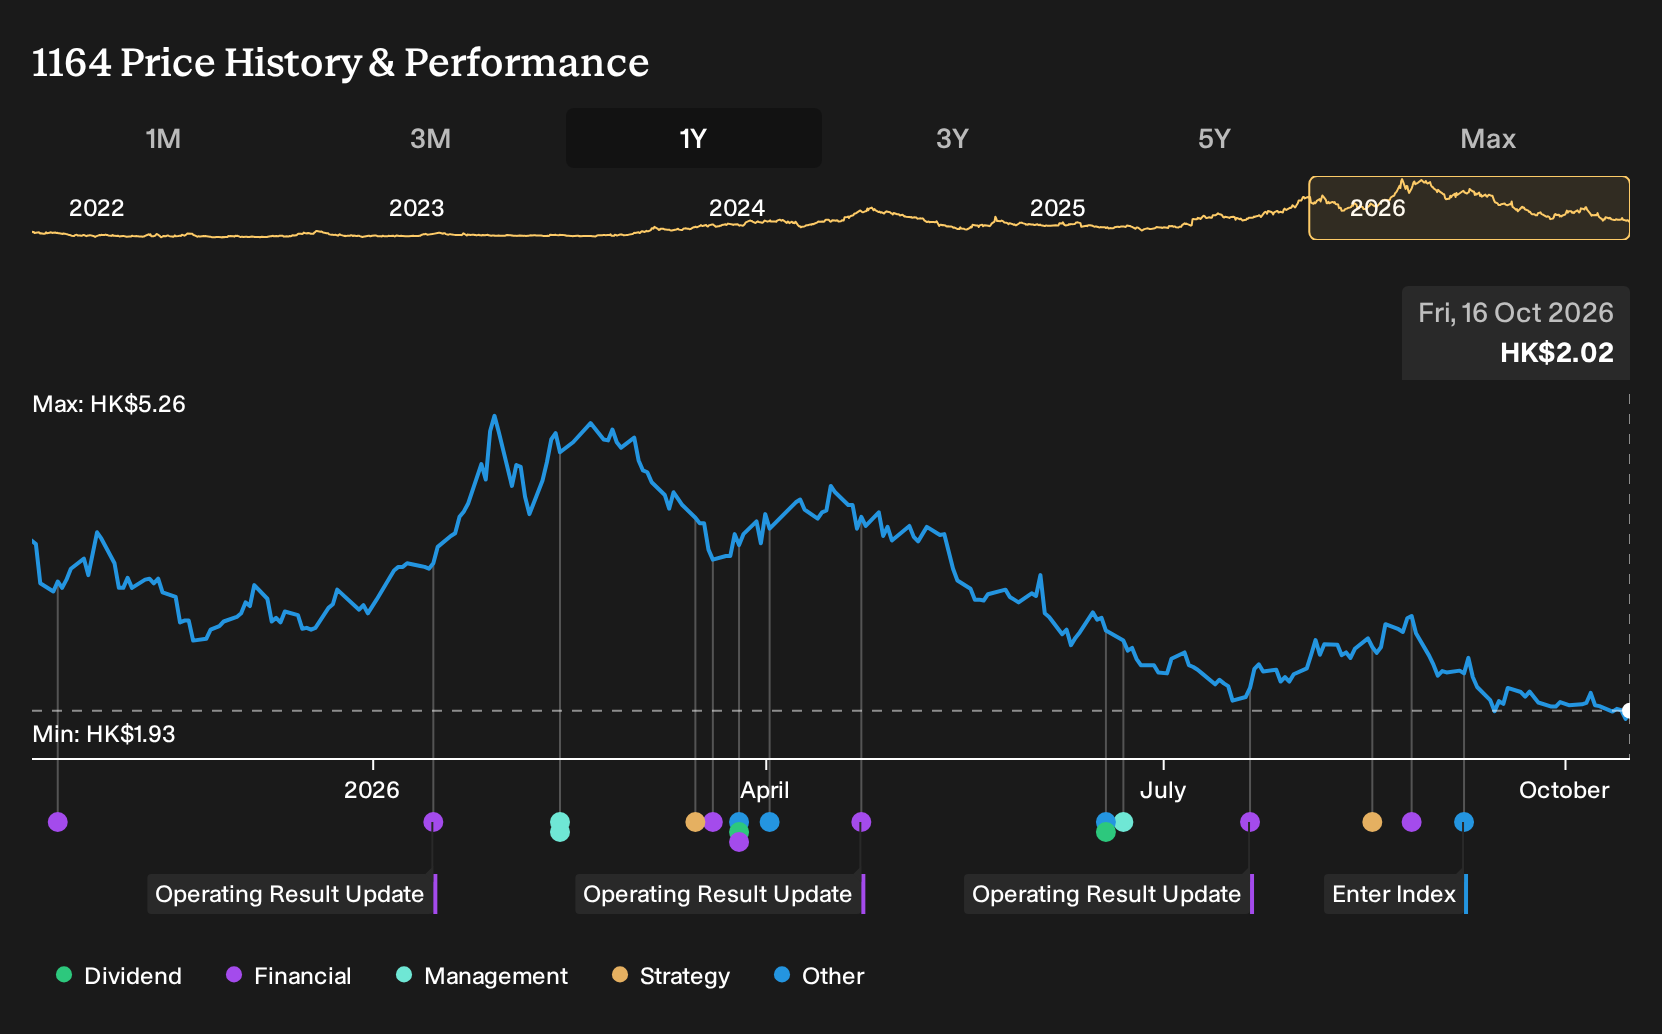
- CGN Mining has seen investor focus shift toward whether its current earnings and uranium operations justify a relatively high P/E level compared with peers, following several years of strong share price performance and a sharp pullback earlier in 2026.
- The key tension now centers on how CGN Mining balances its prior long term share gains with present questions about margins, execution quality and earnings support for that premium valuation.
- Attention now turns to how CGN Mining's premium P/E against sector peers could influence the broader investment narrative around the stock.
Compare CGN Mining's premium uranium valuation with other nuclear infrastructure opportunities by scanning the hand picked 16 nuclear energy infrastructure stocks that may share similar earnings profiles or pricing power.
What Is CGN Mining's Investment Narrative?
To own CGN Mining, you have to buy into a simple idea. The business is essentially a geared play on global uranium demand and pricing, with operations focused on sourcing and trading natural uranium into nuclear utilities across China, Europe and North America. A premium P/E near 34.9x only really makes sense if you think current earnings quality, recent 30.1% profit growth and improving 6.1% net margin can be sustained without heavy missteps in execution or capital deployment.
The sharp share price pullback this year has not changed those basic drivers, but it has brought them under a brighter spotlight. In the short term, the key questions are whether management can keep securing volumes and pricing that support that high multiple, and whether the balance of higher risk funding and a relatively new board introduces more volatility than the current HK$2.02 share price implies. Even so, there is one awkward pressure point that could matter far more than the recent correction if ...
There's only one way to know the right time to buy, sell or hold CGN Mining. Head to Simply Wall St's company report for the latest analysis of CGN Mining's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community only supplies two fair value angles on CGN Mining so far, ranging from HK$3.67 to HK$11.14 per share. That is a wide band. You are seeing how differently people model the same uranium story. Layer this onto recent share price volatility and it makes sense to review several viewpoints before deciding where you stand.
Explore another CGN Mining fair value estimate, including one that suggests there could be as much as 452% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CGN Mining research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for CGN Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CGN Mining's overall financial health at a glance.
Looking for more investment ideas beyond CGN Mining?
If you want to broaden your watchlist beyond CGN Mining, use the Simply Wall St Screener to compare different types of opportunities and stress test your approach across quality, value and risk.
- For investors who care most about valuation support and quality fundamentals, review a curated 196 high quality undervalued stocks that could align more closely with your return and risk expectations.
- If capital preservation and smoother portfolio swings matter to you, consider screening across 231 resilient stocks with low risk scores that may offer more resilient business profiles.
- When you want to focus on financially robust operators first and story second, start with a list of solid balance sheet and fundamentals (203 results) to anchor your research to stronger balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com