


Will Low P E Rerating Change Proximus Stock Narrative
- Proximus is currently trading at a P/E that sits well below the wider telecom sector, raising questions about how the market is treating its earnings power and the impact of ongoing cost-efficiency projects, asset disposals, and digitization efforts on its long term profitability and cash generation.
- The gap between Proximus's low P/E and its active push on automation, fiber investment support and asset sales highlights a tension between balance sheet pressure and self help measures that could shape how investors weigh its earnings quality against capital intensity and execution risk.
- We will now explore how Proximus's low P/E alongside its cost efficiency and digitization plans could influence the existing investment narrative.
Proximus Investment Narrative Recap
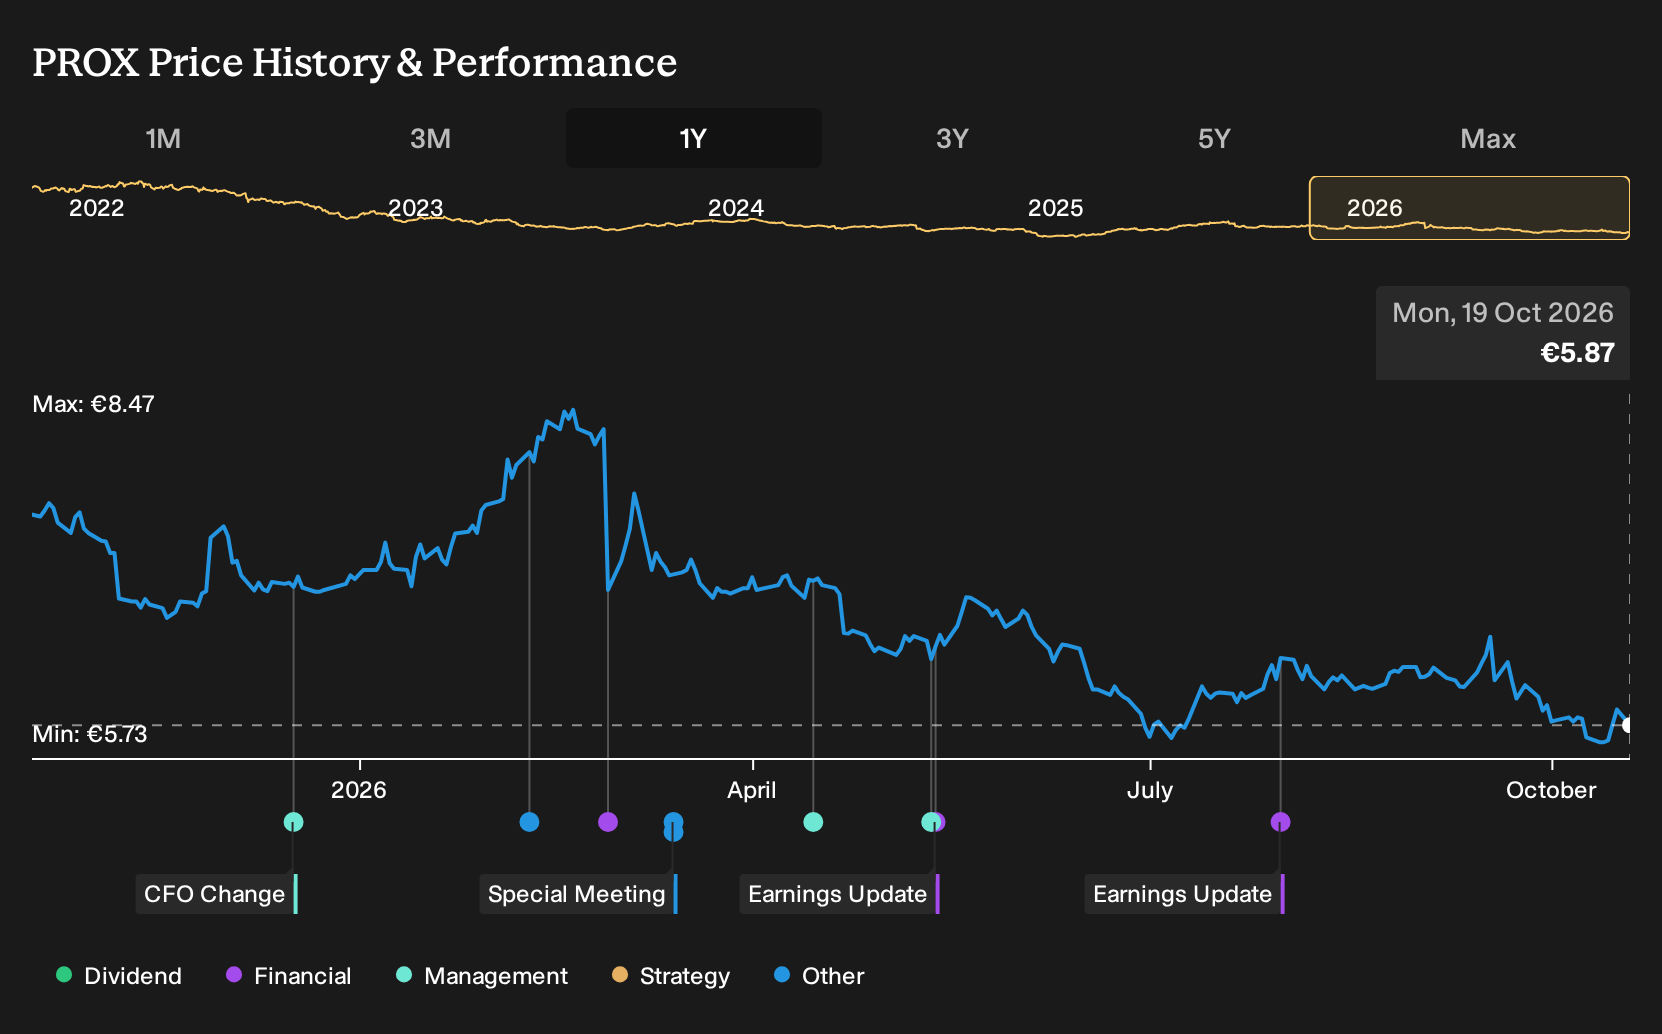
To own Proximus today, you need to believe that heavy fiber spending, cost programs and digitization can turn a low P/E into a cleaner earnings profile and healthier cash generation. The latest news around its discounted valuation versus telecom peers does not really change the near term story. The key near term swing factor still looks like execution on cost savings and automation.
The biggest risk feels more basic. Proximus is carrying a high level of debt while margins have already compressed, with profit margins at 5.9% compared with 8.8% last year. Competitive pressure from players like Digi and inflation on customer related costs keep the pressure on execution and on preserving free cash flow through this investment heavy phase.
With no fresh company announcements disclosed alongside this valuation discussion, the most relevant reference point is the existing plan around asset disposals and cost efficiency. Proximus has already highlighted non core asset sales as a way to support free cash flow while fiber CapEx runs at peak levels. That matters when leverage sits around 3x and rates remain a risk.
For catalysts, the story still hinges on whether these disposals, retirement linked efficiency moves and digitization actually feed through to lower operating expenses and a steadier cash profile. If competitive intensity from Digi or others undermines pricing, or if transformation costs stay high for longer, then the low P/E investors see today could simply reflect structurally lower earnings power rather than underpriced upside.
Proximus' current analyst narrative points to €6.2b in revenue and €342.2m in earnings by 2029, with revenue expected to remain fairly flat over the next 3 years. This implies earnings today of €398.0m and a decline of €55.8m to reach the 2029 consensus figure.
Uncover why Proximus' fair value indicates a 38% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One bearish twist you might want to study is how some analysts frame Proximus Global. The most pessimistic group saw 2029 earnings closer to €232.8 million on about €6.0b of revenue, versus today’s higher consensus figures, and viewed Global’s slower reset as a real drag. Those forecasts predate the latest valuation focus, so they may shift.
Explore 2 other Proximus fair value estimates, including one that suggests it could be worth just €8.11!
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Proximus research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Proximus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Proximus' overall financial health at a glance.
Looking for more investment ideas beyond Proximus?
If the Proximus setup has you thinking about what else might be mispriced or overlooked, it can help to scan a broader field of opportunities with different risk and income profiles.
- For investors who want resilient businesses with stronger balance sheets, consider screening through a list of solid balance sheet and fundamentals (203 results) that can handle tougher conditions without stressing their finances.
- If steadier income is a priority, focus on higher yielding payers by reviewing a curated 217 dividend fortresses that aim to combine income with more durable fundamentals.
- To widen the opportunity set beyond widely followed tickers, cast the net over a 613 high quality undiscovered gems that blend quality metrics with underfollowed profiles the market may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com