


Teleflex (TFX) Completes BIOMAG LL Enrollment, Is The Stock Still A Bargain?
Teleflex (TFX) stock is back in focus after the company reported full patient enrollment in its BIOMAG-LL Clinical Study, a premarket trial assessing the Freesolve resorbable magnesium scaffold for longer coronary lesions.
Teleflex shares have picked up some short term momentum, with a 1-day share price return of 1.72% and a 7-day move of 3.76%, even though the 90-day share price return declined 3.39% and the 3-year total shareholder return fell 28.60%. Recent attention has centred on clinical and product pipeline updates like the BIOMAG-LL enrollment milestone. The stock trades at US$130.43 after a year-to-date share price return of 6.56% and a 1-year total shareholder return of 1.03%, as investors appear to be weighing long term execution against a much weaker 5-year total shareholder return that declined 64.07%.
Spot similar late-stage clinical and medtech pipeline stories by scanning our curated list of 33 healthcare AI stocks, which are also turning specialist research into potential revenue catalysts.After Teleflex stock’s short burst higher, the real debate now is simple: Is this just a partial reset after years of weak total returns, or is most of the easy upside already in the rear-view mirror as the valuation resets?
Most Popular Narrative: 16% Undervalued
Teleflex is pegged with a fair value of $154.73 against a last close of $130.43, which puts the current debate squarely on whether the market is underestimating the balance of margin targets, capital returns and clinical milestones like Freesolve.
The multiyear restructuring program that targets about US$50 million in annual pretax cost savings by mid 2028, combined with plans to offset roughly US$90 million of stranded costs and move steady state adjusted operating margin from about 19% toward roughly 23%, provides a clear path to higher operating margins.
See why 8 investors see Teleflex as 16% undervalued.
Result: Fair Value of $154.73 (UNDERVALUED)
Still, the Teleflex narrative depends heavily on fixing BIOTRONIK integration issues and on actually delivering the planned stranded cost offsets and restructuring savings.
Find out about the key risks to this Teleflex narrative.
Another view on Teleflex valuation
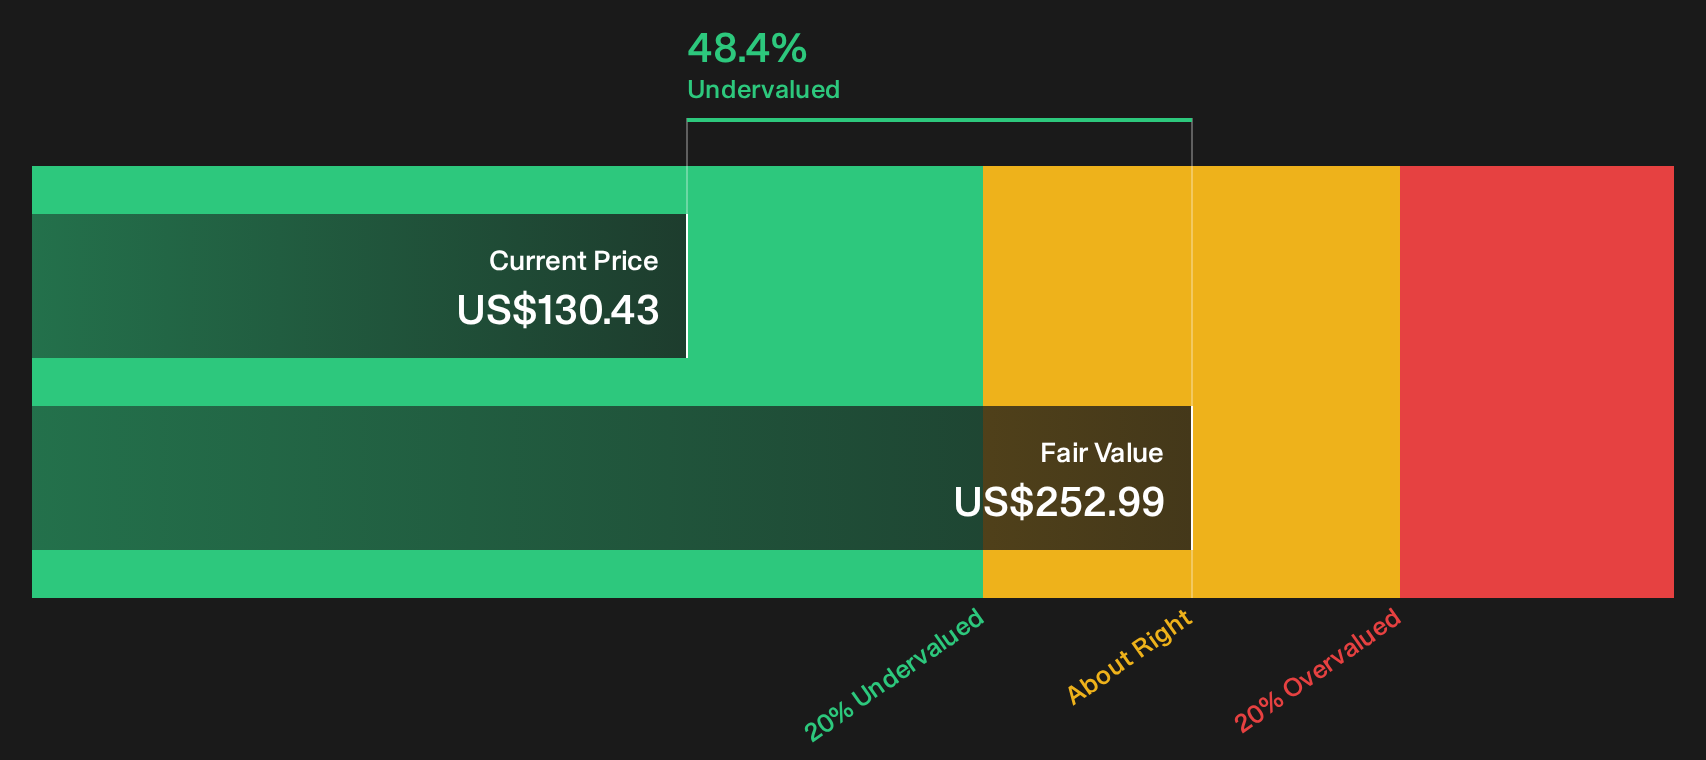
The SWS DCF model presents a much stronger picture for Teleflex. On that framework, TFX at $130.43 sits 48.4% below an estimated future cash flow value of $252.99. This represents a far deeper gap than the 16% discount to the $154.73 fair value. Which lens should carry more weight in your own work?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views like this are exactly when your own work matters most. Move quickly, pressure test Teleflex against your framework and weigh the 2 key rewards and 1 important warning sign.
Looking for more Teleflex-sized investment ideas?
If Teleflex has your attention, do not stop with a single ticker. Broaden your watchlist now and give yourself more ways to put your thesis to work.
- Target potential mispricings by scanning companies flagged as 33 high quality undervalued stocks before other investors crowd the trade.
- Prioritize resilience by checking a list of solid balance sheet and fundamentals (25 results) that can help you focus on sturdier businesses when conditions get choppy.
- Stay ahead of the crowd by reviewing 20 high quality undiscovered gems that the broader market may not be paying attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com