


NEXTDC (ASX:NXT) Selloff Puts Its Rich Valuation And Earnings Story Under The Microscope
Recent commentary around NEXTDC (ASX:NXT) focuses on a sharp share price pullback and a P/E of 85.0x, prompting questions about whether its capital intensive data centre expansion can underpin earnings.
Across the past year, NEXTDC has moved from strong optimism to a more cautious stance. The share price is down 19.2% over 30 days and has delivered a 42.2% decline in 1 year total shareholder return, signalling fading momentum as investors reassess growth and risk around its high P/E valuation.
Pressure test NEXTDC against peers by scanning a curated set of 55 AI infrastructure stocks that face similar capital intensity and valuation expectations.
After a 42.2% slide in 1-year total shareholder return and a P/E of 85.0x, NEXTDC now trades well below analyst targets. Where does a fair value band realistically fall between that price and the estimates spread?
Most Popular Narrative: 54% Undervalued
On the most followed narrative, NEXTDC screens as undervalued, with a fair value of A$20.12 against the last close at A$9.18. This puts the current share price well below that narrative band while still asking investors to underwrite an aggressive earnings path.
Rapid growth in cloud and AI workloads is supporting long-duration contracts with large technology customers and neocloud providers. This can increase contracted utilization and underpin higher net revenue visibility over the rest of the decade.
See why 19 investors see NEXTDC as 54% undervalued.
Result: Fair Value of A$20.12 (UNDERVALUED)
Still, the bullish NEXTDC story leans heavily on huge capex commitments and a concentrated AI and cloud customer base, where deployment delays or funding costs could quickly weaken that upside case.
Find out about the key risks to this NEXTDC narrative.
Another View: NEXTDC Through The P/E Lens
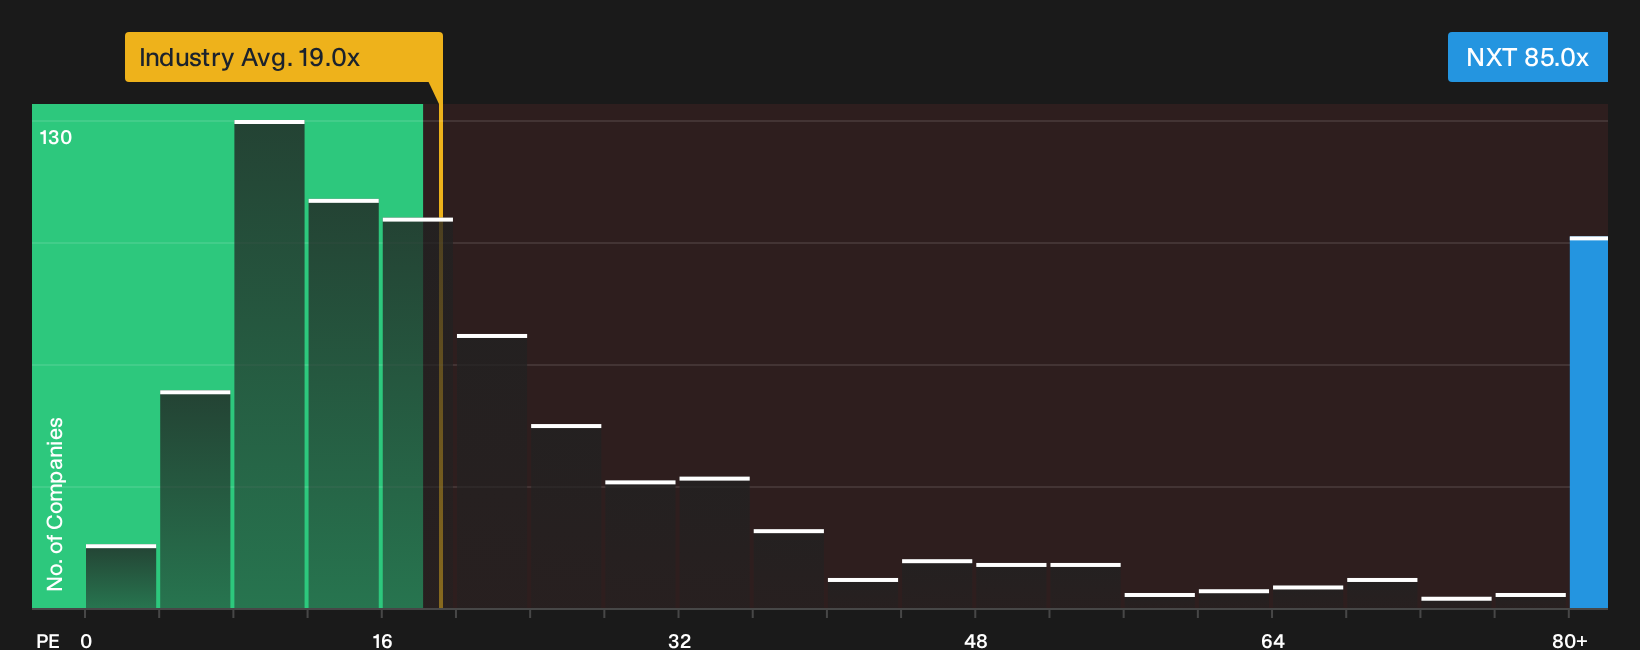
The analyst narrative paints NEXTDC as 54% undervalued at a fair value of A$20.12. The current P/E of 85x tells a very different story. It is well above the global IT sector at 19x, its peer group at 56.6x, and even the fair ratio of 21.9x that the market could feasibly drift toward over time.
That gap means anyone paying today’s multiple is accepting elevated valuation risk if expectations around revenue growth, earnings and AI demand reset closer to sector norms. The real question is whether you are comfortable underwriting such a premium for a capital heavy rollout that analysts expect to deliver declining earnings over the next 3 years.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around NEXTDC is clearly split, and the clock is ticking for you to decide which side of that debate you prefer. Weigh the upside case against the red flags by running through the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond NEXTDC?
Do not stop at NEXTDC. Use the wider market to your advantage by scanning focused stock lists that match the kind of risk and opportunity you actually want.
- Target resilient compounding potential by reviewing companies with steady fundamentals through a 4 high quality undervalued stocks that filters for quality and price discipline.
- Prioritise sleep-at-night resilience by running through a 6 resilient stocks with low risk scores that highlights businesses with stronger risk scores and sturdier profiles.
- Hunt for early-stage potential by checking a 23 elite penny stocks with strong financials that focuses on smaller stocks with more robust financial traits, not just hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com