


What Devon Energy Holders Bought Into
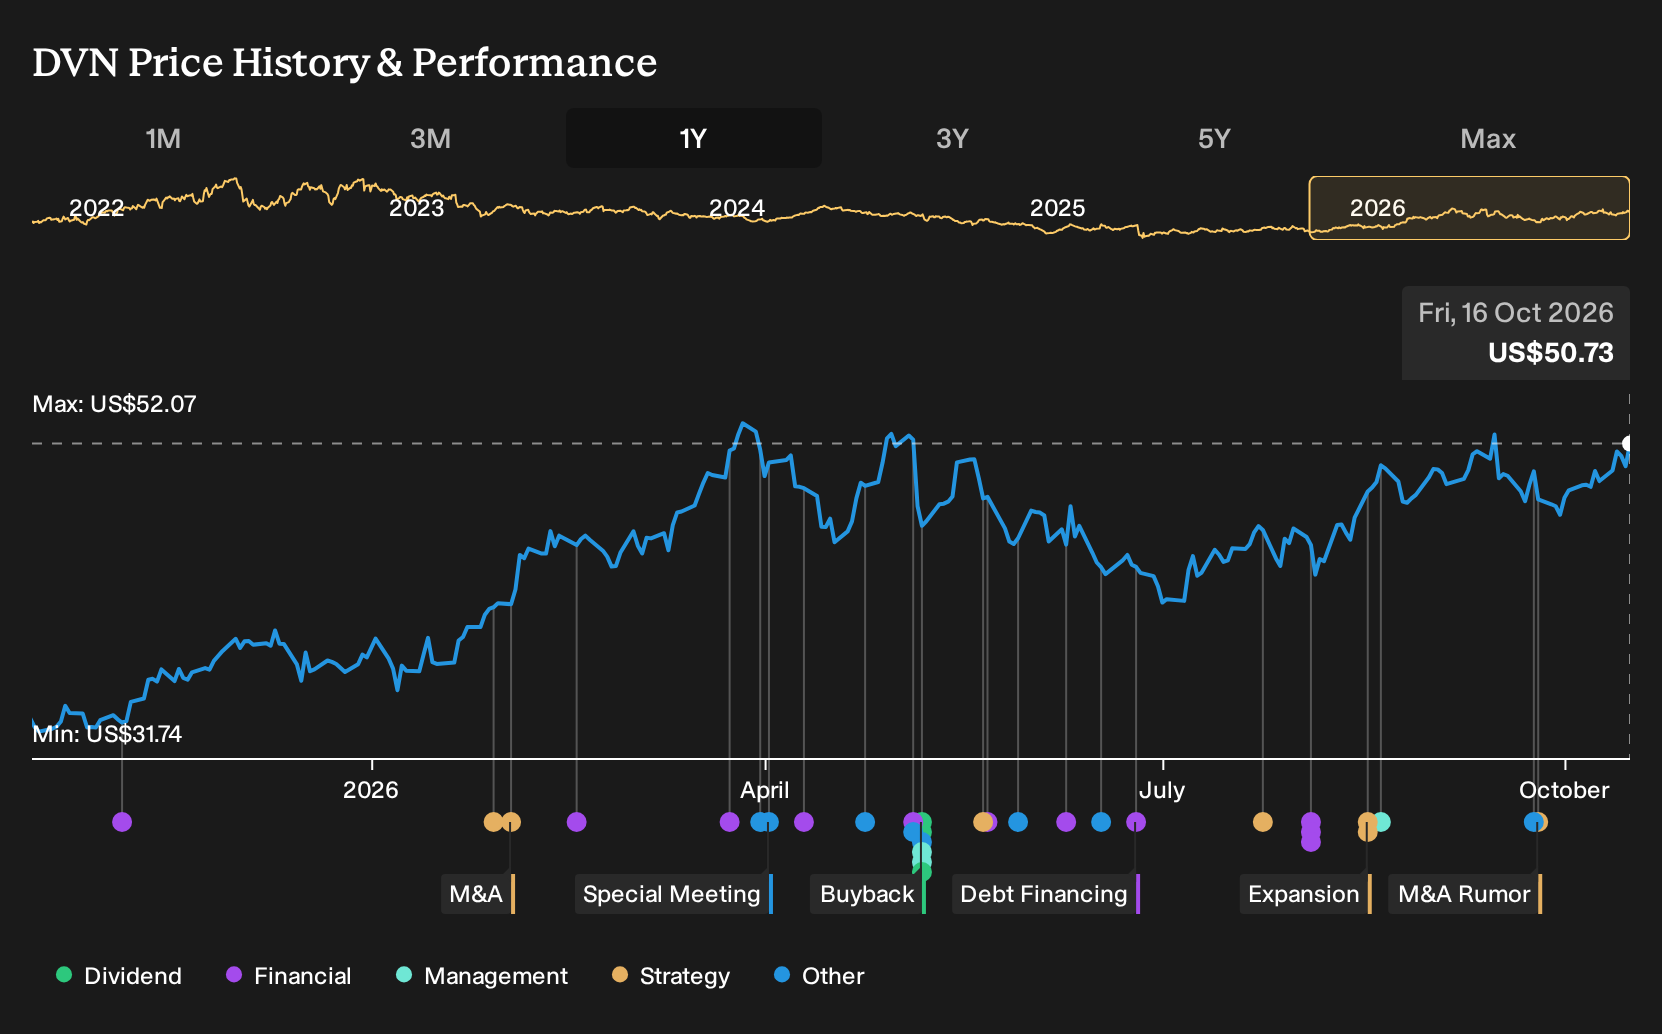
If Devon Energy was on your watchlist instead of in your portfolio, the recent move may feel like a missed shot. Holding Devon Energy over the past year would have returned 62.9%, including dividends. The question is what, if anything, in the October 2025 playbook on AI driven efficiency, midstream investments and a 10.7x future P/E assumption could have flagged that this operational reset might be bigger than a routine shale efficiency story?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Devon Energy. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Devon Energy
The shares cost US$32.03 at the start of the period, which left investors deciding how much faith to place in Devon Energy's efficiency story versus its exposure to shale and regulation.
The bullish narrative saw fair value at US$45.48, built on assumptions of 6.3% annual revenue growth and a 15.6% profit margin supported by AI driven drilling and midstream investments that were expected to stabilise cash flows.
The cautious view treated those same moves as vulnerable to risks around U.S. shale decline rates, water regulation and ESG pressure, and some investors used a lower assumed multiple or slower improvement when setting their own fair value marks.
What The Results Changed In The Devon Energy Story
Q2 2026 did the heavy lifting for Devon Energy, with revenue at US$6.6b and net income at US$1.9b, and net margin moving from 22.2% to 28.8%. That profitability shift leans toward the optimistic case that focused on AI assisted efficiency and midstream moves, although activist pressure and asset sale debates kept the more cautious governance and portfolio concerns alive. Overall, the evidence cut both ways.
The hinge assumption here was margin durability. For any other stock built on an efficiency pitch, you would track net margin against the original forecast each reporting season and test whether buybacks and capital returns follow sustained free cash flow rather than hope.
What Devon Energy's Price Now Asks You To Believe
Devon Energy trades at US$50.73, with this Narrative's Fair Value set above that level based on its own framework rather than a settled truth. The current view leans heavily on AI driven operating gains, deeper Delaware Basin inventory and new midstream links to Gulf Coast buyers.
At today's price, you would be judging whether markets fully account for merger synergies, portfolio simplification and cash returns that hinge on efficient U.S. shale execution. The Narrative argues investors are still not fully crediting the scale and durability of that free cash flow profile.
"The view on Devon Energy has been reviewed and reaffirmed. The updated thesis now focuses on merger driven cost synergies, expanded AI deployment and midstream commitments, which together aim to reduce unit costs, support future production plans and steady cash flows."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking One Step Beyond Devon
Devon Energy focuses on efficient drilling and development decisions. You could look one step away and ask who simply collects when that activity happens.
Another model centers on owning mineral rights rather than running rigs. It still participates in production while others fund and operate the wells.
No drilling budget, service crews or exploration program sit on its books. The operator carries the heavy capital load while the royalty holder receives its contractual share.
For someone studying Devon Energy, that different way of touching the same rock raises a fresh question. How might a pure royalty approach react when development across a basin speeds up or slows down?
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 24% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com