


Alibaba Group Holding (BABA) After Its ESOP Filing And The Undervalued Narrative
Alibaba Group Holding (BABA) recently filed a US$1.336b shelf registration for up to 100,000,000 common shares tied to its employee stock ownership plan, raising fresh questions about dilution, incentives, and how investors should interpret the move.
Set against a US$109.11 share price, Alibaba Group Holding has seen its share price fall 3.65% over the past month and 7.51% over the past quarter, with year to date share price return down 29.94% and 1 year total shareholder return down 36.54%. This comes even as headlines have focused on new AliExpress perks in Europe, embodied AI trials through Amap in Macau, and its role as a cornerstone investor in Suzhou Dongshan Precision Manufacturing's planned Hong Kong listing. The new US$1.336b ESOP shelf registration is therefore landing in a market where momentum has been fading rather than building.
Spot opportunities beyond Alibaba Group Holding by scanning a curated field of under pressure but financially solid companies in the 33 high quality undervalued stocks.Alibaba Group Holding is still a large, profitable platform business. However, the fresh US$1.336b ESOP shelf and a sharply weaker share price put the focus squarely on one thing: Is this strength already fully reflected in today’s valuation?
Most Popular Narrative: 54.9% Undervalued
Measured against the last close at $109.11, the most followed narrative on Alibaba Group Holding pins fair value at $241.91, which frames the new ESOP shelf against a business that some investors see as materially mispriced.
Alibaba is one of the few large-cap companies in the world where there appears to be a meaningful gap between market perception and the underlying value of its assets. At current prices, many investors still view Alibaba primarily as a Chinese e-commerce company. However, a closer look reveals a much broader technology ecosystem with exposure to some of the most important long-term trends in AI, cloud computing, fintech, and digital infrastructure.
See why 16 investors see Alibaba Group Holding as 55% undervalued.
Result: Fair Value of $241.91 (UNDERVALUED)
Still, the Alibaba Group Holding thesis hinges on two pressure points that could break the story quickly. A sharper swing in China sentiment, or renewed regulatory action around Ant Group, would challenge any argument that the gap between price and estimated value will close on a straightforward path.
Find out about the key risks to this Alibaba Group Holding narrative.
Another View On Alibaba Group Holding’s Valuation
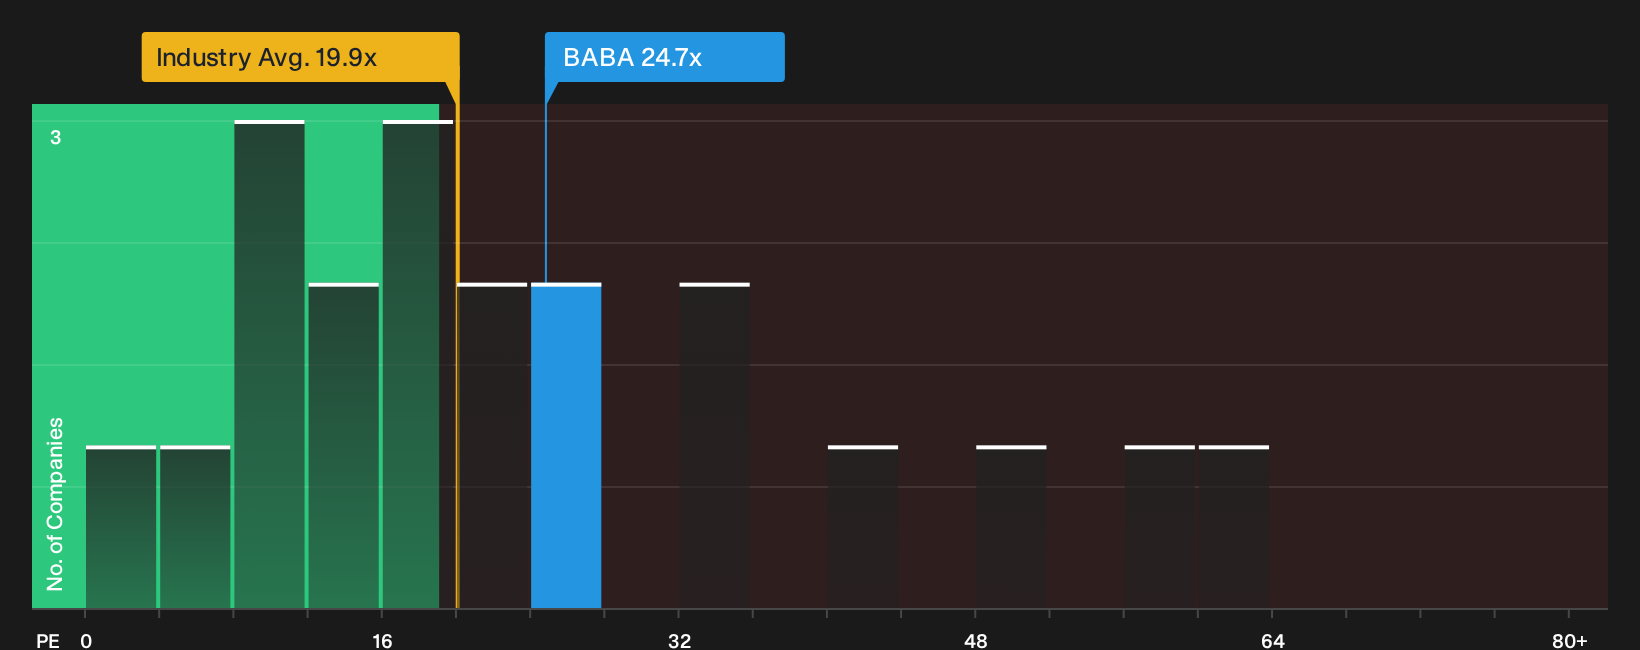
On earnings multiples, Alibaba Group Holding looks less clear cut. The stock trades on a P/E of 24.7x, which is higher than the global Multiline Retail industry at 19.9x, yet below peers on 29.4x and a fair ratio estimate of 34.1x. That mix suggests both valuation risk and potential upside. Which reference point matters most for you as an investor?
For a closer look at what these relative valuation signals could imply for Alibaba Group Holding over time, see what the numbers say in our valuation breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Alibaba Group Holding feel hard to reconcile, that is exactly why the data matters more than the headlines. Take a moment to weigh both sides, and then use the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Alibaba Group Holding?
If Alibaba Group Holding feels hard to pin down, broaden your field of vision. Fresh ideas often come from comparing a few very different opportunities side by side.
Use these screeners to quickly surface focused shortlists, then pressure test each idea against your own risk tolerance and return expectations.
- Target potential value rebounds by scanning a curated pool of under pressure but financially healthy stocks with the 33 high quality undervalued stocks.
- Prioritise resilience by filtering for companies with stronger finances and sturdier balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Hunt for lesser known opportunities with solid fundamentals and room to gain market attention through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com