


Willis Towers Watson (WTW) Following Its AI Rollout Faces A Fresh Valuation Test
Willis Towers Watson (WTW) has rolled out an AI-powered job matching feature inside its Rewards AI platform, aiming to help compensation teams keep roles aligned with pay benchmarks as job content shifts.
Recent trading has backed up that story. The share price is at US$315.49 after a 1-day share price return of 1.65%, a 7-day share price return of 5.72% and a 90-day share price return of 9.23%, even though the year-to-date share price return is down 3.30% and the 1-year total shareholder return has slipped 3.16%. The 3-year total shareholder return of 60.91% points to stronger gains over a longer holding period and suggests that momentum has re-accelerated in the short term as investors weigh product launches like Rewards AI job matching alongside the broader performance record.
Spot opportunities around Willis Towers Watson's AI push by scanning a curated 39 profitable AI stocks that aren't just burning cash that combine real earnings power with exposure to similar technology themes.Bulls highlight Willis Towers Watson’s AI initiatives and its long-term return record as support for a richer valuation multiple. Bears focus on the softer one-year performance. Which side do the current valuation indicators appear to favor?
Most Popular Narrative: 15% Undervalued
Against the last close of $315.49, the most followed narrative points to a fair value of $370.63, which leans toward a richer free cash flow story for Willis Towers Watson.
The analysts have a consensus price target of $370.63 for Willis Towers Watson based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $11.9 billion, earnings will come to $2.0 billion, and it would be trading on a PE ratio of 19.6x, assuming you use a discount rate of 7.7%.
See why 7 investors see Willis Towers Watson as 15% undervalued.
Result: Fair Value of $370.63 (UNDERVALUED)
Still, the story can break if AI adoption in broking and consulting compresses fees faster than Willis Towers Watson cuts costs, or if softening insurance pricing undercuts Risk & Broking momentum.
Find out about the key risks to this Willis Towers Watson narrative.
Another View: What Willis Towers Watson’s P/E Is Saying
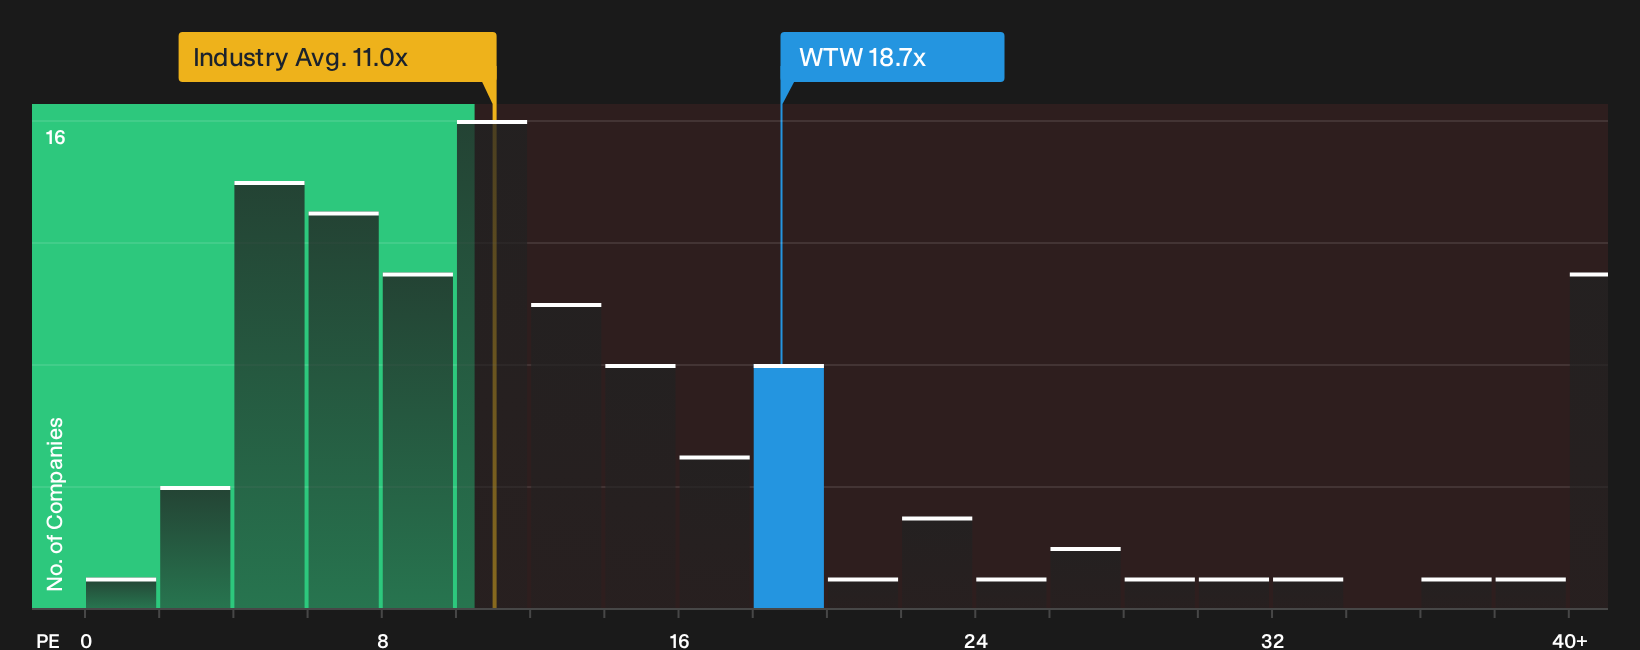
A different lens tells a tighter story. Willis Towers Watson trades on a P/E of 18.7x, while the US Insurance industry sits at 11x and the fair ratio sits at 12.8x. That gap points to richer expectations and less room for error if growth or margins disappoint.
Our P/E based view says the stock looks expensive relative to both peers and the fair ratio. This suggests the market could eventually lean toward lower multiples if sentiment cools. Does that premium feel justified given the current growth forecasts you are using?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mixed tone in this Willis Towers Watson story and wondering which side you land on? Act quickly, analyze the data in detail, and weigh both sides using the 3 key rewards and 1 important warning sign.
Ready for more Willis Towers Watson style ideas?
If this Willis Towers Watson story has you thinking harder about price, quality, and risk, do not stop with just one ticker. Use the Simply Wall Street Screener to line up a watchlist that actually fits your plan, before the market moves on without you.
- Target potential mispricing by lining up companies that look attractively valued against quality metrics using the 33 high quality undervalued stocks.
- Prioritize resilience by scanning a 32 resilient stocks with low risk scores that can help you focus on businesses with more measured risk profiles.
- Spot under-the-radar opportunities by reviewing a 20 high quality undiscovered gems that filters for strong fundamentals the crowd may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com