


What Teledyne Technologies (TDY)'s Airborne AI Software Launch Means For Shareholders
- Teledyne Technologies, through Teledyne FLIR OEM, recently launched Prism A-ISR, an AI-enabled embedded software module that provides real-time air-to-ground object detection, classification, and tracking for uncrewed aircraft systems and other airborne ISR platforms using multispectral sensor data and advanced image processing.
- The new Prism A-ISR module is tailored for NVIDIA and Qualcomm embedded AI hardware and links directly into Teledyne FLIR thermal camera families. This can deepen the company’s role in mission-critical defense ISR workflows and tighten integration between its sensors, software, and OEM customers.
- We will now look at how Teledyne Technologies' AI driven airborne ISR software release could influence the broader investment narrative.
Scan how Teledyne Technologies’ ISR-focused AI fits into a wider defense tech trend by reviewing a curated set of 55 AI infrastructure stocks powering next-generation sensing and compute workloads.
Teledyne Technologies Investment Narrative Recap
For a shareholder in Teledyne Technologies, the core belief is that a focused portfolio in sensing, imaging, and defense electronics can keep turning a large funded backlog into higher quality earnings. The Prism A ISR launch fits that story because it keeps Teledyne’s FLIR assets aligned with unmanned and ISR demand rather than opening a new direction for the group.
The most important shorter term swing factor still looks like execution on margins and delivery against roughly US$6.53b of 2026 revenue expectations, not this one software release. Key risk remains cost pressure in components and materials, plus any mix shift or acquisition impact that drags on company wide margin expansion.
Among recent developments, the planned Varex Imaging acquisition is most relevant for thinking about catalysts around Prism A ISR. Teledyne Technologies is leaning on its balance sheet flexibility and niche positions in sensing to broaden health related imaging toward roughly US$1.2b of revenue, while still investing in defense focused software like Prism.
That combination matters for you because execution on Varex integration and margin improvement could have a bigger financial effect than any single product. Prism A ISR then looks like an incremental proof point that Teledyne’s imaging and software stack remains tightly aligned with unmanned, space, and sensing programs that underpin multi year defense revenue expectations.
Teledyne Technologies' narrative projects US$7.4b revenue and US$1.2b earnings by 2029. That path reflects analysts' assumption of 5.2% yearly revenue growth and an earnings increase of about US$225m from US$974.8m today.
Uncover why Teledyne Technologies' fair value indicates a 23% potential upside to its current price. This opportunity could narrow quickly as sentiment catches up.
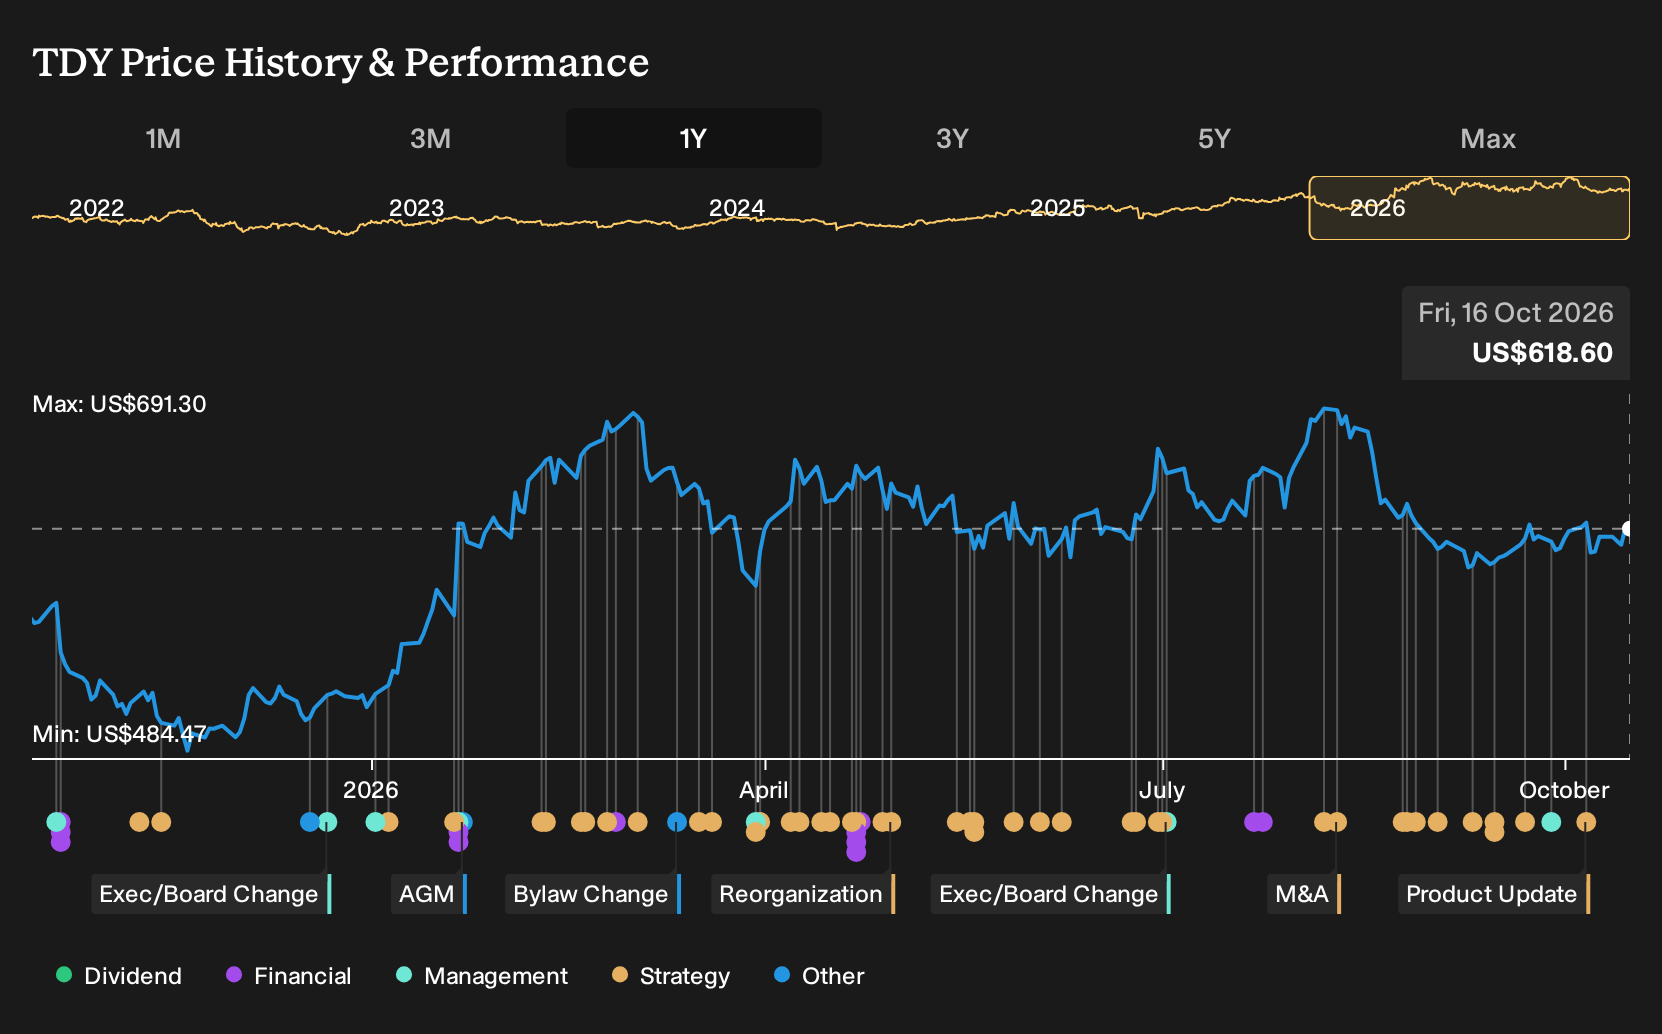
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$599 and US$758 per share, which already shows how far apart retail forecasts can be. When you layer on risks around supply chain costs, potential margin dilution, and defense program execution, you get a wide field of outcomes for Teledyne Technologies that is worth exploring from several angles.
Explore another Teledyne Technologies fair value estimate, including one that suggests as much as 23% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Teledyne Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teledyne Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teledyne Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Teledyne Technologies?
If you want to put Teledyne Technologies in context, it helps to scan a wider field of opportunities. Use the Simply Wall St Screener to find other stocks that fit the type of risk and return profile you are aiming for, then compare them side by side with TDY.
- If capital preservation and steadier profiles matter most to you, hone in on 32 resilient stocks with low risk scores that score well on resilience metrics and more conservative risk factors.
- If income is your priority, focus on companies in 8 dividend fortresses that pair higher yields with a more robust record of distributions.
- If you like finding potential early stage outliers, cast a wider net across 20 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com