


How Investors Are Reacting To Kalmar Oyj (HLSE:KALMAR) Port Service Deal
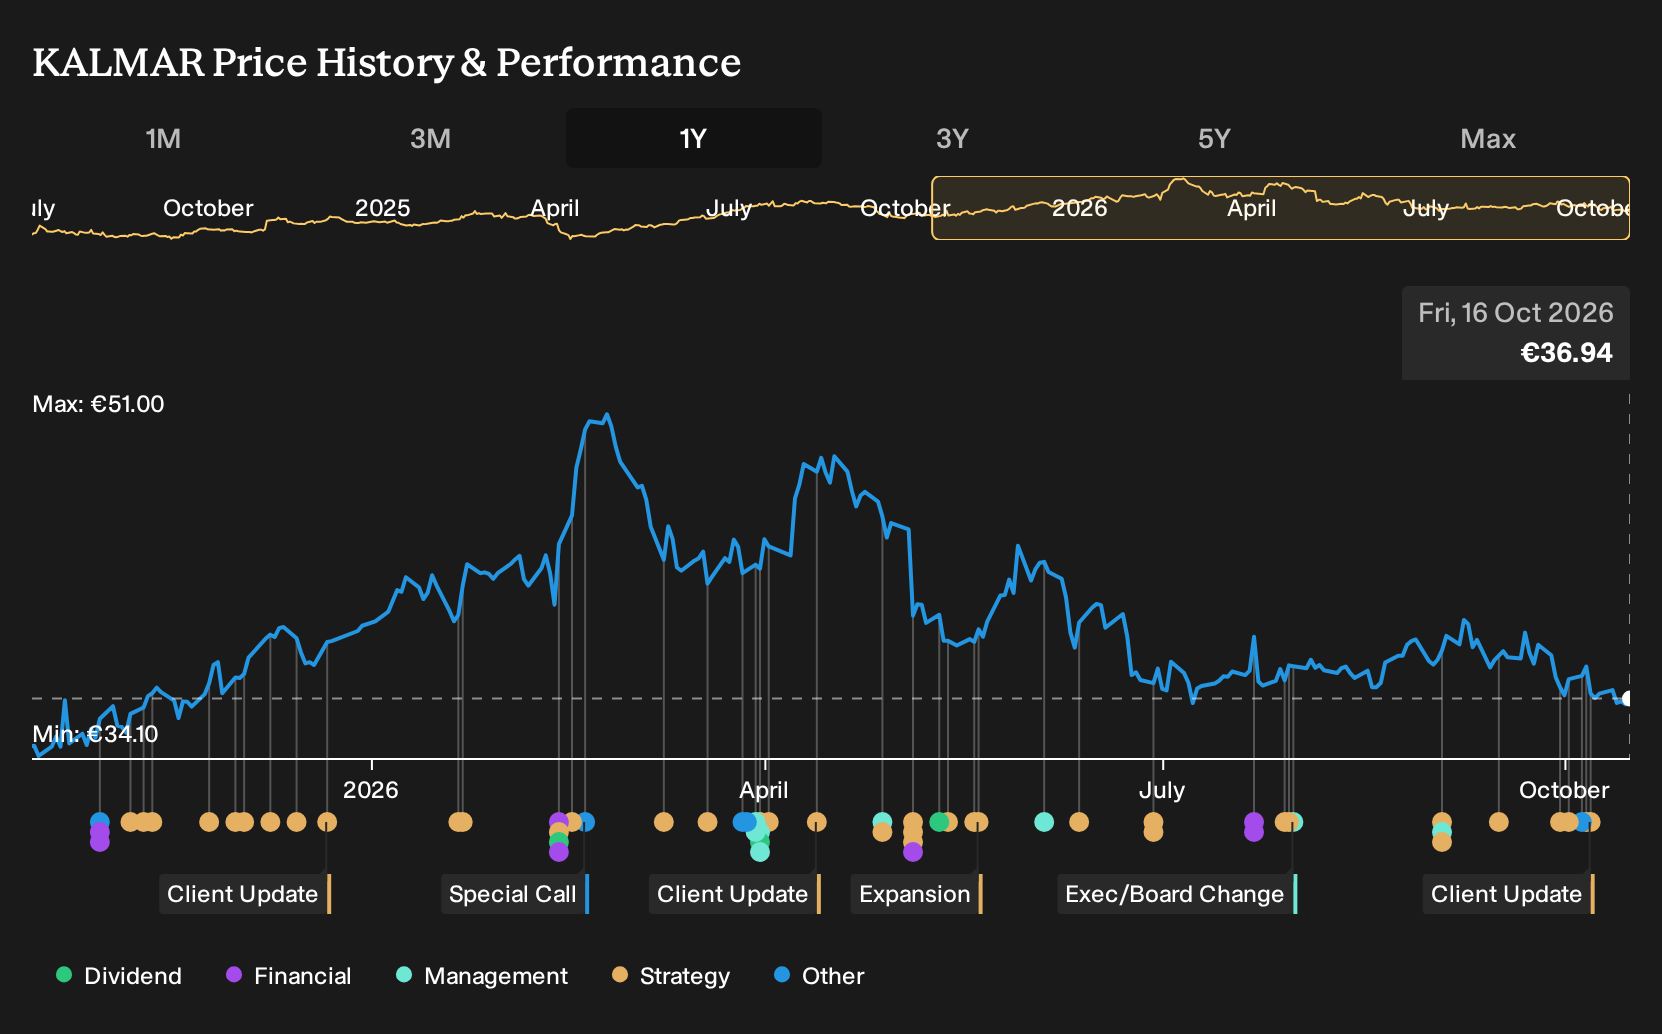
- Kalmar Oyj recently announced a 3 year Kalmar Complete Care service contract with Sweden’s Port of Halmstad, covering maintenance for a mixed cargo handling fleet and booked in the Third Quarter 2026 order intake.
- Alongside the port deal, Kalmar issued a targeted NHTSA recall for certain Ottawa T2 terminal tractors. The recall addresses a rare electrical insulation issue and aims to protect customer uptime and safety.
- We will look at how Kalmar Oyj's investment narrative around services and safety is affected by the Halmstad maintenance agreement.
Scan beyond Kalmar Oyj and see how other port and logistics specialists manage uptime, safety, and capital intensity with a curated set of 92 robotics and automation stocks that power modern cargo operations.
Kalmar Oyj Investment Narrative Recap
To own Kalmar Oyj, you need to believe that ports and heavy logistics customers will keep turning to long term service agreements, software, and eco equipment rather than treating purchases as one off capex. The Halmstad deal reinforces that services already matter here, with €618.6m of segment revenue and a growing attach rate around Kalmar’s installed base.
In the near term, the key swing factor is how efficiently Kalmar converts its €1,822.3m revenue and 9.5% net margin into steadier cash flow as U.S. demand stays uneven and competition in AMEA remains intense. The Ottawa T2 recall looks operationally contained, so the main risk still sits with order timing and pricing pressure rather than this specific event.
The Halmstad Kalmar Complete Care agreement is the clearest operational link to the current news flow. It extends a multi year service partnership at one of Sweden’s larger ports and aligns tightly with management’s push toward more recurring maintenance, lifecycle and digital services on top of the Equipment segment’s €1,202.9m revenue base.
For catalysts, contracts like this matter because they can support more predictable service income while Kalmar invests in automation, data platforms such as MyKalmar INSIGHT, and eco portfolio offerings. When set against risks such as slower U.S. decision making and price pressure from Asian rivals, consistent execution on these service frameworks will be important for earnings stability and cash conversion.
Kalmar Oyj's current analyst story points to revenues of €2.1 billion and earnings of €225.3 million by 2029. That path assumes 4.5% yearly revenue growth and an earnings increase of about €51.9 million from €173.4 million today.
Discover how Kalmar Oyj's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view says the real swing factor for Kalmar Oyj is not services growth at all but tariff exposure on Chinese components. The most cautious analysts already pencilled in slower 3.5% annual revenue growth to about €2.0b and a lower 13.0x P/E by 2029. After this Halmstad contract and the recall, those expectations may shift.
Explore 2 other Kalmar Oyj fair value estimates, including one that suggests it could be worth just €43.00.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kalmar Oyj research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Kalmar Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kalmar Oyj's overall financial health at a glance.
Looking for more investment ideas beyond Kalmar Oyj?
Once you are comfortable with where Kalmar Oyj fits in your portfolio, it can help to line it up against other opportunities that offer different mixes of quality, income, and risk. The Simply Wall St Screener is built for exactly that, letting you filter the market down to a small set of stocks that match the type of profile you care about most.
- If you want steadier balance sheets and fewer financial surprises, start by scanning a list of solid balance sheet and fundamentals (203 results) that can act as the anchor holdings in your portfolio.
- For those hunting for quality at a reasonable entry point, compare Kalmar Oyj with 194 high quality undervalued stocks that combine fundamental strength with a discount to their assessed worth.
- If your priority is keeping potential downside in check, narrow the field to 231 resilient stocks with low risk scores and see which businesses line up best with your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com