


Exploring Three Undiscovered Gems in Global Markets
In recent weeks, global markets have experienced significant volatility, driven by concerns over AI spending and inflation pressures, causing a rotation from large-cap growth stocks to more defensive segments. Amid this backdrop, small-cap stocks have been particularly impacted as the Russell 2000 Index fell by 3.05%, highlighting the challenges these companies face in uncertain economic climates. In such an environment, identifying undiscovered gems requires a focus on companies with strong fundamentals and potential for growth that are not yet fully recognized by the market.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| Bastide Le Confort Médical | 263.37% | 2.00% | -22.93% | ★★★☆☆☆ |
We're going to check out a few of the best picks from our screener tool.
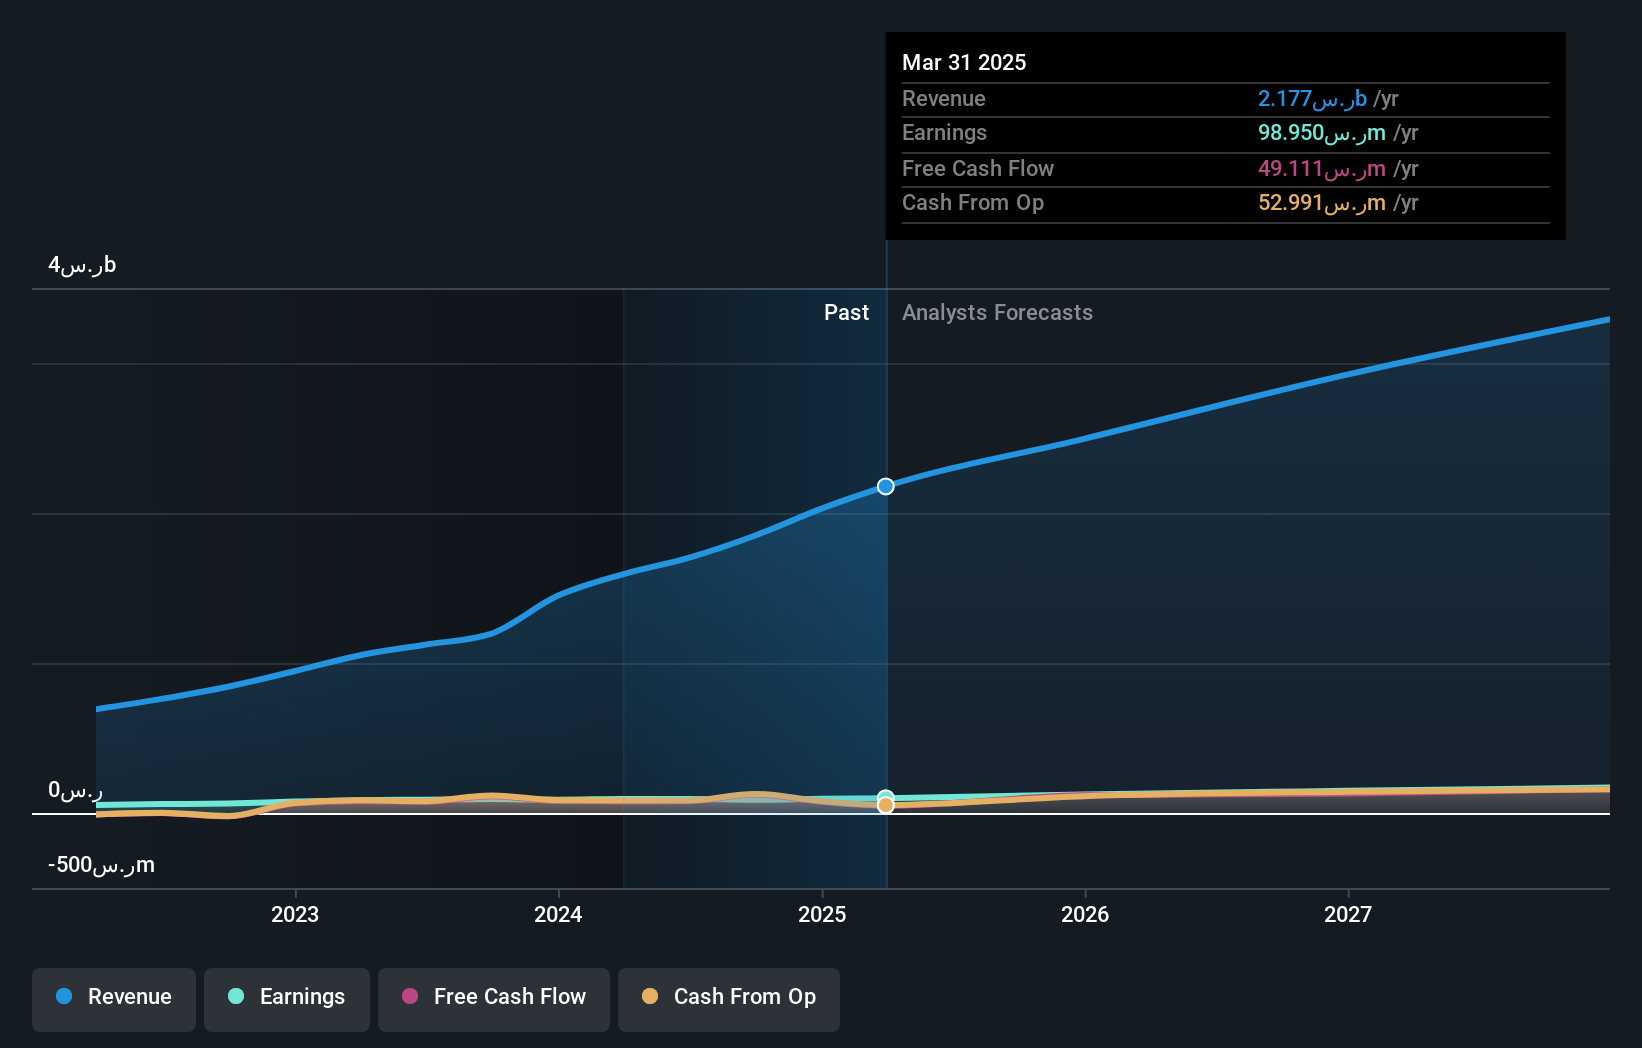
Almawarid Manpower (SASE:1833)
Simply Wall St Value Rating: ★★★★★★
Overview: Almawarid Manpower Company offers recruitment services for both domestic and expatriate labor, catering to domestic workers and temporary employment agencies in Saudi Arabia, with a market cap of SAR1.73 billion.
Operations: The company's revenue is primarily driven by its Corporate Segment, generating SAR2.40 billion, followed by the Individual and Hourly Segments at SAR328.44 million and SAR213.35 million respectively.
Almawarid Manpower, a nimble player in the manpower sector, has shown impressive financial health with no debt and a robust earnings growth of 65% over the past year, outpacing the industry average of 39.2%. Trading at an attractive valuation—71.1% below its estimated fair value—the company reported second-quarter sales of SAR 783 million and net income of SAR 50 million, marking significant improvements from last year. With basic earnings per share rising to SAR 2.5 from SAR 1.62 and dividends set at SAR 1.60 per share for the first half of 2026, Almawarid presents a compelling case for potential investors seeking value in smaller firms.
- Click here to discover the nuances of Almawarid Manpower with our detailed analytical health report.
CSC Financial (SEHK:6066)
Simply Wall St Value Rating: ★★★★☆☆
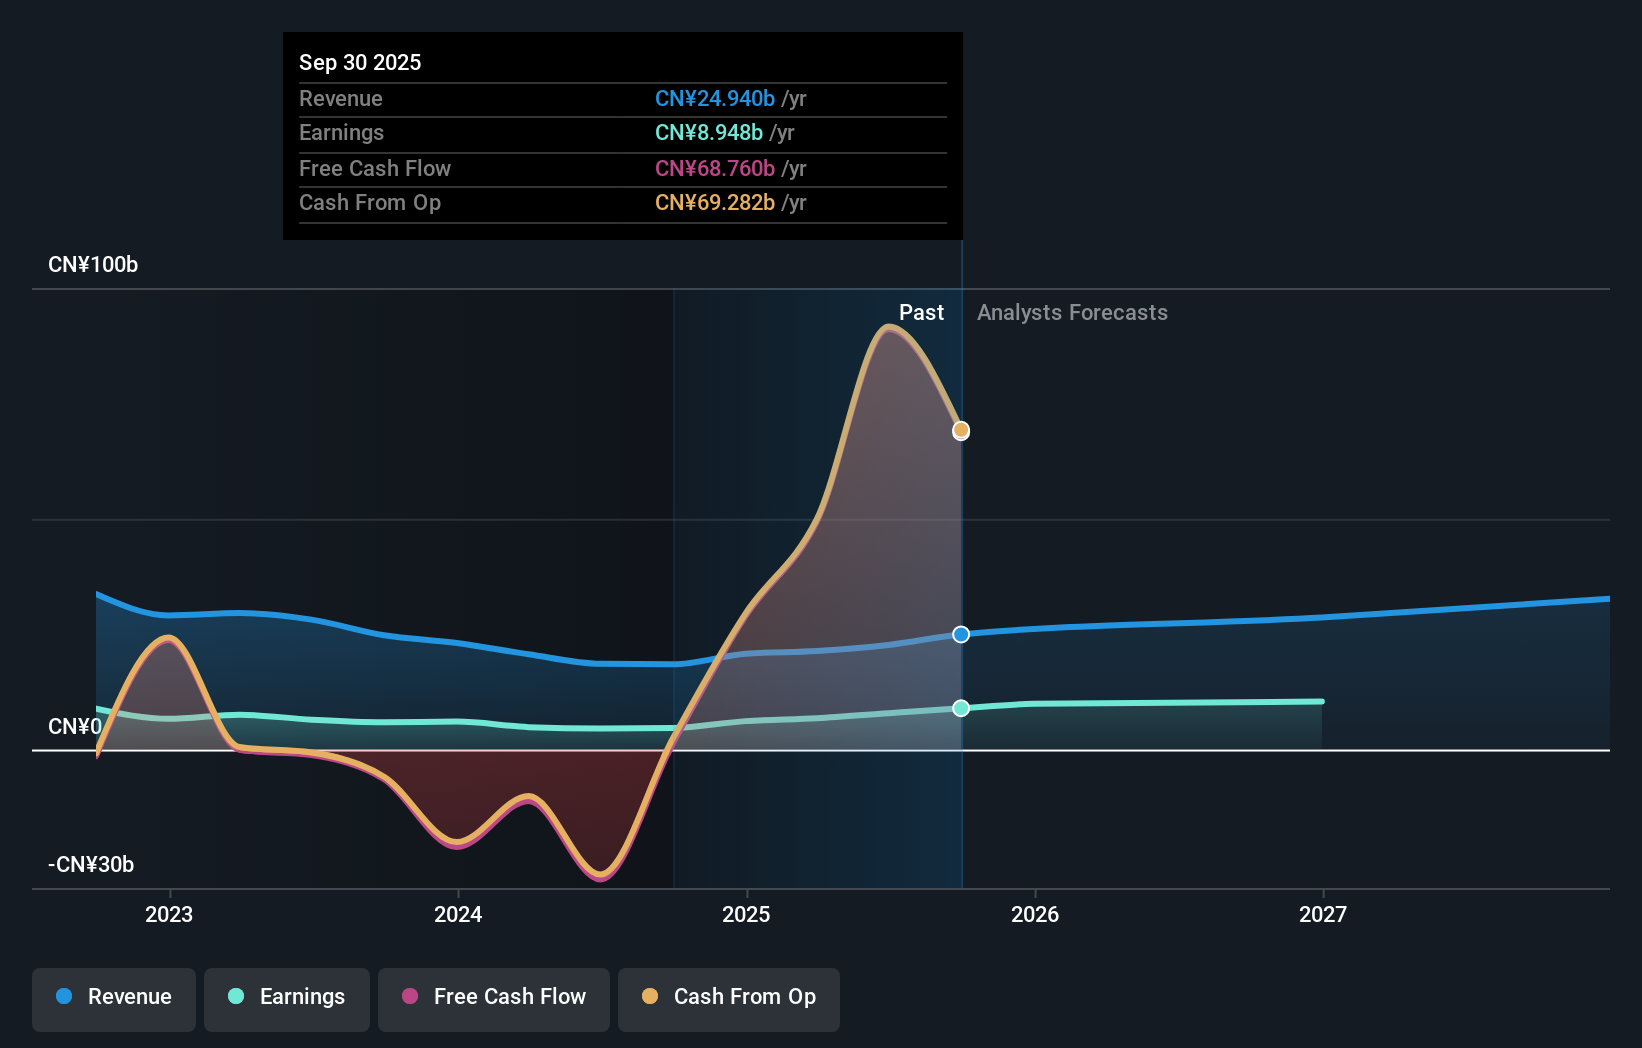
Overview: CSC Financial Co., Ltd. operates as an investment banking firm offering a range of financial services in Mainland China and internationally, with a market capitalization of approximately HK$188.36 billion.
Operations: CSC Financial generates revenue primarily from its Transaction and Institutional Customer Service segment (CN¥13.92 billion) and Wealth Management services (CN¥9.12 billion). The Investment Banking and Asset Management Business segments contribute CN¥3.12 billion and CN¥1.69 billion, respectively, to the company's total revenue streams.
CSC Financial seems to be a promising player in the financial sector, trading at 16.6% below its estimated fair value, indicating potential upside for investors. The company reported impressive revenue growth for the half year ended June 2026, reaching CNY 16.23 billion from CNY 10.74 billion last year, while net income rose to CNY 7.64 billion from CNY 4.51 billion previously. Despite its debt-to-equity ratio increasing over five years from 277% to 310%, CSC maintains more cash than total debt and boasts high-quality earnings with a positive free cash flow trajectory, suggesting robust financial health and operational efficiency moving forward.
Silvery Dragon Group Tianjin (SHSE:603969)
Simply Wall St Value Rating: ★★★★★☆
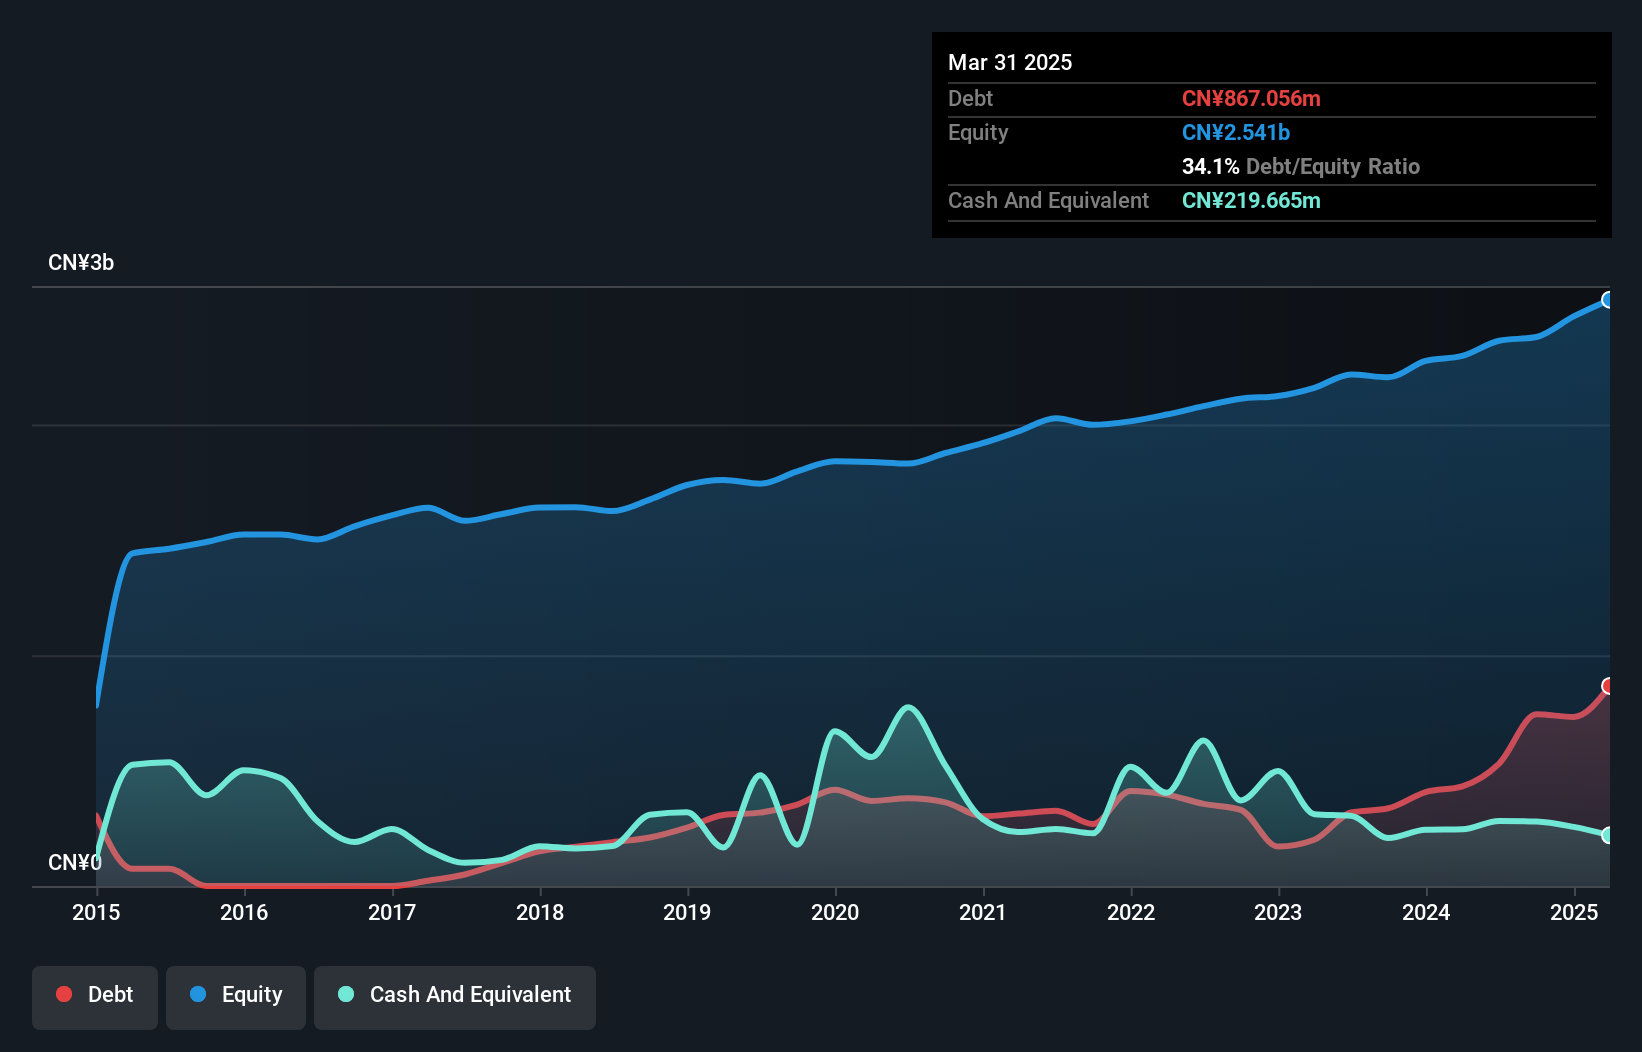
Overview: Silvery Dragon Group Co., Ltd. Tianjin, with a market cap of CN¥5.93 billion, is engaged in the research, development, manufacturing and sale of prestressed steel products both within China and internationally.
Operations: Silvery Dragon Group generates revenue primarily from the Metal Processors and Fabrication segment, amounting to CN¥3.32 billion. The company's financial performance is influenced by its gross profit margin, which has shown variability over recent periods.
Silvery Dragon Group Tianjin, a lesser-known player in the metals and mining industry, has shown robust performance with earnings growth of 41.2% over the past year, surpassing its industry peers' 23.3%. The company's net income for H1 2026 reached CNY 240.97 million, up from CNY 171.7 million in the previous year, reflecting solid operational efficiency. Trading at approximately 33.7% below its estimated fair value suggests potential for value investors seeking opportunities in this sector. With a satisfactory net debt to equity ratio of 15.4%, Silvery Dragon demonstrates financial prudence and resilience amid market fluctuations.
Taking Advantage
- Gain an insight into the universe of 179 Global Undiscovered Gems With Strong Fundamentals by clicking here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com