


ServiceNow (NOW) AI Push Puts Its Valuation Story Back In Focus
ServiceNow (NOW) just put AI governance and workplace automation at the center of its story, rolling out AI Passport for real time agent controls alongside new EmployeeWorks tools that let staff build job specific AI helpers.
ServiceNow’s share price has been volatile this year, with the stock down 3.72% year to date but logging a 35.60% 90 day share price return and a 4.80% 30 day gain that point to building momentum around its AI agent story.
Scan how ServiceNow’s AI push compares with other enterprise automation plays by reviewing the hand picked 55 AI infrastructure stocks at the intersection of software, data centers, and AI agents.
ServiceNow is fresh off a sharp AI driven rebound after a tougher 12 month stretch, which raises a simple fork in the road for investors. Lean into the current setup now or wait for a cheaper shot later as the valuation math unfolds next?
Most Popular Narrative: 45.5% Undervalued
ServiceNow’s most followed narrative pins fair value at $260.58 per share against a last close of $141.97, which implies a wide gap that this framework treats as a valuation opportunity rather than a rounding error.
The castle still stands. It may even be worth considerably more than the market price. But this time, we have counted both the gold in the vault and the mortgage on the quarry.
See why 95 investors see ServiceNow as 46% undervalued.
The author John_Eric builds this view around ServiceNow’s role as workflow infrastructure, not just another software license, and layers in the updated balance sheet to keep that thesis honest. In that narrative, the fair value estimate of $260.58 per share already reflects roughly $810 million of net debt, acquisition spend on security assets like Armis and Veza, and an explicit focus on cash generation rather than headline revenue alone.
ServiceNow’s current share price of $141.97 is also well below the Simply Wall St DCF estimate of $272.01, which reaches a similar conclusion through a different lens. The SWS DCF model projects future free cash flows from the existing business, then discounts those back using an 8.63% rate to reflect risk and the time value of money, producing a present value for the equity.
Taken together, the most popular narrative and the SWS DCF output both point to a material gap between current trading levels and the estimated worth of ServiceNow’s workflow and AI governance platform, while still recognizing real trade offs such as a value score of 2 and a P/E ratio above both software peers and the modelled fair P/E. The key question for readers is how much weight to put on that cash flow trajectory compared with the richer multiple and recent share price volatility.
Result: Fair Value of $260.58 (UNDERVALUED)
Still, two pressure points could upset the ServiceNow story: the sizeable acquisition-driven debt load and any slowdown in AI workflow adoption by large clients.
Find out about the key risks to this ServiceNow narrative.
Another View: Multiples Are Less Generous
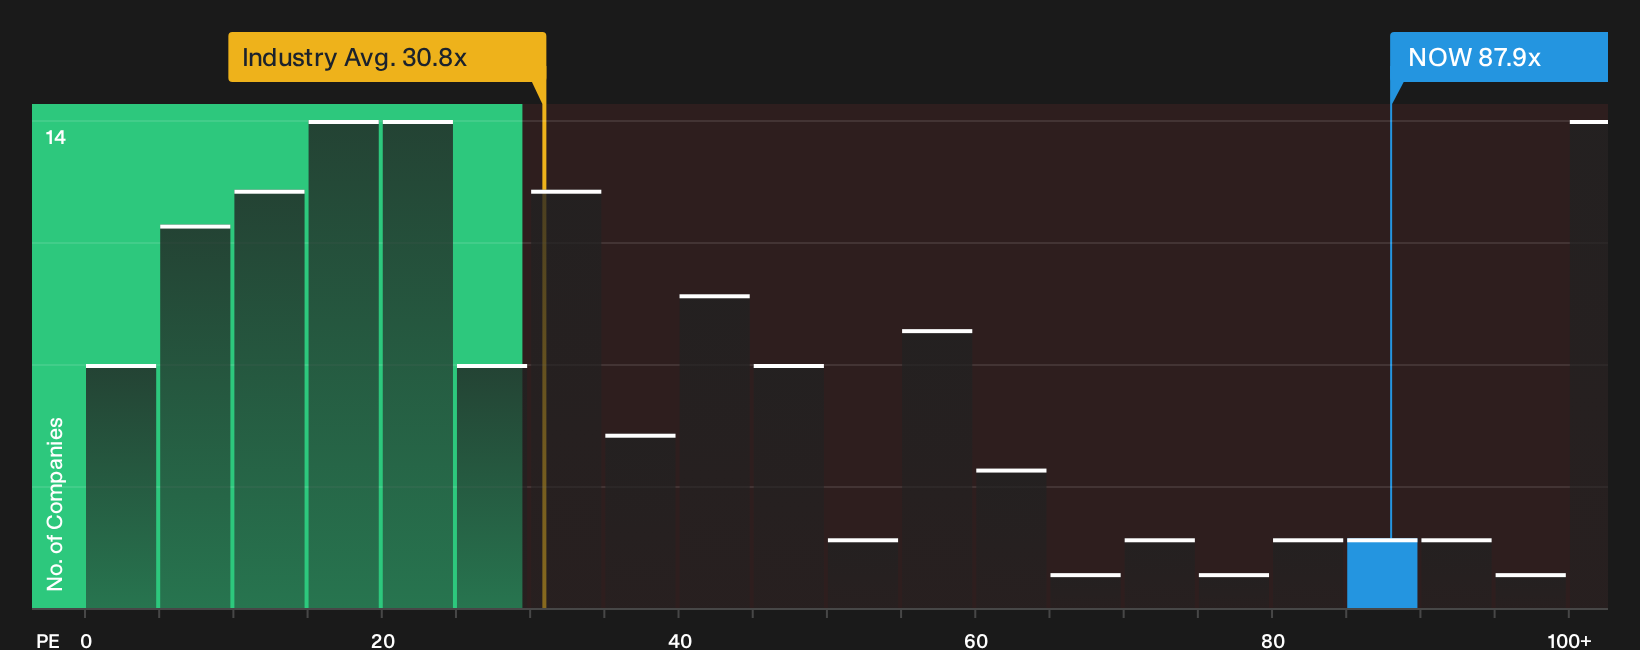
There is a catch to the bullish fair value case on ServiceNow. On earnings, the stock trades at a P/E of 87.9x, compared with 30.8x for the US software group and a fair ratio of 50.9x that regression work suggests the market could move toward over time.
If sentiment cools, a move closer to either the peer average or that 50.9x fair ratio would mean the price does more of the adjustment than earnings. How comfortable are you relying on cash flow models when the current multiple already assumes a premium story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the tension between optimism and caution around ServiceNow’s setup today is normal, so move fast on the homework and pressure test the 3 key rewards.
Looking for more investment ideas beyond ServiceNow?
If ServiceNow has your attention, do not stop there. Use the same discipline to scan other opportunities before this cycle moves on without you.
- Target resilient performers by reviewing the 32 resilient stocks with low risk scores that may help steady your portfolio when single names swing around.
- Spot potential mispricings early and work through the 20 high quality undiscovered gems before wider attention tightens the gap between perception and price.
- Strengthen your income plan by assessing the 8 dividend fortresses that combine higher yields with a focus on durability, not just headline payout rates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com