


Is RELX (LSE:REL) A Bargain On Positioning Ahead Of Its Trading Statement?
Investor attention around RELX (LSE:REL) has picked up as the group approaches its trading statement scheduled for Thursday 22 October, which has been flagged as potentially price sensitive for the information and analytics specialist.
Recent trading has been punchy. RELX’s 30 day share price return of 16.61% and 90 day share price gain of 15.73% contrast with a year to date share price decline of 2.31%. The 1 year total shareholder return is down 10.87%, while the 5 year total shareholder return is up 43.79%. This points to short term momentum building ahead of the trading statement against a mixed longer term picture.
Scan how other information and analytics peers are positioning for potential breakouts around earnings season with our hand picked 7 high quality undervalued stocks, together with RELX’s upcoming trading statement.
RELX now trades at a double digit discount to both analyst targets and intrinsic value estimates after a sharp short term rally. Is that underpricing genuine caution, or a misread of the risk in this information heavyweight?
Most Popular Narrative: 14% Undervalued
On the most followed view, RELX screens below an estimated fair value of £33.91 against the last close at £29.14. This puts the trading statement in the spotlight for how it might validate or challenge that gap.
RELX's continued rollout and integration of advanced AI-powered analytics and decision tools across its Risk, STM, and Legal segments is deepening customer value, increasing product adoption, and supporting higher-margin, recurring digital revenues. Management expects operating profit growth to outpace revenue growth, which is likely to drive further EPS and margin expansion.
See why 81 investors see RELX as 14% undervalued.
Result: Fair Value of £33.91 (UNDERVALUED)
Still, the bullish RELX story could be upset if open access policies chip away at STM subscriptions, or if cheaper AI tools squeeze pricing power in legal analytics.
Find out about the key risks to this RELX narrative.
Another View On RELX Valuation
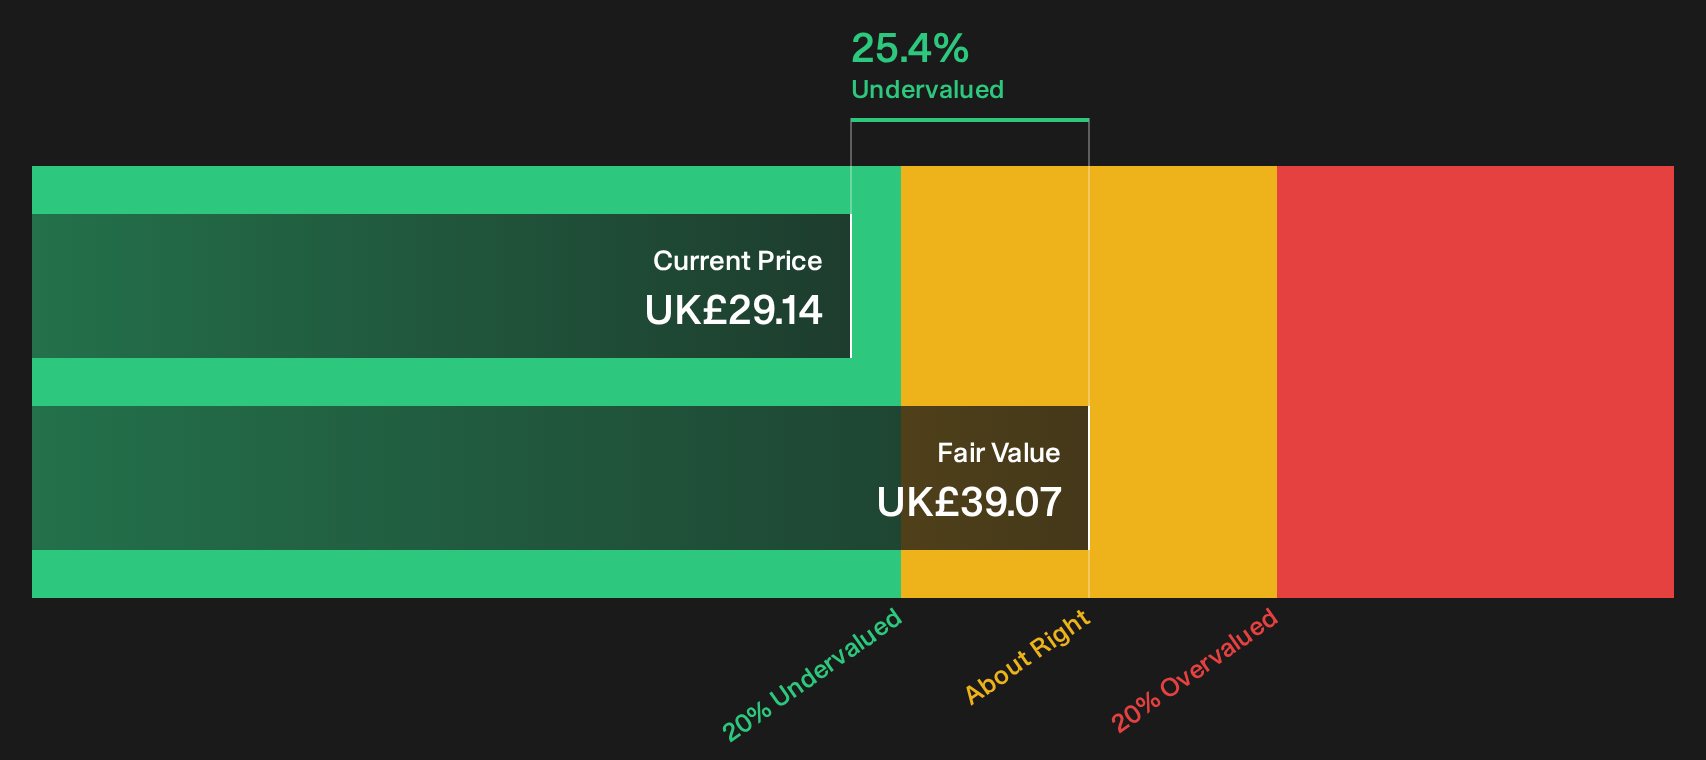
The earlier argument leans on analyst earnings forecasts and target prices to frame RELX as about 14% below a £33.91 fair value. Look at the SWS DCF model and you get a stronger message. On that approach, RELX at £29.14 sits 25.4% below an estimated £39.07 future cash flow value. That gap suggests more upside on paper, but also raises a simple question: which set of assumptions do you trust more when the trading statement lands?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around RELX is mixed enough that you should see the numbers for yourself and decide how much caution or optimism feels justified. To weigh both sides quickly, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond RELX?
RELX might be front of mind today, but you do not want your watchlist tied to a single story when there are other angles worth considering.
- Target potential value upside before it is crowded by scanning our hand picked 5 high quality undiscovered gems that pair strong fundamentals with low market attention.
- Build a portfolio that can handle stress by focusing on companies flagged in the 4 resilient stocks with low risk scores for resilient financial profiles and lower risk scores.
- Strengthen your core holdings with businesses highlighted in the list of solid balance sheet and fundamentals (9 results) so cash flow and balance sheet quality work in your favour, not against you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com