


Rubicon Research Heads 3 Indian Founder Led Growth Stocks
Energy prices are heating up again, with September inflation in the US pushed to 3.7% largely by jumps in gas and fuel oil. Rising input costs often reward businesses that can grow faster than their expenses and retain pricing power. High growth Indian companies where insiders hold meaningful stakes can sometimes fit that profile. This article highlights three such fast growing, owner backed stocks from our screener.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing, owner backed businesses where both analysts and management see room for progress. However, if you want the names that matter most, these 39 high growth high conviction stocks are the strongest companies we've found.
Rubicon Research (NSEI:RUBICON)
Rubicon Research is a specialty pharma player built around proprietary drug delivery platforms that support gastro retentive and sustained release medicines. This ties directly into this screener’s focus on high growth businesses where management is leaning into scalable, higher value products.
Rubicon Research generates its ₹19,358 million revenue primarily from pharmaceutical products and related services, underpinned by its RubiReten and RubiSRL drug delivery technologies across pain, cardiovascular, CNS and other specialty categories. The stock carries a market value of about ₹249.7 billion.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a track record of commercialising 88% of approved products, points to a deeper product basket that can support future revenue and earnings visibility."
What ultimately happens to margins and growth will hinge on how one quietly growing pressure inside Rubicon Research’s expansion plans plays out.
That pressure point is exactly what the full narrative for Rubicon Research unpacks, showing how Rubicon Research’s growth push could accelerate or stall as that constraint bites.

Privi Speciality Chemicals (BSE:530117)
Privi Speciality Chemicals manufactures and exports aroma and fragrance ingredients used in everyday home and personal care products, with its aroma and fragrance chemicals business directly linked to the “fast growing stocks with high insider ownership” theme. It reports about ₹26.7b from Speciality Oleo Chemicals and carries a market value near ₹130.7b.
Privi Speciality Chemicals matters for this screener because its fragrance ingredients feed straight into global demand for deodorants, detergents and shampoos, and management is actively building capacity to pursue that opportunity.
"Ongoing capacity expansion from roughly 48,000 tonnes to 54,000 tonnes, combined with continuous process intensification and debottlenecking, increases operating leverage as fixed costs are spread over higher output, which can allow earnings to grow faster than volumes."
What investors need to watch now is how a single assumption about future fragrance demand shapes pricing power and margin resilience.
That assumption is exactly what the full narrative for Privi Speciality Chemicals breaks down. It shows whether fragrance demand risk is masking pricing power or setting up an accelerating earnings story.

Bajel Projects (NSEI:BAJEL)
Bajel Projects runs high voltage power transmission and distribution EPC contracts, a direct fit with the screener’s focus on fast growing, execution heavy businesses. It generates about ₹27.5b from Power Transmission and Power Distribution and carries a market value near ₹19.4b.
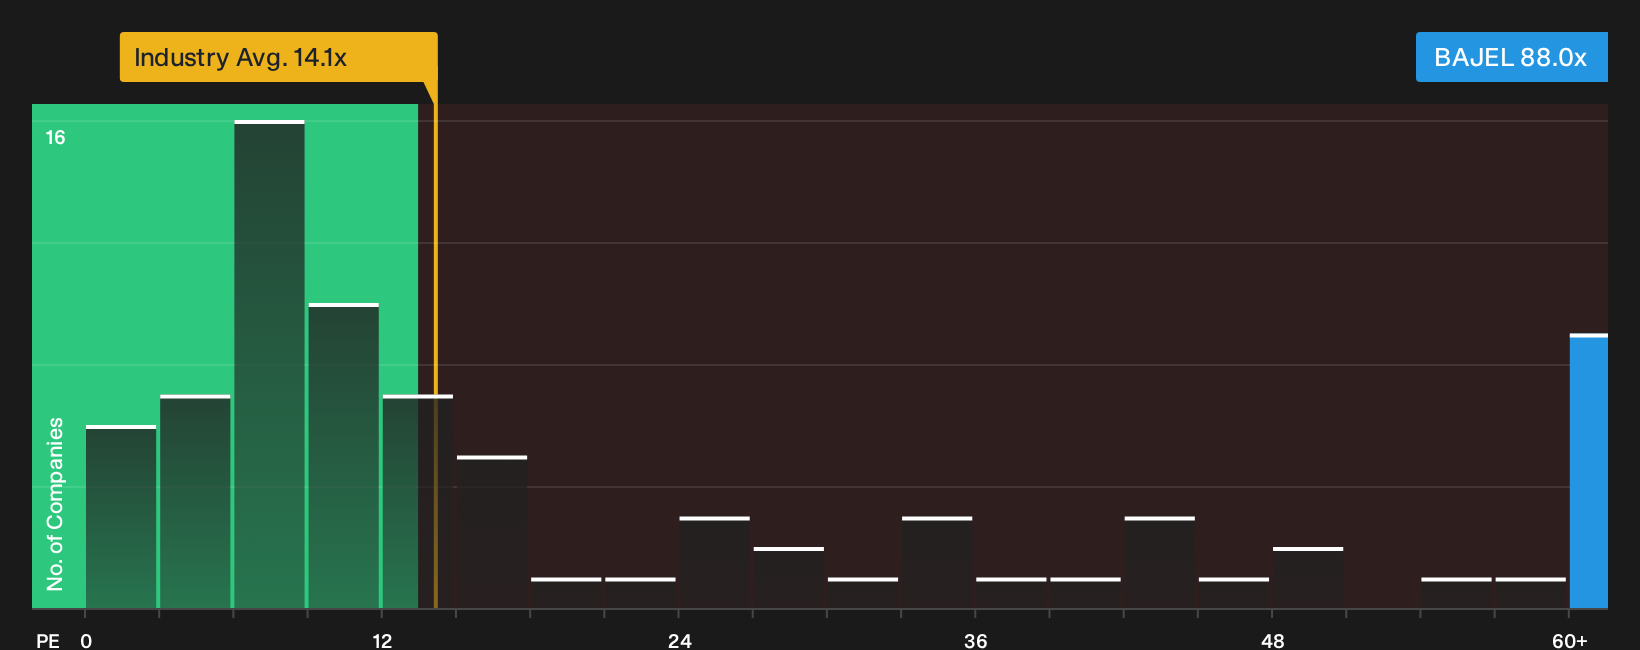
Bajel Projects combines forecast earnings growth of about 57.7% a year with large ticket EHV orders from PowerGrid and Tata Power that can fuel rapid expansion. The stock trades on a rich 88x P/E and very slim 0.8% margins, so a lot rests on how one pressure inside those big EPC contracts plays out.
That pressure makes it worth studying the 2 key rewards and 1 important warning sign to see how Bajel Projects’ rich P/E could either compress, or be overtaken by execution.
Seeking Fresh Alternatives Beyond These Picks
Fresh ideas move first. Breakout moves, early momentum, and quiet winners often get caught by screeners before headlines. Scan what is flying under the radar for now and act now.
- Spot cash rich outliers before they rerate by scanning the 189 high quality undervalued stocks curated for robust cash flows and sturdy balance sheets.
- Ride structural electricity demand trends by zeroing in on curated 42 power grid technology and infrastructure stocks geared to grid upgrades, transmission tech, and long term infrastructure spends.
- Target disciplined AI operators by focusing on 39 profitable AI stocks that aren't just burning cash picked for real earnings, not just hype fueled cash burn.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com