


Mondelez International (MDLZ) Could Be 8% Undervalued Following New Restaurant Brand Tie Ups
Mondelez International (MDLZ) is in focus after new limited-time collaborations put its snack brands into restaurant chains, from Wingstop’s SOUR PATCH KIDS Wicked Punch wings to Portillo’s OREO shakes and desserts this Halloween season.
The recent restaurant tie ups arrive at a time when Mondelez International’s share price has climbed 19.12% year to date and the latest close sits at US$63.91. The 1 year total shareholder return of 5.96% points to steadier progress over a longer stretch.
Scan how Mondelez International’s branded tie ups compare with other consumer companies using our hand picked list of 20 high quality undiscovered gems for ideas that may still be off most radars.
After a 19.12% year to date climb, Mondelez International now asks a simple question of investors: Does the current price still reflect a fair trade off between its branded power and the risks you are taking on?
Most Popular Narrative: 8% Undervalued
On Simply Wall St’s most followed view, Mondelez International screens as undervalued, with a fair value of $69.13 compared with the latest close at $63.91. That gap rests on a story that links cocoa costs, brand spending and supply chain upgrades to stronger earnings power over time.
The company is continuing to reinvest upside into brands, emerging markets and distribution, with raised 2026 organic net revenue guidance to at least 2% and maintained EPS guidance alongside double digit advertising and consumer spending. This points to an ongoing effort to build future revenue and earnings rather than maximize short term profit.
See why 99 investors see Mondelez International as 8% undervalued.
Result: Fair Value of $69.13 (UNDERVALUED)
Still, this bullish Mondelez International story can unravel if cocoa markets tighten again or if North American shoppers pull back and pressure margins.
Find out about the key risks to this Mondelez International narrative.
Another View: Mondelez International Through The P/E Lens
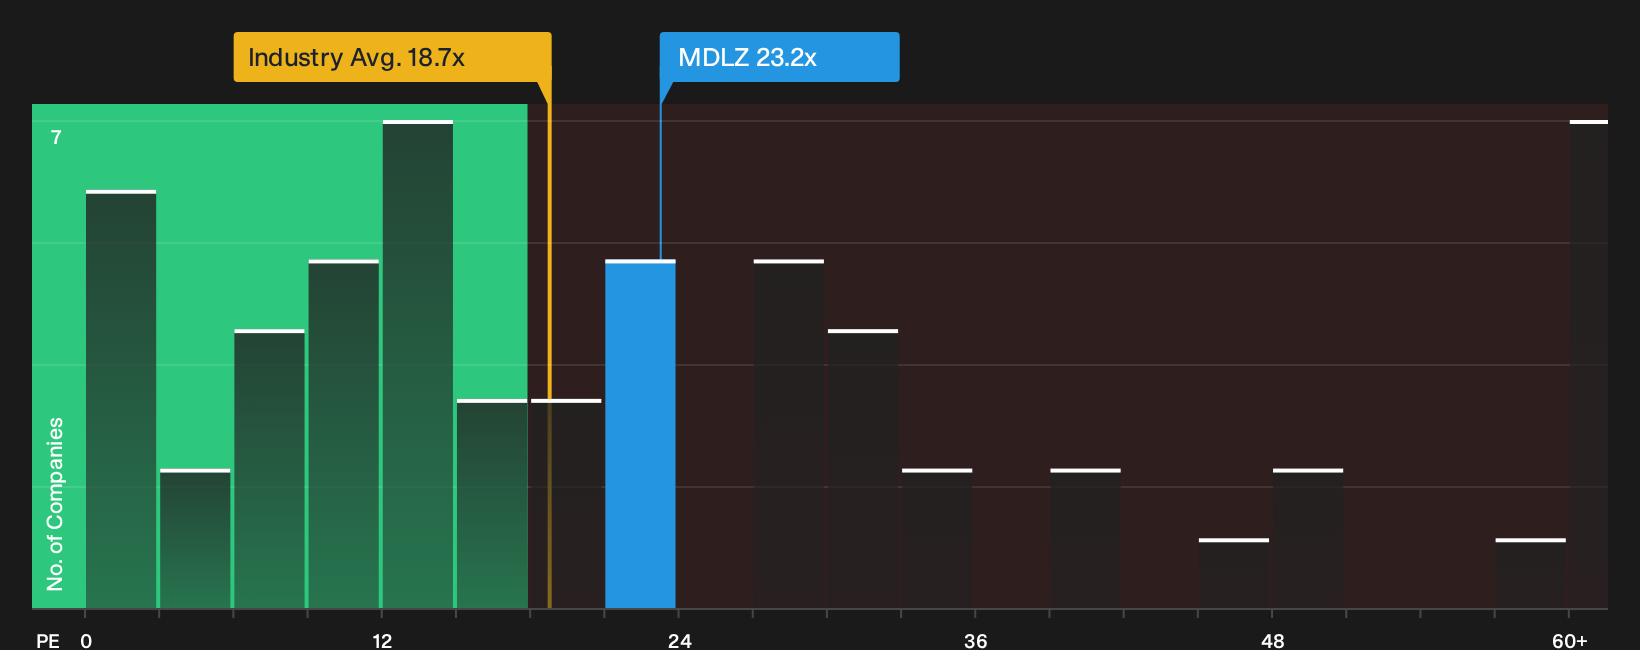
The first story presents Mondelez International as undervalued on a fair value of $69.13 versus a $63.91 share price. The P/E picture is less forgiving. MDLZ trades on 23.2x earnings, above a 21.4x fair ratio and the US Food sector on 18.7x, although still below peer averages at 32.1x. That mix of a premium to the sector but a discount to peers raises a simple question for you: Is MDLZ priced for comfort or for upside risk?
For a closer look at how these earnings multiples compare with fundamentals and peers, including the fair ratio context, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split sentiment around Mondelez International gives you mixed feelings, use that as a prompt to move fast and test the numbers yourself. You can review the full balance of potential upside and the single flagged risk by checking 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mondelez International?
Do not stop with one ticker. Use the same disciplined approach that helped you assess Mondelez International to scan wider opportunities before the crowd catches on.
- Target potential mispricing by reviewing companies that screen as high quality yet out of favor through our 33 high quality undervalued stocks.
- Strengthen your income stream by examining businesses that feature in the 8 dividend fortresses and already offer elevated yields.
- Reduce portfolio stress by focusing on financially sturdy candidates surfaced in the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com