


FactSet Research Systems (FDS) Expands Wealth Management Ties As Valuation Debate Heats Up
FactSet Research Systems (FDS) just widened its reach with Scotia Wealth Management and SUBSCRIBE, extending its research platform deeper into advisor desktops while adding digital tools for alternative investment onboarding and reporting.
These partnerships land at a time when FactSet Research Systems shares have been gaining traction, with a 7 day share price return of 5.05% and a 90 day share price return of 17.94%. However, the 3 year total shareholder return remains down 27.24%, highlighting that recent momentum has picked up after a weaker multi year stretch.
Scan how FactSet Research Systems stacks up against other information and analytics players by checking out a curated list of 20 high quality undiscovered gems in similar data driven businesses.
FactSet Research Systems now appears to be caught between stronger client relationships and a share price that has sprinted ahead in recent weeks. How much of that move reflects business progress rather than a mood shift in the market?
Most Popular Narrative: 16.6% Overvalued
FactSet Research Systems last closed at $301.67, while the most followed narrative pegs fair value at $258.69. That gap sits at about a 16.6% premium to the narrative estimate and sets the stage for a closer look at what is driving such a firm view.
Josh Warren made one declarative statement this morning that has no equivalent in any prior period: “We believe that FY 2026 operating margins represented a floor.”
Not a trend. Not a range. A floor.
See why 1 investors see FactSet Research Systems as 17% overvalued.
Result: Fair Value of $258.69 (OVERVALUED)
Still, FactSet Research Systems faces narrative risk if consumption based pricing makes ASV a weaker signal for future revenue, or if key AI partnerships remain quiet on delivery and impact.
Find out about the key risks to this FactSet Research Systems narrative.
Another View: Cash Flows Tell a Different Story
The headline narrative says FactSet Research Systems looks 16.6% overvalued at $301.67 against a $258.69 fair value. A different lens tells a very different story. The Simply Wall St DCF model puts fair value at $438.23, which implies the current share price trades at a large discount instead of a premium.
That gap between earnings-based narratives and cash-flow estimates can cut both ways. It can signal a mispriced opportunity, or it can highlight how sensitive long-horizon models are to small changes in assumptions. Which version of FactSet Research Systems do you think the market is really pricing in right now?
Look into how the SWS DCF model arrives at its fair value.
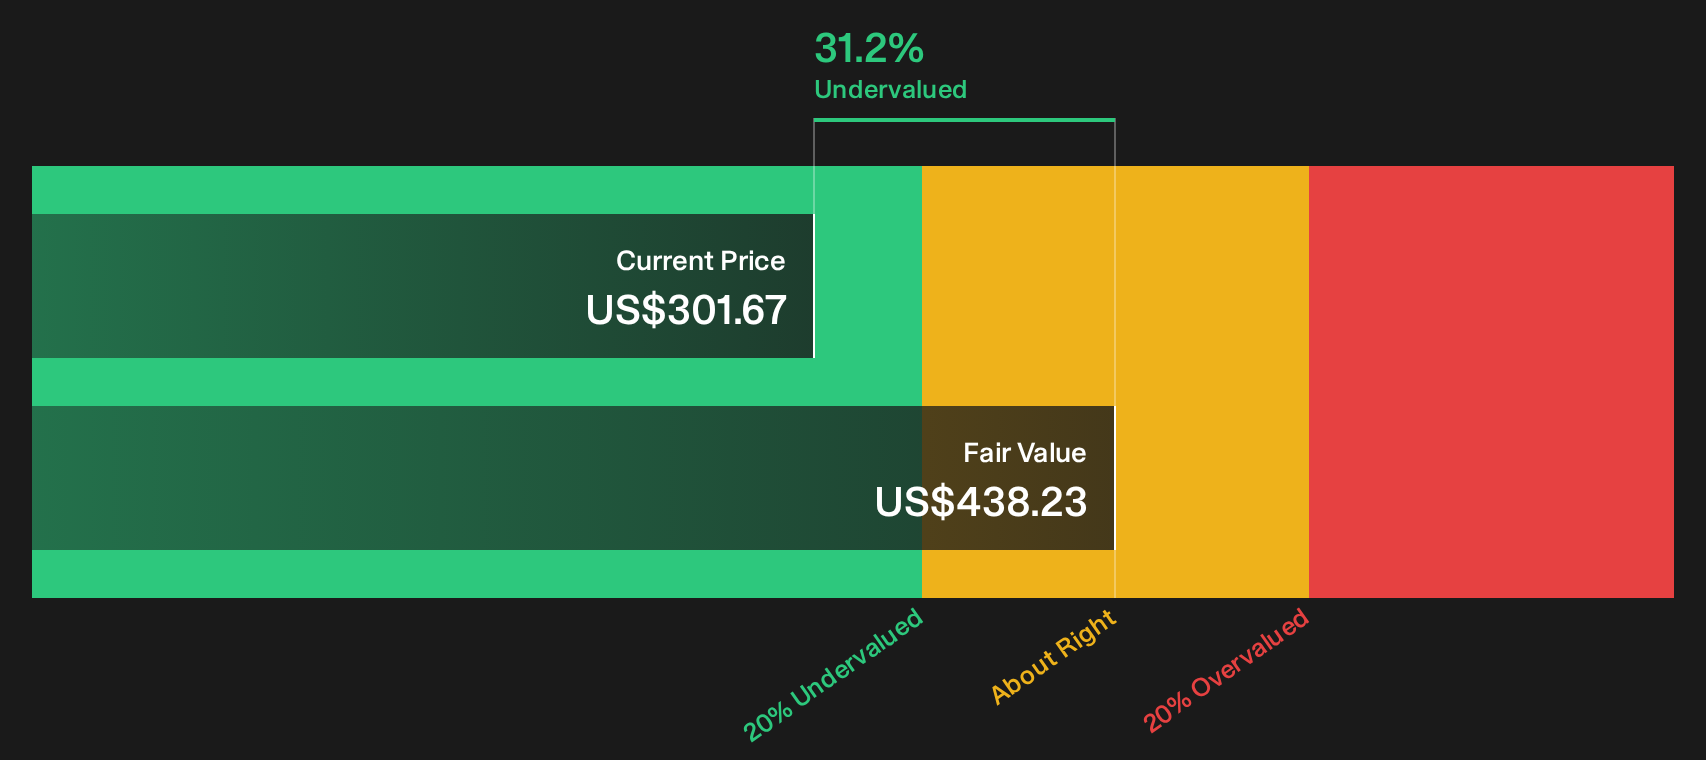
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FactSet Research Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Momentum cuts both ways for FactSet Research Systems, so if you care about the full picture, move quickly and weigh the data for yourself. To balance sentiment with specifics, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond FactSet Research Systems?
FactSet Research Systems gives you plenty to think about, but your portfolio may benefit from more than one story. Broaden your watchlist now to stay prepared for potential opportunities.
- Target income resilience by scanning for companies built around dependable payouts using the 8 dividend fortresses.
- Focus on potential value opportunities by reviewing a curated set of 33 high quality undervalued stocks.
- Aim to reduce unpleasant surprises by focusing on businesses with sturdier finances through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com