


Canadian Insider Owned Growth Stocks To Watch In October 2026
Energy driven inflation in the US recently reached a 3.7% annual rate, reminding investors how quickly costs can jump when fuel prices bite. Rising prices often reward businesses that can grow fast enough to keep their pricing power. That is where Canadian fast growers with sizeable insider holdings come in. This article walks through three such stocks, and why management ownership may matter for long term investors.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders have substantial skin in the game. However, if you want the strongest names, these 11 high growth high conviction stocks are at the top of the list.
Tenaz Energy (TSX:TNZ)
Tenaz Energy is a Calgary based oil and gas producer that leans heavily on its Dutch North Sea natural gas project, aligning directly with the screener’s focus on fast growth supported by committed management and optimistic analyst expectations.
Tenaz Energy generates about CA$497 million from producing and selling petroleum and natural gas, with most activity tied to its North Sea and Alberta assets, and carries a market value of roughly CA$2.34 billion.
"The build out of high quality Netherlands gas production, supported by multiple rigs across TEN operated, ONE Dyas operated and ENI operated wells, increases exposure to European gas pricing and can support higher revenue as more volumes move into the sales mix."
What matters now is how one subtle shift in the economic balance of that project filters through to cash flows and shareholder returns.
To see how that shift could either accelerate or stall value creation, read the full narrative for Tenaz Energy, which unpacks insider alignment, capital allocation and project risk in full.

Ivanhoe Mines (TSX:IVN)
Ivanhoe Mines taps directly into the fast growing, insider aligned story through its tier one African mining projects, with the Kamoa-Kakula complex central to its copper expansion while Kipushi Properties contributed about US$575 million and the group carries a market value near CA$14.7b.
For investors looking at fast growing resource plays backed by confident management, Ivanhoe Mines offers a clear example of how a single flagship asset can reshape a portfolio’s exposure to copper and critical metals.
"Kamoa-Kakula: 388,838 to 388,841 t copper in concentrate (100% basis; Ivanhoe attributable ~154 kt) despite Q2 seismic/flooding hiccup at Kakula East (temporary 6-month disruption in 30+ year LOM)."
What happens to Ivanhoe’s growth story depends on how one unseen pressure on long term project economics and capital efficiency ultimately plays out.
That unseen pressure is exactly what the full narrative for Ivanhoe Mines unpacks in detail, showing where Ivanhoe Mines could be accelerating, stalling, or quietly masking upside.

Cascades (TSX:CAS)
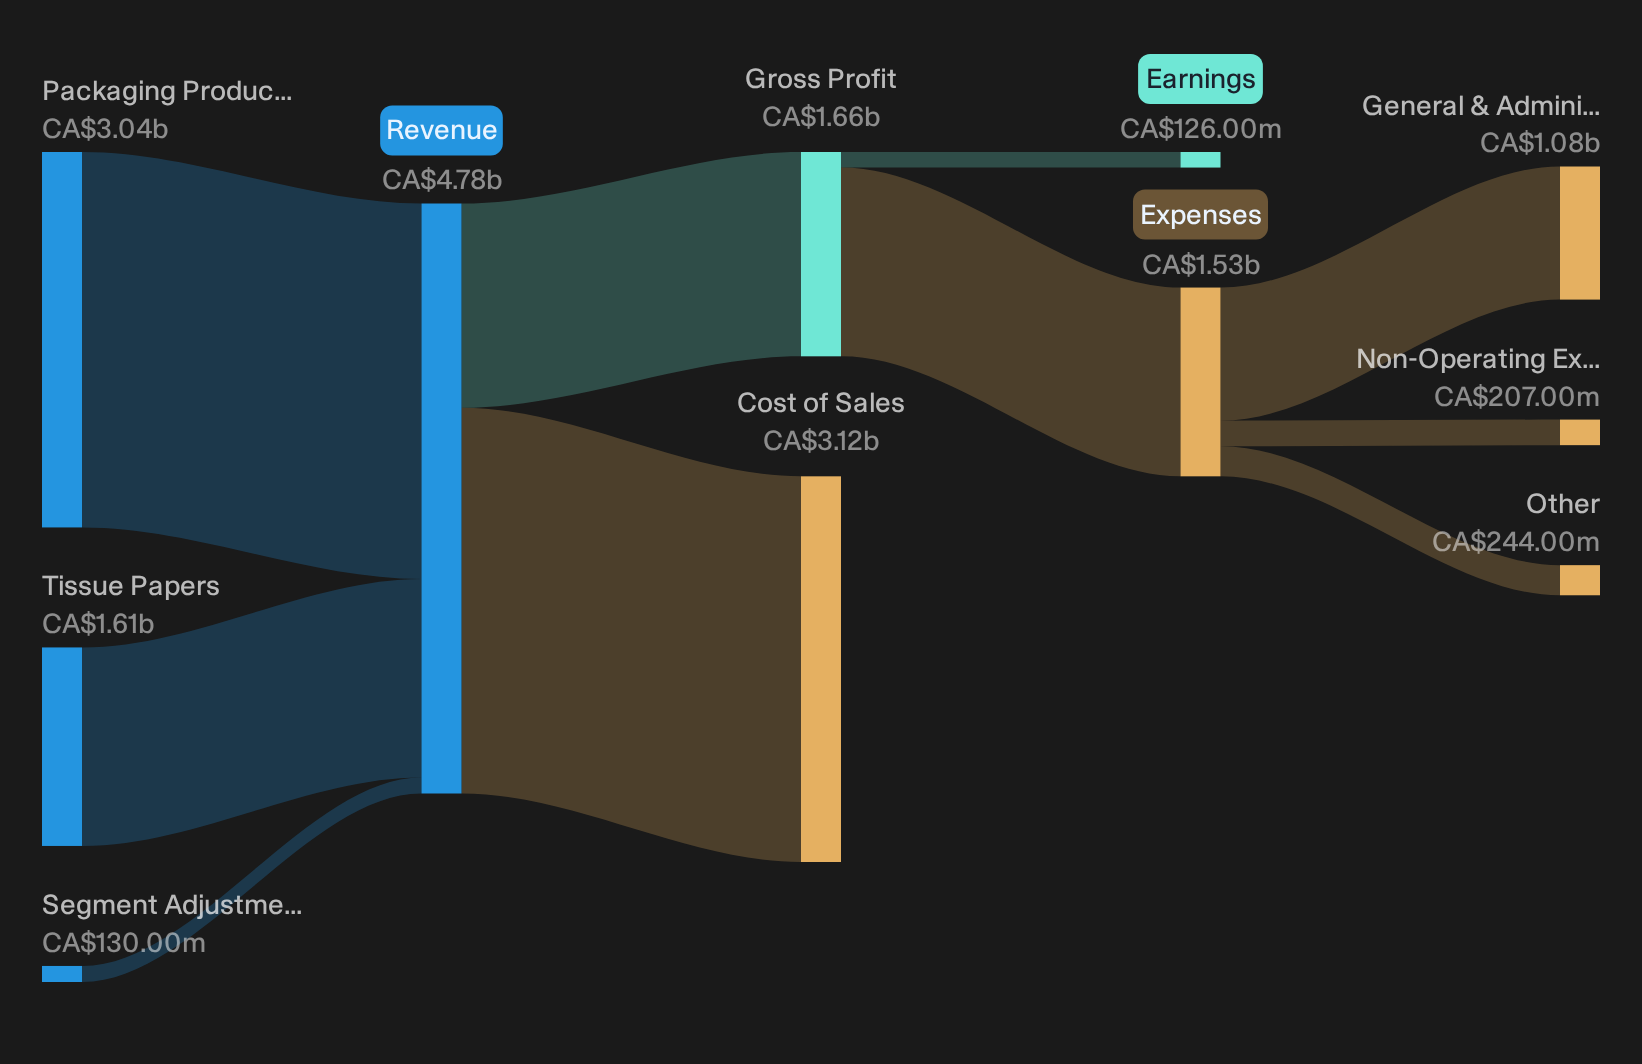
Cascades is a CA$1.8b packaging and tissue group whose growth story leans on its e-commerce and protective packaging lines. Packaging Products generates about CA$3.0b and Tissue Papers about CA$1.6b in revenue.
Cascades gives you direct exposure to packaging tied to online retail and logistics, while its tissue and recycling operations keep the overall business grounded in everyday demand.
"Continued ramp up at the Bear Island mill toward Greenpac level efficiencies, combined with targeted reductions in chemical and material usage, should lift Packaging segment productivity and support structurally higher EBITDA margins."
What investors really need to watch is how one quiet shift in the balance between pricing power and input costs feeds through those margins.
That margin shift is exactly what the full narrative for Cascades breaks down, showing where Cascades might be quietly accelerating, masking risks, or setting up for sturdier cash flows.
Seeking Alternatives Before The Crowd
Fresh ideas move first. The quickest breakouts and the early momentum often come from stocks still under the radar for now, so do not delay and get in early.
- Target resilient compounding potential by scanning 8 resilient stocks with low risk scores that aim to keep portfolio swings contained while the market chases more volatile stories.
- Ride the next infrastructure wave by using 42 power grid technology and infrastructure stocks curated for companies plugged into grid upgrades as electrification demand keeps building.
- Position for structural metal demand with 17 top copper producer stocks focused on producers tied to long term electrification and data center build outs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com