


Following Mixed September Sales, Is Yuexiu Property (SEHK:123) Still Below Fair Value?
Yuexiu Property (SEHK:123) has drawn fresh attention after releasing unaudited contracted sales for September 2026, which show a slightly higher monthly sales value but a sharply smaller sales area compared with a year earlier.
Recent trading tells a cautious story. Yuexiu Property’s share price has slipped over 2026, with the year-to-date share price return down 19.65% and the 1-year total shareholder return falling 31.38%, while the fresh sales update has arrived against that weaker backdrop.
Compare Yuexiu Property’s mixed sales update with other real estate developers that screen well on cash flow and balance sheet strength by scanning our hand-picked list of solid balance sheet and fundamentals (203 results) today.
Yuexiu Property now trades at a steep discount to both intrinsic value estimates and analyst targets after that weak share price run. Is the market correctly pricing in the risks, or leaning too far into caution?
Preferred price-to-sales of 0.1x for Yuexiu Property: Is it justified?
On raw pricing, Yuexiu Property looks cheap. The shares trade at a P/S of 0.1x while the stock is trading at HK$3.23 and screens as good value against both peers and the wider Hong Kong real estate sector.
The P/S ratio compares a company’s market value with its revenue. For a developer like Yuexiu Property, where earnings are currently negative and can swing with project timing, investors often fall back on sales as a cleaner yardstick for how the market is valuing the underlying pipeline.
That yardstick points to a steep discount. Yuexiu Property’s P/S of 0.1x is described as good value relative to peers on 0.2x, and even more so versus the Hong Kong real estate industry average of 0.7x. It is also flagged as below an estimated fair P/S of 0.4x that regression analysis suggests the market could move toward if sentiment or fundamentals change.
Explore the SWS fair ratio for Yuexiu Property.
Result: Price-to-sales of 0.1x (UNDERVALUED)
Still, recurring net income losses and a multi year total return decline could keep pressure on Yuexiu Property if investor sentiment weakens again.
Find out about the key risks to this Yuexiu Property narrative.
Another view on Yuexiu Property’s value
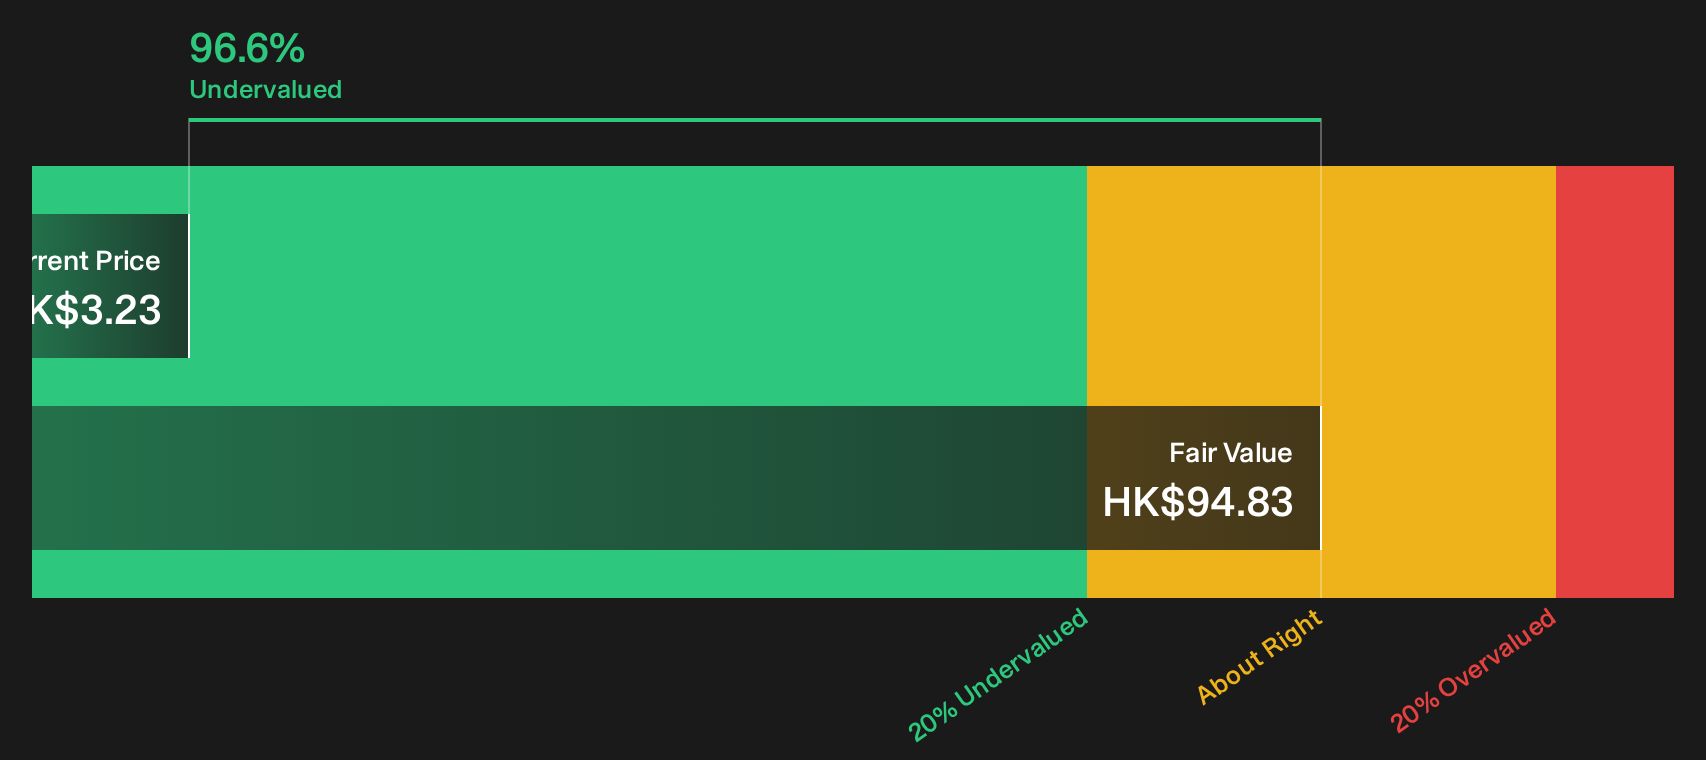
The SWS DCF model presents an even more extreme picture. At HK$3.23 per share, Yuexiu Property is priced roughly 96.6% below an estimated future cash flow value of HK$94.83, which suggests very little confidence in long term cash generation. Is that excessive pessimism or a fair warning sign?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yuexiu Property for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Yuexiu Property is clearly split, with discounted valuation on one side and fragile recent returns on the other. Put the data in context quickly and build your own stance with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Yuexiu Property?
Do not stop your research with Yuexiu Property. Broaden your watchlist using focused screeners that surface companies with very different strengths and risk profiles.
- Target stability first and stack your watchlist with companies that screen as 232 resilient stocks with low risk scores before market sentiment shifts again.
- Hunt for quality at a discount by scanning our 189 high quality undervalued stocks that combine solid fundamentals with attractive pricing.
- Strengthen potential income streams by reviewing 215 dividend fortresses that aim to pair higher yields with resilient business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com