


ArcBest (ARCB) Stock Looks Pricey On Its 78% One Year Run
ArcBest has delivered a powerful run over the past year, and the share price now invites a closer look at what investors are paying for each dollar of the freight operator's sales. With the stock drawing attention, the open question is how well those revenues line up with the current valuation.
- Over the past 12 months the stock has returned 77.9%, which puts real weight on the question of whether the current price is still grounded in its sales base.
- The business depends heavily on how efficiently it turns freight demand into revenue, so trends in pricing, volumes and operating discipline can all shape how much investors are prepared to pay for each dollar of sales.
- The analysts covering ArcBest have run their own numbers. See what analysts think ArcBest's shares could be worth.
The issue now is whether ArcBest's current share price is adequately supported by its sales when viewed through this lens.
For a broader starting list while you weigh ArcBest at its current P/S, it can help to run a quick screen of 33 high quality undervalued stocks as a comparison set.
Has ArcBest Run Too Far on Sales?
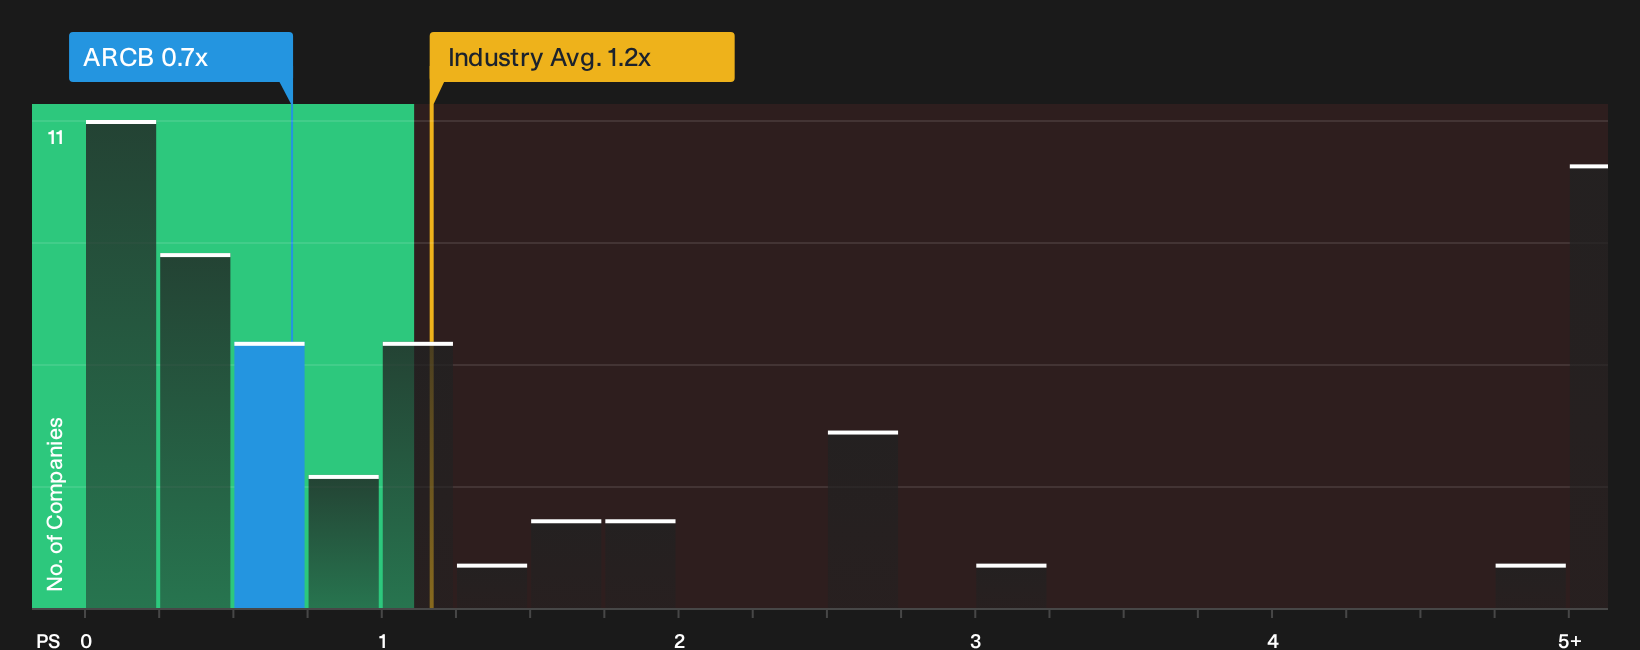
P/S fits ArcBest because freight carriers are often judged on how much investors are willing to pay for each dollar of revenue. On that score, the stock trades on a P/S of about 0.7x, compared with a Transportation industry average near 1.2x and a peer group closer to 0.9x. That puts the shares at a noticeable discount to both the broader sector and more direct competitors on this sales-based yardstick.
The fair-value model, which blends ArcBest’s growth profile, profitability, size and risks into a tailored P/S benchmark, suggests the current multiple is above the level implied by those fundamentals, so the stock screens overvalued on this framework even though it looks cheap against the raw industry numbers. For you as a shareholder or prospective buyer, the key question is whether ArcBest’s revenue quality and execution justify paying more than that modelled P/S while still paying less than many peers. Explore the numbers behind ArcBest's P/S valuation.
The ArcBest Narrative: What Would Justify Today's Price?
ArcBest’s valuation puzzle only really comes into focus once you spell out the paths the business could follow. Simply Wall St Narratives on the Community page map those possible futures by linking ArcBest's potential growth, margins and earnings paths to different outcomes for the share price. Each storyline ties a fair value to a specific mix of catalysts and risks so you can track which version appears to be unfolding over time.
One of the top community narratives on ArcBest: 30% undervalued
"The current valuation implies the share price does not fully recognise ArcBest’s structural cost efficiency program, AI-driven savings and expanding Managed Solutions contribution..."
Discover why this Narrative puts ArcBest at 30% undervalued.
One more ArcBest check that belongs next to the price tag
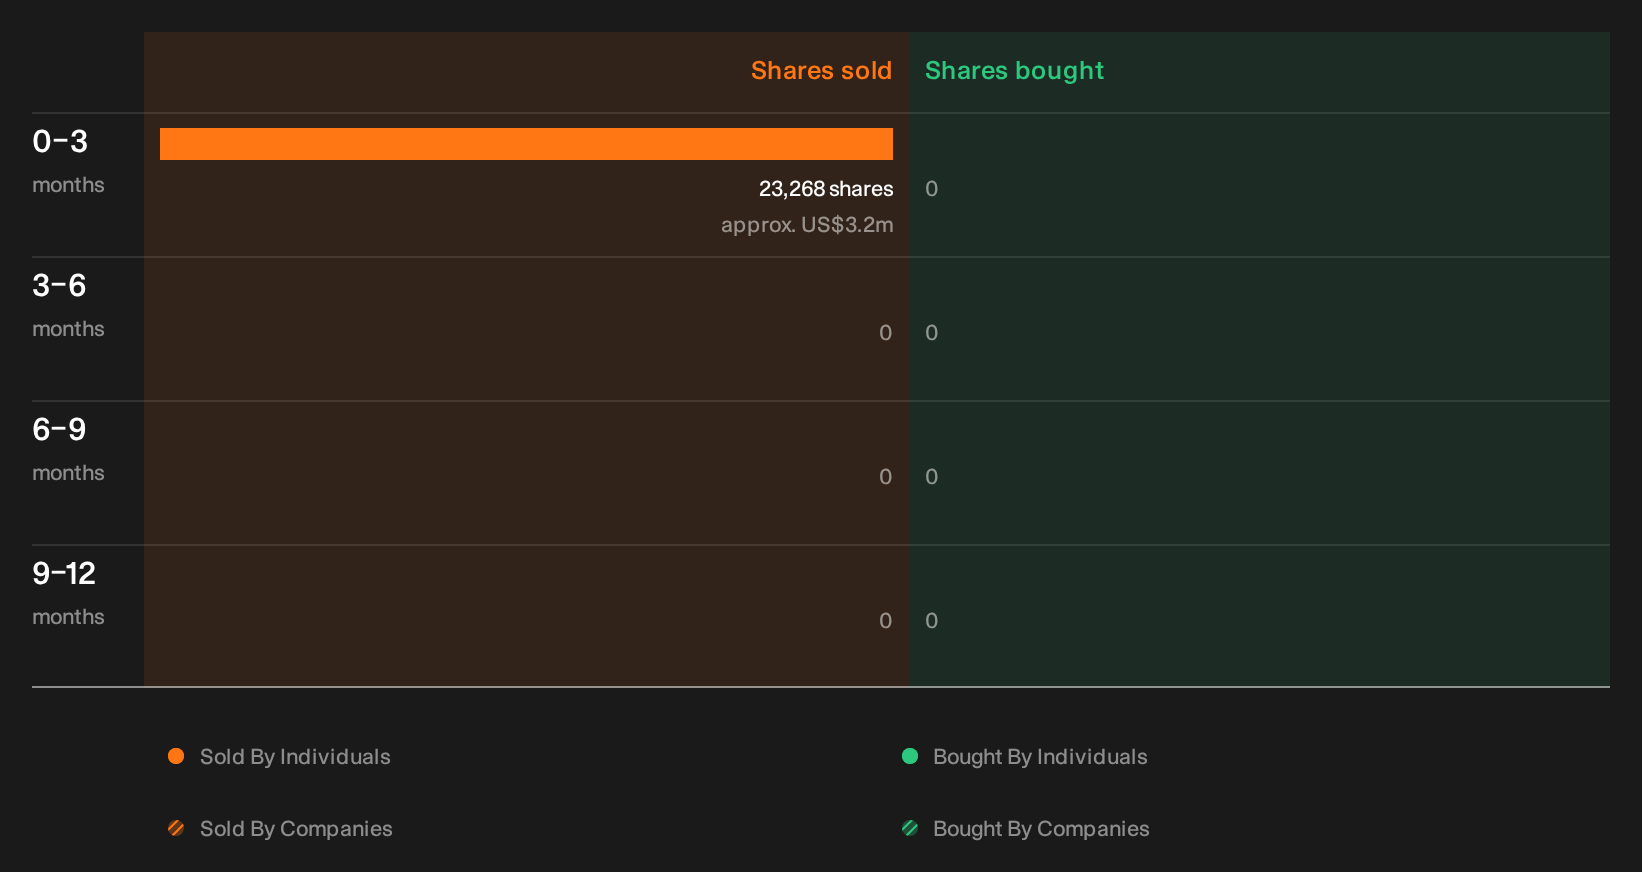
Before you stop at the valuation work, it is worth knowing that recent dealing by people inside ArcBest has been flagged by our checks, with the individuals, size of sales and what they might signal still for you to review. See the recent insider selling flagged for ArcBest.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com