


What Walt Disney (DIS)'s Profitable Streaming Shift Means For Shareholders
- Walt Disney is reporting stronger profitability in its direct to consumer streaming units Disney+, Hulu, and ESPN+, while its Experiences division that includes parks, cruises, and resorts is generating substantial operating income supported by a US$60b investment program.
- The shift from a loss making streaming operation to one with positive operating income, paired with a heavily invested Experiences footprint, gives Disney multiple high margin engines tied to the same intellectual property catalog.
- Next, the focus turns to how Walt Disney's more profitable streaming model could reshape its longer term investment narrative and risk profile.
Walt Disney Investment Narrative Recap
To own Walt Disney, you need to believe its IP flywheel can keep feeding Experiences and direct to consumer streaming with enough high margin content to justify the heavy US$60b park and cruise investment and ongoing content spending. The key near term swing factor is execution on the more profitable streaming model while keeping subscriber churn and content costs in balance.
The biggest operational risk still sits in streaming ad markets and regional park softness, especially in Asia, where weaker demand could weigh on Experiences income. The Character.AI news is interesting but does not materially change those near term drivers or the core risk reward equation right now.
The most relevant development here is Walt Disney moving to license intellectual property from bankrupt Character.AI and hire most of its workforce. That ties into the newer CTO led push on data and AI platforms that is already framed as a potential efficiency and product improvement catalyst across the group.
If those AI tools help refine personalization in Disney+, Hulu, and ESPN+ or improve guest engagement in parks, they could support the existing catalysts around double digit SVOD margins and higher return Experiences capex. Execution risk is real, especially given Character.AI's legal overhang, so investors will likely watch cost discipline, product rollouts, and any regulatory headlines closely.
Walt Disney's current analyst narrative points to revenues of US$113.7b and earnings of US$13.5b by 2029. That profile is based on assumed yearly revenue growth of 4.8% and an earnings increase of about US$4.9b from US$8.6b today.
Uncover how Walt Disney's fair value indicates a 14% potential upside to its current price. This potential could narrow quickly as investors recalibrate expectations.
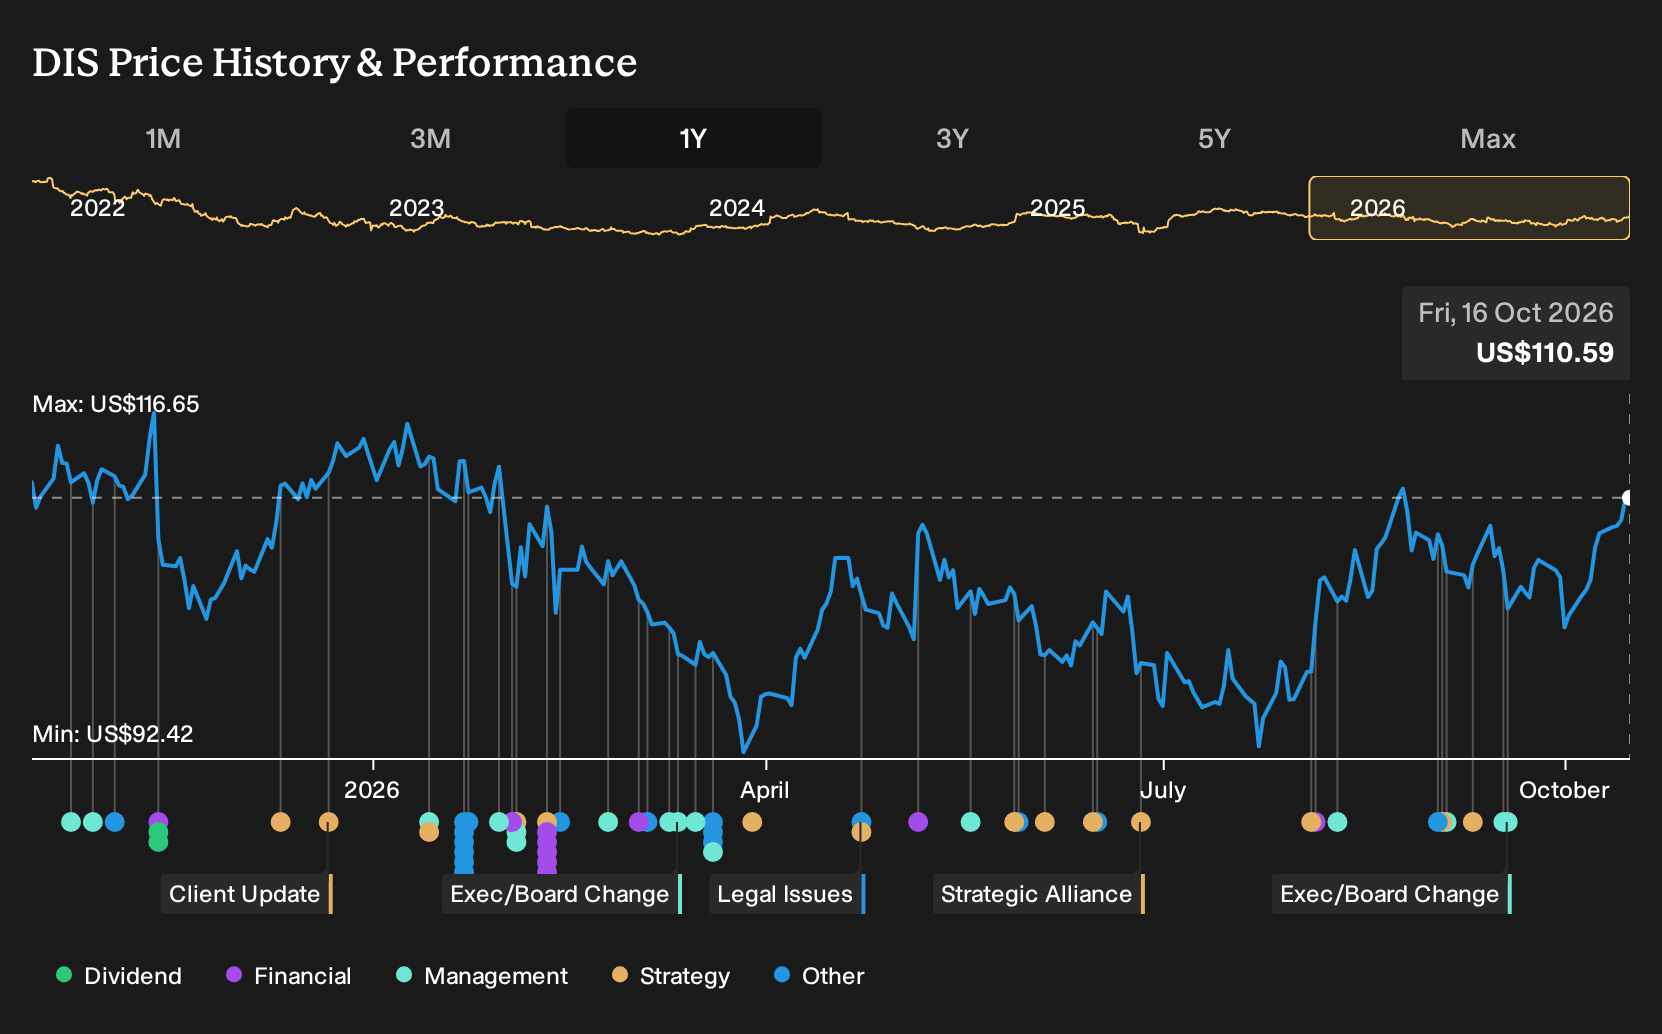
Exploring Other Perspectives
The Walt Disney fair values from five private investors in the Simply Wall St Community cluster tightly between about US$124 and US$135, so you see little spread yet still very different conviction levels. When these are set against streaming ad weakness or Asia park softness, it serves as a reminder that opinions differ widely, which is exactly why exploring multiple viewpoints matters.
Explore 4 other Walt Disney fair value estimates, including one that indicates potential upside of up to 22% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Walt Disney research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Walt Disney. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Walt Disney's overall financial health at a glance.
Looking for more Walt Disney style investment ideas?
After forming a view on Walt Disney, it often helps to compare it with other opportunities that fit different risk, income, and balance sheet profiles. The Simply Wall St Screener can help you quickly filter for stocks that match the characteristics you care about most.
- For investors who want potential mispricing with stronger fundamentals, consider a 33 high quality undervalued stocks that combines quality metrics with attractive valuations.
- If dependable income matters more to you than headline growth, focus on companies with robust payouts by reviewing a 8 dividend fortresses that targets higher yielding opportunities.
- For a calmer ride through market swings, concentrate on financial resilience by filtering for a 32 resilient stocks with low risk scores that scores well on balance sheet strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com