


Leadership Reshuffle Could Matter For Fresenius Stock And Fresenius SE KGaA (XTRA:FRE)
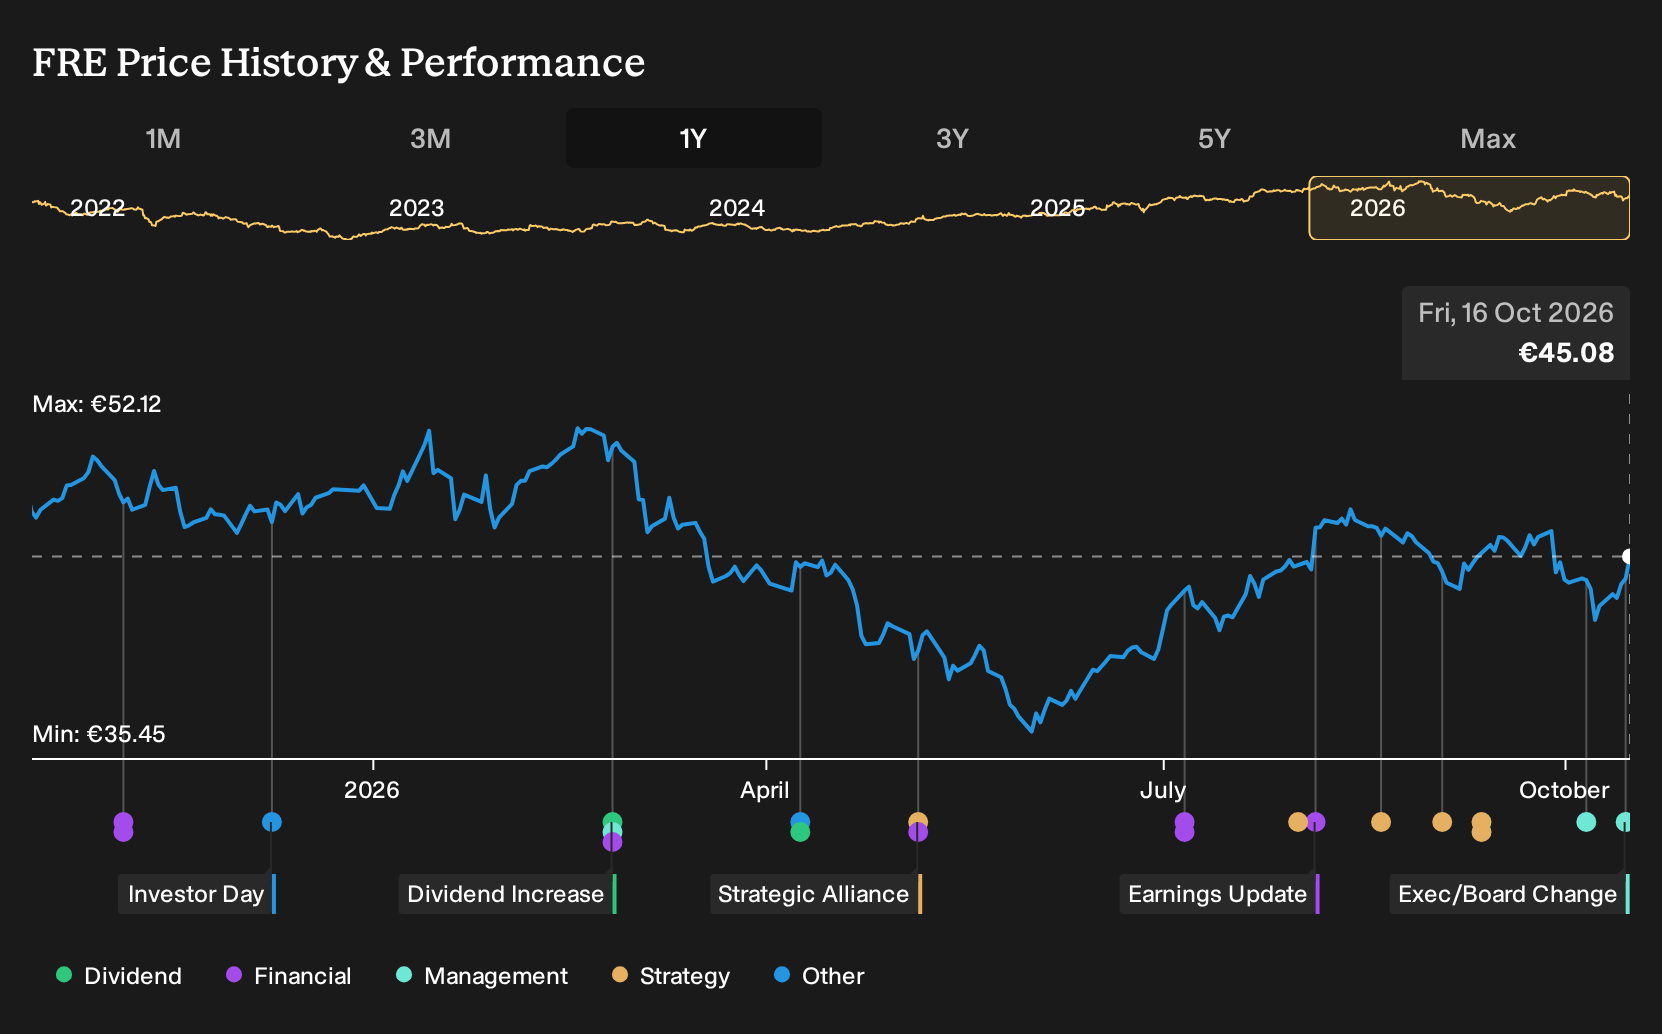
- Fresenius SE KGaA recently reshaped leadership at Fresenius Kabi, adding Dr. Marc-Alexander Mahl to the Management Board for Kabi and formalizing Nutrition as a standalone unit under Sébastien Guery, while Fresenius Ventures hired Nipun Juneja as investment strategy director.
- The creation of a dedicated Nutrition business, together with a reinforced ventures team, signals that Fresenius SE KGaA is sharpening its focus on higher priority platforms and capital allocation decisions inside the wider healthcare portfolio.
- We will look at how Fresenius SE KGaA's investment narrative is influenced by Mahl's elevation to the Management Board at Kabi.
Scan how Fresenius SE KGaA's reshaped healthcare focus compares with other potential opportunities by lining it up against our hand picked list of solid balance sheet and fundamentals (204 results).
Fresenius SE KGaA Investment Narrative Recap
To own Fresenius SE KGaA, you need to be comfortable with a healthcare group that leans heavily on Fresenius Kabi growth platforms while running a large hospital network through Helios. The near term story turns on whether Biopharma, Nutrition and MedTech can keep supporting higher EBIT margins without cost inflation eating into that progress.
The biggest operational swing factor right now is margin resilience against wage, energy and supply chain pressure, with China pricing and tender exposure an added complication for Kabi, especially in nutrition. The leadership reshuffle itself does not look like a material short term catalyst, although execution under the new set up still matters.
The most relevant update here is Marc Alexander Mahl joining the Fresenius Management Board while still steering Kabi’s Pharma unit and overseeing the Nutrition segment structure. That keeps an experienced insider directly accountable for the growth platforms analysts already highlight as key to earnings power.
For investors, the operational question is whether this governance tweak improves how Fresenius SE KGaA allocates capital across Biopharma, Nutrition and MedTech, while keeping Helios margins within the targeted 10 to 12% range. Any stumble on pricing, Chinese tenders or cost control would work against the catalysts analysts have built into their forecasts.
Fresenius SE KGaA's narrative projects €26.9 billion revenue and €2.5 billion earnings by 2029. This projection is based on 4.9% yearly revenue growth and an earnings increase of about €0.9 billion from €1.6 billion today.
Uncover why Fresenius SE KGaA's fair value indicates a 23% potential upside to its current price, as investors reassess how long that discount can realistically last.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit far apart, from €55.59 to €144.11, which shows how differently retail investors are framing Fresenius SE KGaA today. Before the management reshuffle and Ventures hire, many focused on Kabi growth platforms as potential earnings drivers. Weigh that against inflation, China tender pressure and shifting sentiment, then explore the full spread of views.
Explore another Fresenius SE KGaA fair value estimate, including one that suggests there could be as much as 220% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fresenius SE KGaA research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fresenius SE KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fresenius SE KGaA's overall financial health at a glance.
Looking for more investment ideas beyond Fresenius SE KGaA?
Once you have formed a view on Fresenius SE KGaA, it can help to cross check that thinking against a wider watchlist of opportunities that fit your risk and income preferences.
- If you want potential growth at a lower share price, scan a curated set of 134 elite penny stocks with strong financials that still clear solid financial hurdles.
- For readers who care most about getting quality at a discount, line up your thesis against a focused group of 189 high quality undervalued stocks that pair stronger balance sheets with appealing valuations.
- If portfolio income is the priority, round out your research with a targeted group of 215 dividend fortresses that aim for reliable payouts above 5%.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com