


The Bet Astellas Pharma Holders Made
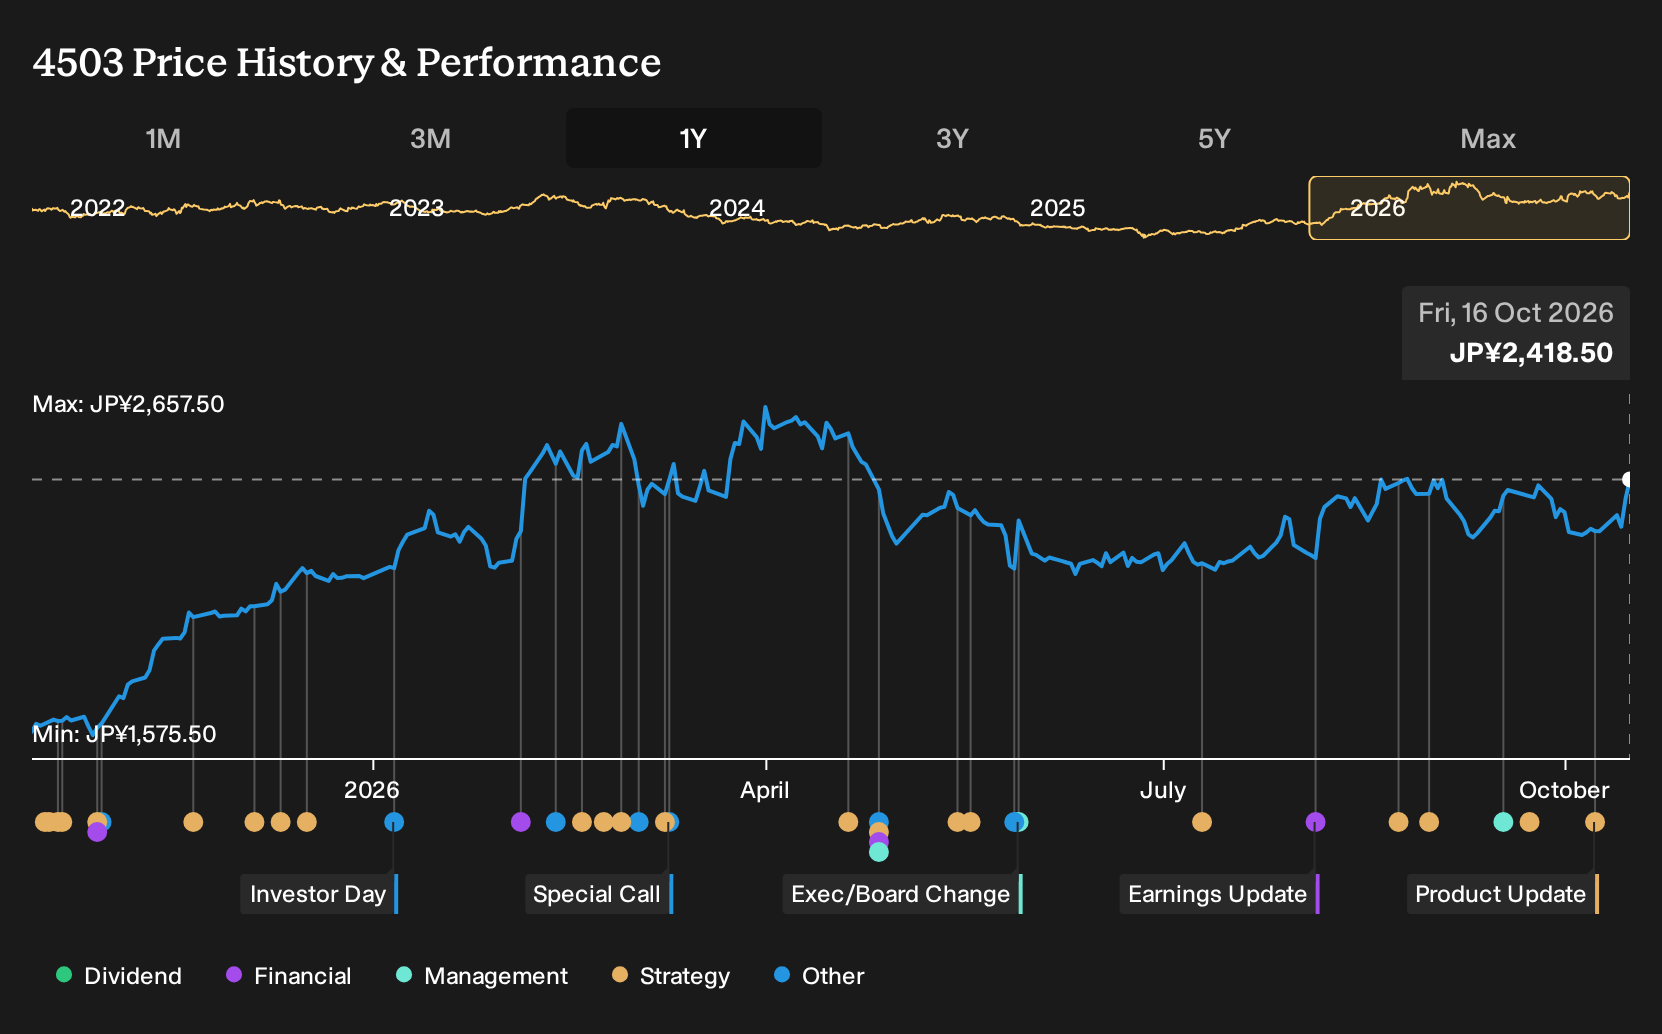
If you only glanced at headlines, the Astellas Pharma story over the past year might look like it turned on big oncology moves such as the Keytruda Padcev priority review in bladder cancer. Investors who held Astellas Pharma over the past year are up 55.5%, including dividends. If you were deciding back on 16 October 2025, what conviction about future cancer and rare disease drugs would you have needed before any of this news arrived?
Astellas Pharma has already moved. Pinpoint other ways to investigate the theme among 10 healthcare AI stocks.
The Argument You Would Have Been Weighing Up On Astellas Pharma
The shares cost ¥1,604 at the start of the period, and Astellas Pharma sat between two very different stories about its future.
The bullish view saw oncology and rare disease drugs driving global demand. In that case, a Fair Value of ¥1,725 was implied if that script played out, supported by an assumed 9.9% profit margin and a 19.3x future P/E.
The cautious case focused on patent expiries and pricing reform. This view paired a Fair Value of ¥1,300 with concern that revenue could decline 5.4% a year despite margin improvement.
What The Evidence Did To The Astellas Pharma Argument
The clearest new fact for Astellas Pharma was the Q1 2027 report. Revenue rose to ¥640,914m and net income to ¥141,828m, with net margin moving from 13.5% to 22.1%. That shift in profitability supported the optimistic case that higher margins could justify a richer P/E, even if earlier worries around patent expiries and pricing pressure remained unresolved.
The lesson is simple. When a thesis hangs on margin improvement, you check the reported net margin and absolute profit, not just the top line or share price, and see whether that specific promise is turning up in the numbers.
What Astellas Pharma's One Year Run Already Prices In
After rising 55.5% over the past year, Astellas Pharma now trades at ¥2,418. The selected Narrative places its Fair Value below that level, arguing that the current quote already prices in smooth execution on margins, product mix and capital plans.
The key question for investors is what must keep going right for this price to hold. A buyer today would need confidence that newer brands and late stage drugs can offset XTANDI pressure and still support the implied margin and earnings path.
"Although Astellas Pharma outlines a shift from XTANDI toward higher margin brands, the expected drop of about ¥50b in XTANDI revenue from pricing pressure and emerging patent expiries could leave a larger gap than these products fill, which would weigh on total revenue and earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where Astellas Pharma’s Theme Extends
Astellas Pharma points you toward rising focus on complex chronic conditions. Oncology and rare disease are one side of that story.
On the other side sit obesity and diabetes therapies that reshape long term treatment plans. These medicines address metabolic risk alongside cardiovascular and hormone issues.
One large player in that field is developing oral treatments and delivery devices. It is also using AI to move more drug candidates into early testing.
If that effort keeps expanding the pipeline, your research list may extend beyond cancer and rare disease specialists.
One Narrative has already put a figure on it. → Uncover the company trading 15% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com