


Asian Undervalued Small Caps With Insider Activity To Explore In October 2026
As the Asian markets navigate a landscape marked by heightened inflation pressures and shifting investor sentiment, small-cap stocks have experienced notable fluctuations. With the Russell 2000 Index recently facing a decline, investors are increasingly drawn to sectors offering value opportunities amid broader market rotations. In this context, identifying small-cap companies with strong fundamentals and insider activity can provide valuable insights into potential growth prospects within Asia's dynamic economic environment.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 3.9x | 0.8x | 22.75% | ★★★★★★ |
| Q Technology (Group) | 3.3x | 0.2x | 47.33% | ★★★★★☆ |
| Charter Hall Long WALE REIT | 8.5x | 12.0x | 40.06% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.9x | 0.9x | 39.62% | ★★★★★☆ |
| Centurion | 15.7x | 3.0x | 20.50% | ★★★★☆☆ |
| Australian Finance Group | 7.5x | 0.3x | 18.17% | ★★★★☆☆ |
| Aztech Global | 10.6x | 0.9x | -65.85% | ★★★★☆☆ |
| Clover | 16.3x | 1.7x | 46.94% | ★★★☆☆☆ |
| Kina Securities | 8.4x | 1.9x | -9.05% | ★★★☆☆☆ |
| Citicore Energy REIT | 13.7x | 10.4x | 24.64% | ★★★☆☆☆ |
Let's uncover some gems from our specialized screener.
Australian Finance Group (ASX:AFG)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Australian Finance Group is a financial services company primarily involved in mortgage broking and distribution, with a market capitalization of A$0.52 billion.
Operations: The company's primary revenue stream is from its Distribution segment, contributing A$1.07 billion, complemented by the Manufacturing segment at A$378.90 million. Over recent periods, net profit margin has shown a notable declining trend from 6.86% to 3.45%. Operating expenses have consistently increased, impacting net income despite rising revenues.
PE: 7.5x
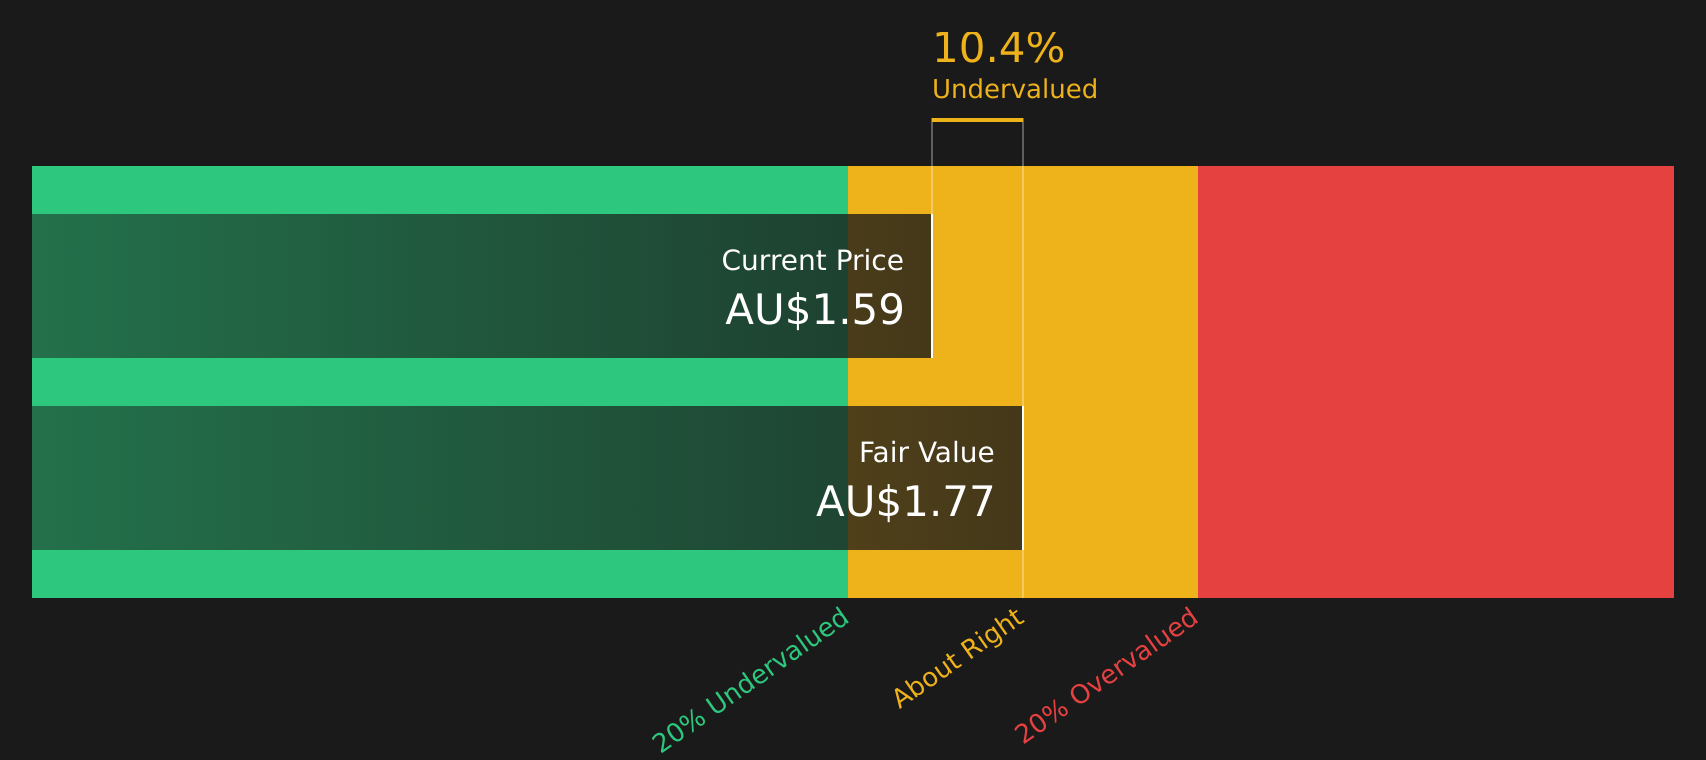
Australian Finance Group, a key player in financial services, recently experienced significant changes. Dropping from the S&P/ASX 300 and Small Ordinaries Indexes in September 2026 reflects market challenges. However, insider confidence is evident with Craig Carter's purchase of 150,000 shares valued at A$227,443. Despite relying on higher-risk external borrowing for funding and facing debt coverage issues by operating cash flow, earnings are forecasted to grow annually by 7.55%. The retirement of co-founder Brett McKeon marks a leadership transition as David Flynn joins the board with extensive capital markets expertise.
Midea Real Estate Holding (SEHK:3990)
Simply Wall St Value Rating: ★★★★★☆
Overview: Midea Real Estate Holding is a company engaged in asset operation, real estate technology, project management services, and property management services with a market cap of CN¥13.5 billion.
Operations: Midea Real Estate Holding generates revenue primarily from Property Management Services, which is the largest contributor, followed by Asset Operation and Project Management Services. The company's cost of goods sold (COGS) significantly impacts its gross profit, with a gross profit margin peaking at 34.36% in recent quarters. Operating expenses include notable allocations to sales and marketing as well as general and administrative functions.
PE: 5.6x
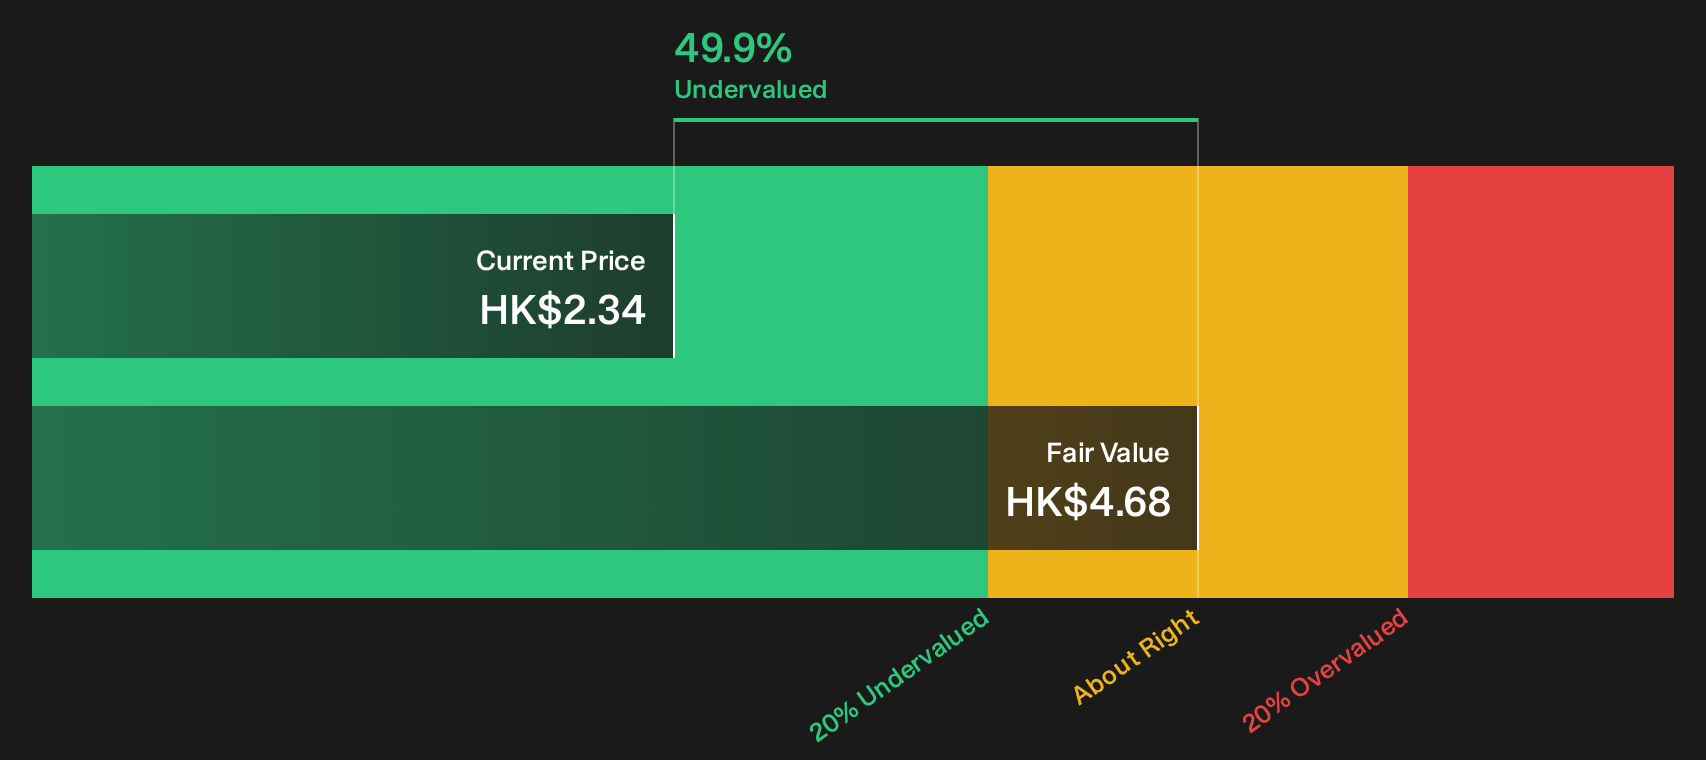
Midea Real Estate Holding, a smaller player in Asia's real estate sector, shows mixed signals. While their net profit margin has decreased from 27.1% to 12.6%, they maintain a cautious funding strategy with no customer deposits and rely entirely on external borrowing. Recent earnings for the first half of 2026 showed sales at CNY 1,882 million and net income at CNY 255 million, both down from last year. Insider confidence is evident as insiders increased their holdings earlier this year, suggesting belief in future prospects despite forecasted earnings decline over the next three years by an average of 1.1% annually.
Bukit Sembawang Estates (SGX:B61)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Bukit Sembawang Estates is primarily engaged in property development, with additional activities in hospitality and investment holding, and has a market capitalization of approximately SGD 1.23 billion.
Operations: The primary revenue stream is property development, contributing SGD 334.80 million, followed by hospitality and investment holding. The cost of goods sold (COGS) significantly impacts profitability, with a gross profit margin showing fluctuations from 65.33% in September 2016 to 13.39% in September 2023. Operating expenses have remained relatively stable over time, while net income has varied, reflecting changes in non-operating expenses and other financial factors impacting the bottom line.
PE: 8.8x
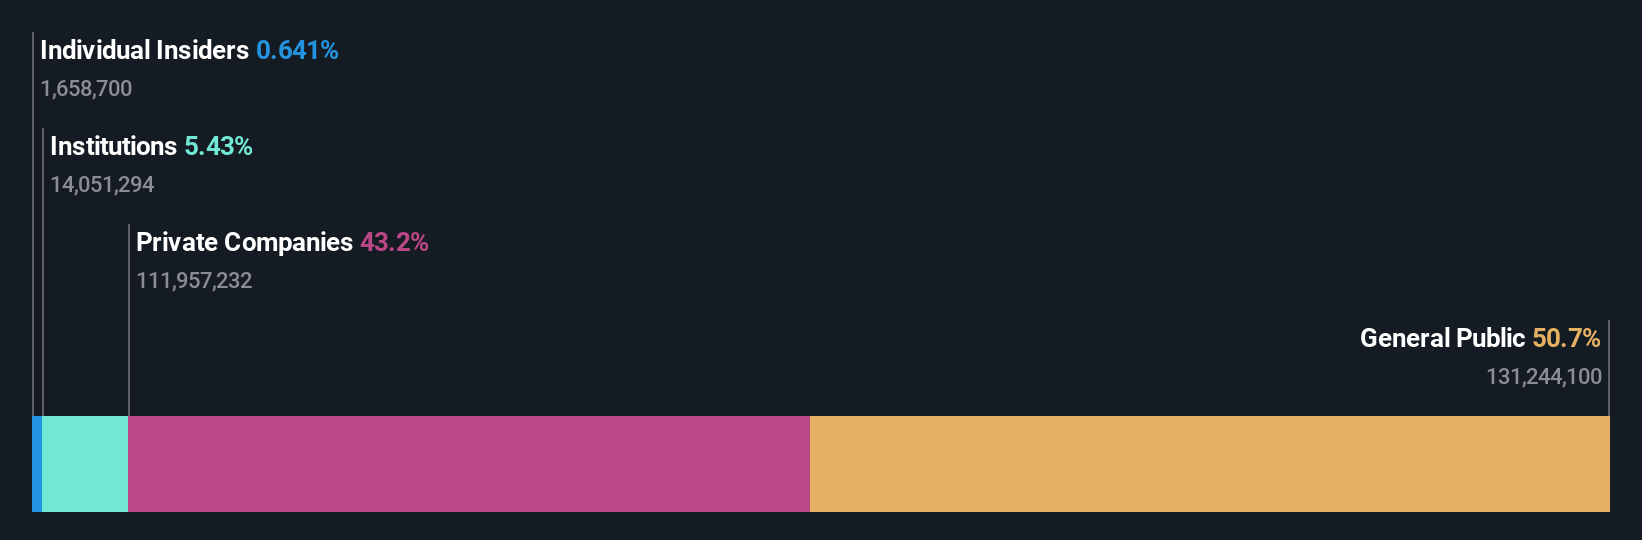
Bukit Sembawang Estates, a smaller player in the Asian market, shows potential despite some challenges. Recently approved special dividends of 18 cents per share reflect shareholder value focus. Insider confidence is evident with Non-Executive Director Chien Shih Lee acquiring 26,400 shares for S$116,157 in recent months. Although revenue is projected to grow by 31% annually, earnings might dip by 6% yearly over the next three years due to reliance on riskier external funding sources.
- Get an in-depth perspective on Bukit Sembawang Estates' performance by reading our valuation report here.
Evaluate Bukit Sembawang Estates' historical performance by accessing our past performance report.
Turning Ideas Into Actions
- Gain an insight into the universe of 59 Undervalued Asian Small Caps With Insider Buying by clicking here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com