


Asian Market Gems: 3 Stocks Priced Below Their Estimated Intrinsic Values
As Asian markets navigate the complexities of global inflation pressures and geopolitical tensions, investors are increasingly seeking opportunities in undervalued stocks that may offer potential value amidst the volatility. Identifying stocks priced below their estimated intrinsic values can provide a strategic edge, especially in an environment where discerning investment choices become crucial for navigating uncertain market conditions.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Xiamen King Long Motor Group (SHSE:600686) | CN¥9.41 | CN¥18.51 | 49.1% |
| Shizuki Electric (TSE:6994) | ¥1219.00 | ¥2362.76 | 48.4% |
| Nissui (TSE:1332) | ¥1108.00 | ¥2165.31 | 48.8% |
| Kumagai GumiLtd (TSE:1861) | ¥1214.00 | ¥2410.08 | 49.6% |
| Innocean Worldwide (KOSE:A214320) | ₩18250.00 | ₩36186.92 | 49.6% |
| Inner Mongolia ERDOS ResourcesLtd (SHSE:600295) | CN¥14.29 | CN¥28.27 | 49.4% |
| ENN Energy Holdings (SEHK:2688) | HK$50.15 | HK$97.07 | 48.3% |
| Double Medical Technology (SZSE:002901) | CN¥39.84 | CN¥79.12 | 49.6% |
| China Coal Energy (SEHK:1898) | HK$10.37 | HK$20.16 | 48.6% |
| Apex Mining (PSE:APX) | ₱17.20 | ₱33.35 | 48.4% |
Let's explore several standout options from the results in the screener.
Kumagai GumiLtd (TSE:1861)
Overview: Kumagai Gumi Co., Ltd. is a construction company that operates both in Japan and internationally, with a market capitalization of ¥206.31 billion.
Operations: The company's revenue is primarily derived from Building Construction at ¥252.69 billion, followed by Civil Engineering at ¥116.10 billion, and its subsidiaries contributing ¥125.47 million.
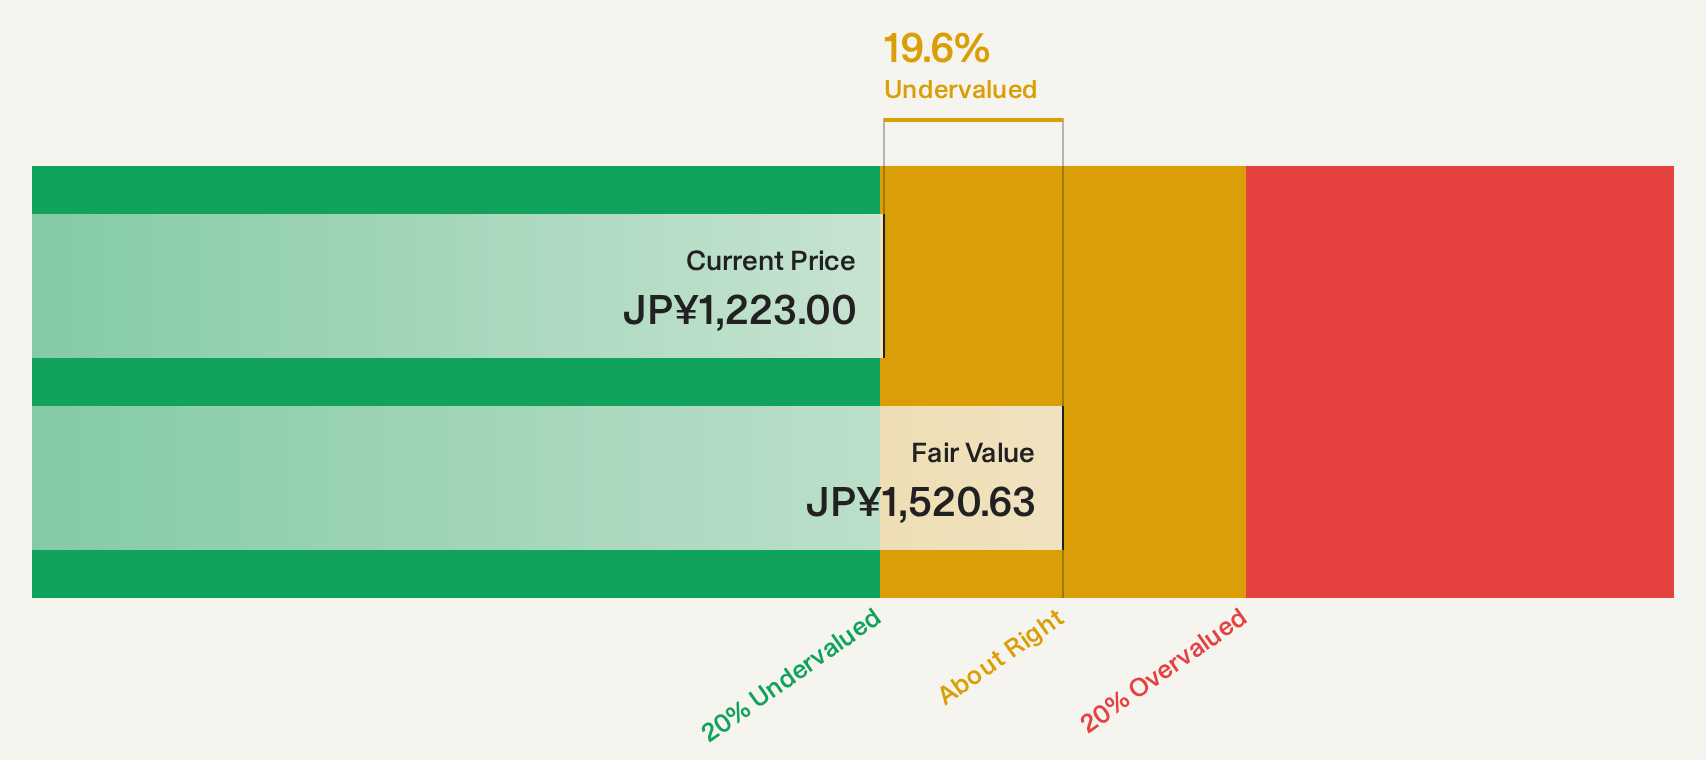
Estimated Discount To Fair Value: 49.6%
Kumagai Gumi Ltd. trades at ¥1,214, significantly below its estimated future cash flow value of ¥2,410.08 and 49.6% under its fair value estimate. Despite a forecasted annual earnings growth of 10.4%, surpassing the Japanese market average, revenue growth is slower at 2.7%. Recent earnings showed improved net income despite lower sales, with guidance indicating steady profitability ahead. The stock offers a reliable dividend yield of 4.12%.
- The analysis detailed in our Kumagai GumiLtd growth report hints at robust future financial performance.
- Dive into the specifics of Kumagai GumiLtd here with our thorough financial health report.
DIC (TSE:4631)
Overview: DIC Corporation is a global manufacturer and seller of printing inks, organic pigments, and synthetic resins with a market cap of ¥479.44 billion.
Operations: Revenue segments include printing inks at ¥343.20 billion, organic pigments at ¥118.50 billion, and synthetic resins at ¥192.30 billion.
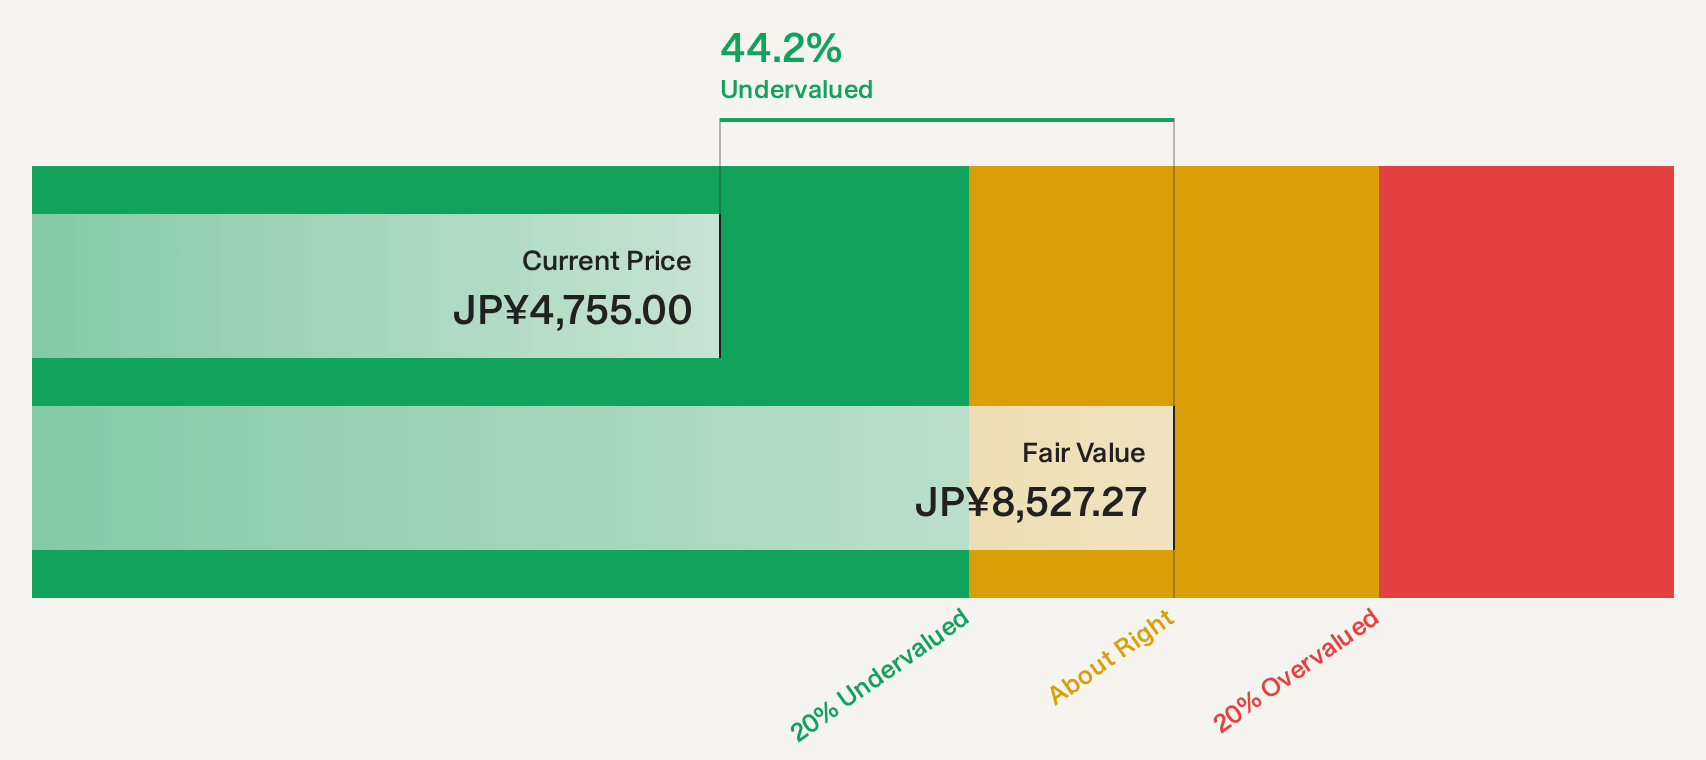
Estimated Discount To Fair Value: 41.2%
DIC Corporation is trading at ¥5,062, well below its estimated future cash flow value of ¥8,613.77 and 41.2% under fair value estimates. Despite slower forecasted earnings growth of 1.9% annually compared to the Japanese market average, recent earnings showed significant improvement with net income rising to ¥37.19 billion from ¥13.09 billion a year ago. The company has initiated a share buyback program and increased dividends, reflecting efforts to enhance shareholder value amidst high debt levels and volatile share prices.
- In light of our recent growth report, it seems possible that DIC's financial performance will exceed current levels.
- Unlock comprehensive insights into our analysis of DIC stock in this financial health report.
Ichikoh Industries (TSE:7244)
Overview: Ichikoh Industries, Ltd. develops, manufactures, and sells automotive lamps and parts to automobile manufacturers both in Japan and internationally, with a market cap of ¥55.66 billion.
Operations: The company generates revenue primarily from its Automotive Parts segment, amounting to ¥121.32 billion.
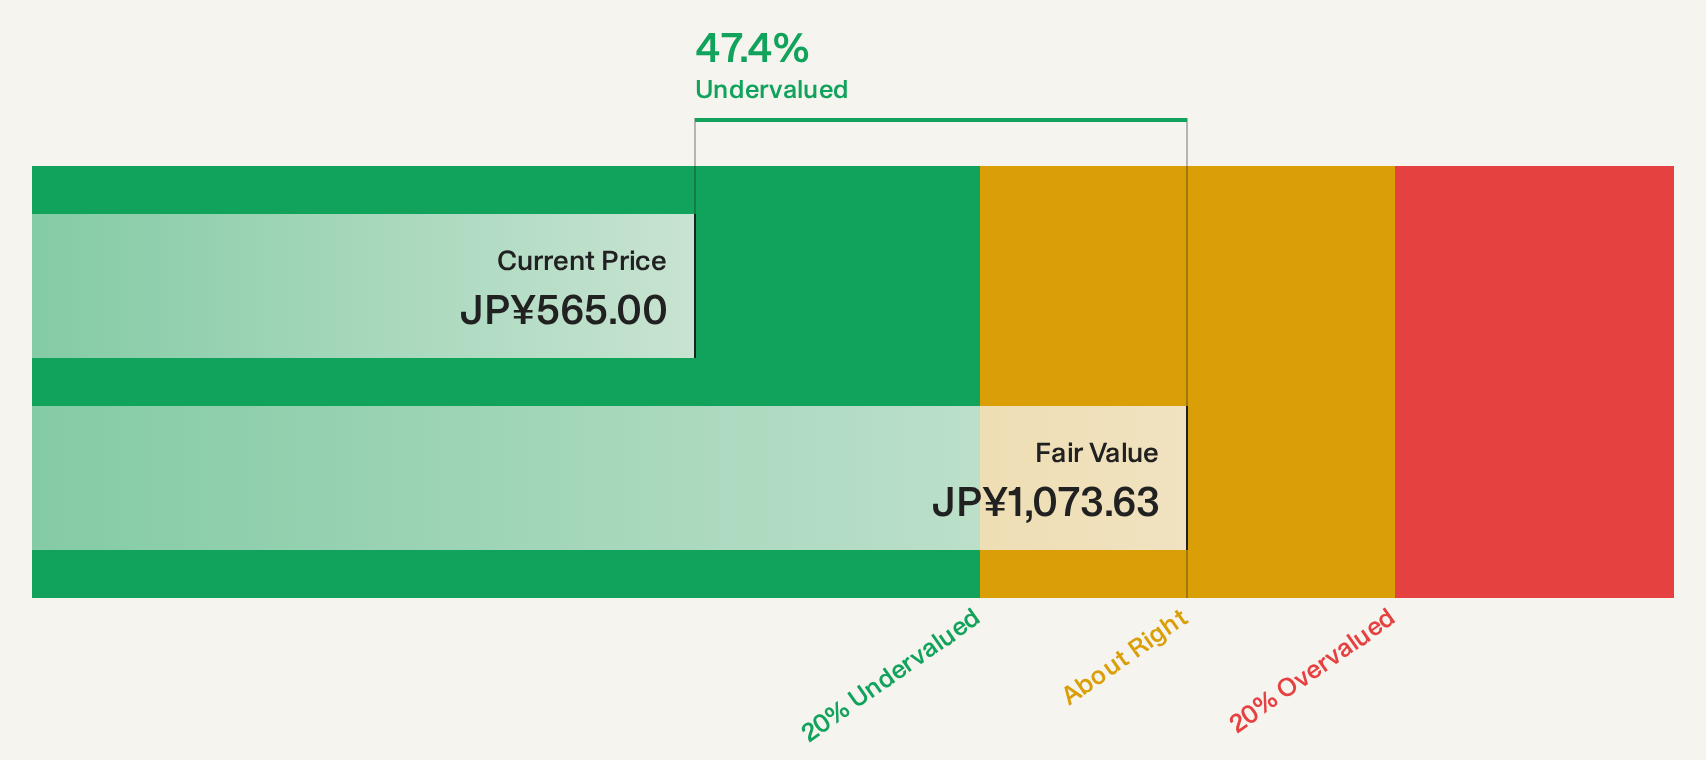
Estimated Discount To Fair Value: 45.3%
Ichikoh Industries is trading at ¥578, significantly below its estimated future cash flow value of ¥1,057.25 and 45.3% under fair value estimates. Recent earnings showed a notable increase in net income to ¥3.76 billion from ¥2.60 billion a year ago, supported by sales growth to ¥59.77 billion from ¥55.55 billion previously. Despite slower forecasted revenue and profit growth compared to the Japanese market, the company increased dividends, indicating robust retained earnings support amidst an unstable dividend history.
- According our earnings growth report, there's an indication that Ichikoh Industries might be ready to expand.
- Click here and access our complete balance sheet health report to understand the dynamics of Ichikoh Industries.
Key Takeaways
- Gain an insight into the universe of 174 Undervalued Asian Stocks Based On Cash Flows by clicking here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com