


Why Lamb Weston Holdings (LW) Is Getting Attention Today
Lamb Weston Holdings (LW) just put a lot on the table at once. You have softer first quarter earnings, a cautious sales outlook for fiscal 2027, a maintained dividend, and an effectively completed multiyear buyback.
Recent trading tells a mixed story for Lamb Weston Holdings. The share price is up 11.95% over the past week and 26.72% year to date, yet the 1 year total shareholder return is down 15.02% and the 3 year total shareholder return is down 34.19%. Investors appear to be weighing the softer earnings and cautious low single digit sales outlook against the dividend, completed buyback and leadership transition news, with short term momentum improving even as longer term returns remain weak.
Spot fresh ideas by comparing Lamb Weston Holdings with a curated list of food and consumer staples players that currently screen as 33 high quality undervalued stocks.Lamb Weston’s sharp rebound sits between two readings: either a fresh vote of confidence in a still profitable frozen potato franchise, or a short term reset in sentiment. The valuation numbers now need to break that tie.
Most Popular Narrative: 12% Overvalued
Lamb Weston Holdings closed at $53.59, while the most followed narrative pins fair value closer to $48.06. The fresh share price rebound sits above that reference point and turns the focus to whether the recent reset in expectations really changes the long-term story.
The international segment is where the framing has moved the most. Mike Smith attributed EMEA weakness to a slowdown in demand and said the company was “controlling the controllables” while it worked through the Netherlands closures. The call now places the cause on supply. Mike Smith calls the European crop “a tale of two years,” argues that raw potato quality and yield “is likely going to be the limiter,” and says “not all open industry capacity will be used.”
See why 2 investors see Lamb Weston Holdings as 12% overvalued.
Result: Fair Value of $48.06 (OVERVALUED)
Still, Lamb Weston’s international crop constraints and the quiet ERP pause both hang over the story and could quickly challenge the current narrative of overvaluation.
Find out about the key risks to this Lamb Weston Holdings narrative.
Another View: Cash Flow Says Lamb Weston Is Cheap
The first take paints Lamb Weston Holdings as about 12% overvalued at $53.59 versus a narrative fair value of $48.06. A different lens tells a very different story. The SWS DCF model points to a future cash flow value of $138.49, which frames the shares as trading well below that estimate.
The gap between a $48.06 narrative anchor and a $138.49 DCF outcome is wide. One method leans on earnings and sentiment, and the other on projected cash generation. For investors trying to size up valuation risk or opportunity, which set of assumptions feels more realistic for how Lamb Weston actually earns its money over time?
Look into how the SWS DCF model arrives at its fair value.
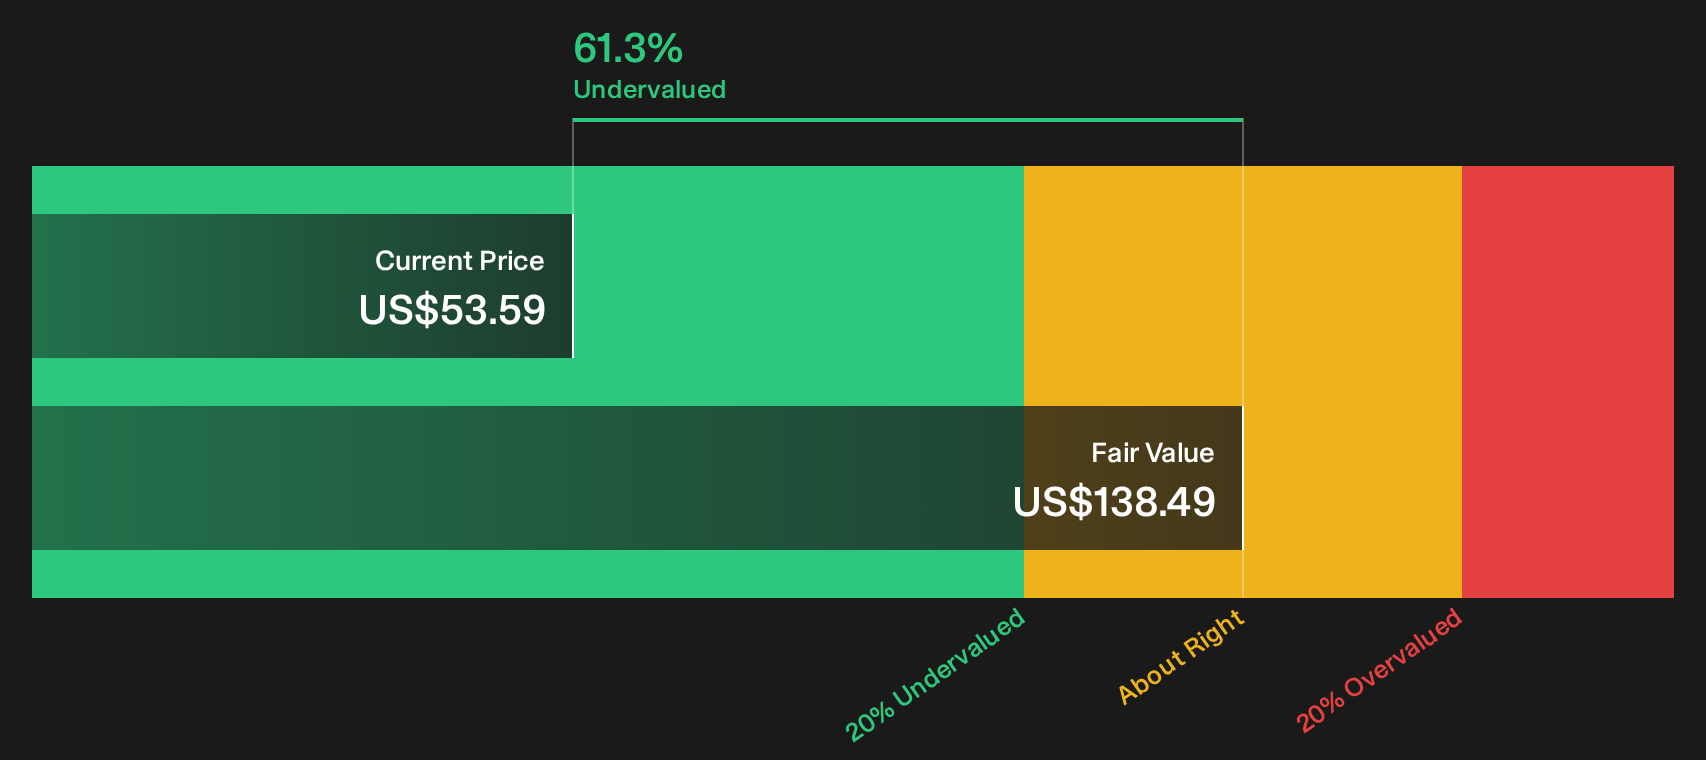
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lamb Weston Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Lamb Weston might feel confusing, which is exactly why checking the full picture yourself matters right now. To see how the valuation story balances those concerns and bright spots, review the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lamb Weston Holdings?
Do not stop with Lamb Weston Holdings when you can quickly line up a wider watchlist. The next opportunity might already fit the exact profile you want.
- Target steadier potential by reviewing companies that appear to combine quality with attractive pricing using the 33 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that currently feature higher yields and payout support with the 8 dividend fortresses.
- Prioritise resilience by filtering for companies that show robust finances and cleaner balance sheets with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com