


Vita Coco Company (COCO) Could Be 28% Undervalued On Rising Earnings Optimism
Vita Coco Company (COCO) has drawn fresh attention after its shares rose 1.77% on a down market day, ahead of an October 22 earnings report with EPS projected to increase 27.50% year over year.
Those short term moves sit on top of a choppier backdrop, with a 30 day share price return of 5.14% but a 90 day share price decline of 20.55% as investors reassess growth expectations against recent gains. Even with that pullback, Vita Coco Company’s total shareholder return of 43.29% over one year and 139.45% over three years indicates that momentum has been building over time rather than fading.
Scan for other beverage and consumer stocks showing similar earnings momentum and sector tailwinds by checking the hand-picked 33 high quality undervalued stocks alongside Vita Coco Company.
Vita Coco Company now trades about 30% below one intrinsic value estimate and roughly 34% under the average analyst target, even after the latest bounce. Is that discount caution well placed or too harsh?
Most Popular Narrative: 28% Undervalued
Against a last close of $58.69, the most followed narrative sets Vita Coco Company’s fair value at $81.90, implying a sizeable gap that hinges on how far coconut water and related products can scale without margins slipping.
Rapid expansion of private label coconut water, with 28% growth in Q1 2026, 83% growth in Q2 2026 to US$27 million and U.S. private label expected to grow 90% to 100% for 2026, can deepen retailer relationships and better utilize the supply chain, which supports overall revenue and EBITDA generation even at lower unit margins.
See why 24 investors see Vita Coco Company as 28% undervalued.
Result: Fair Value of $81.90 (UNDERVALUED)
Still, Vita Coco Company faces two clear pressure points: elevated packaging and freight costs, and a tightly run supply chain where disruptions can quickly hit margins.
Find out about the key risks to this Vita Coco Company narrative.
Another View On Vita Coco Company Valuation
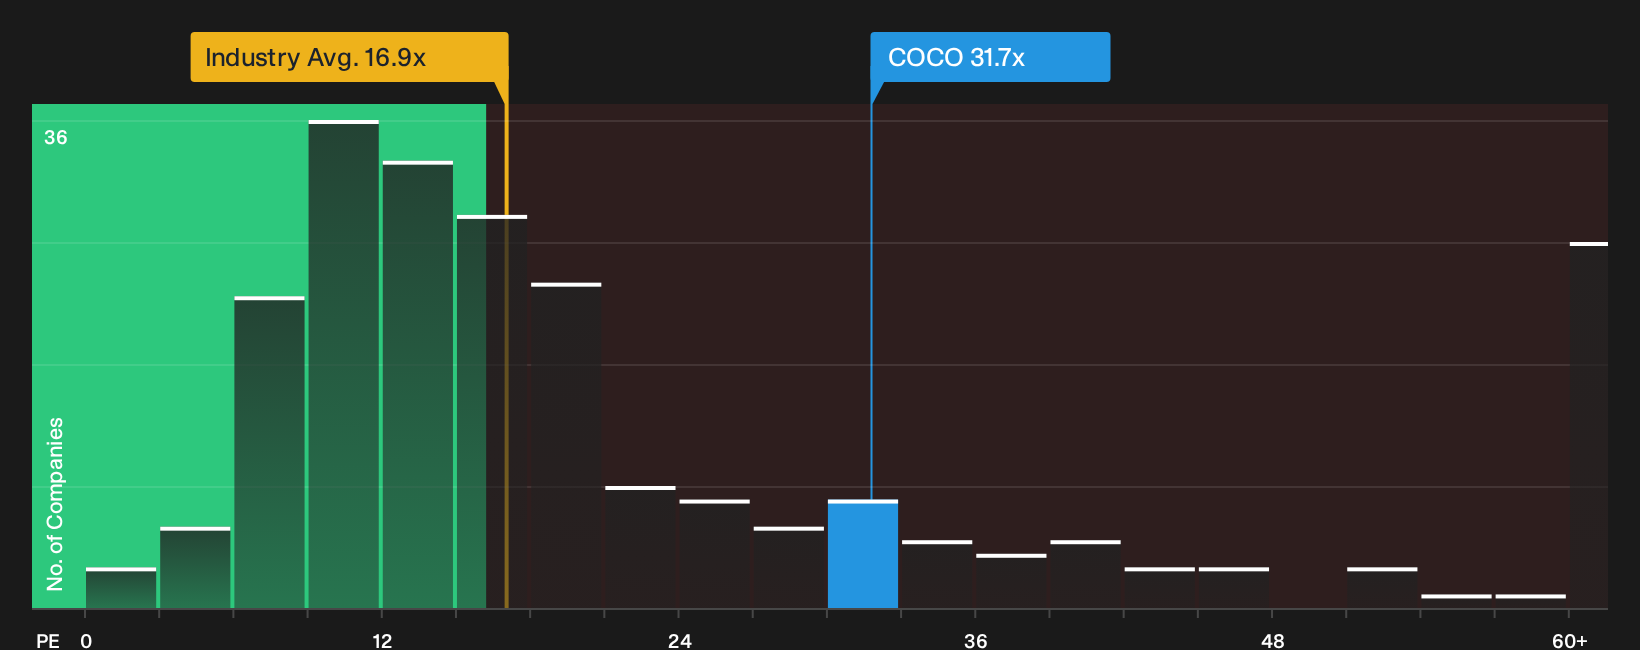
The first narrative leans on future earnings and fair value targets. A simple P/E cross-check tells a different story. Vita Coco Company trades on 31.7x earnings, almost double the global Beverage sector at 16.9x and well above a fair ratio of 18x, even though it sits below a 54.3x peer average. Is the premium pointing to quality, or is it simply thinning the margin of safety for new buyers?
To see how this richer earnings multiple compares in more detail, including where the fair ratio suggests the market could shift toward next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Vita Coco Company splits pretty cleanly between a premium-looking P/E and a discount to some fair value estimates, so do not just rely on the headline takeaways. Move quickly, review the underlying metrics yourself, and then weigh those against the 4 key rewards.
Looking for more Vita Coco Company sized opportunities?
Do not stop your work with Vita Coco Company alone. Broaden your watchlist with fresh ideas that match your risk appetite and income goals.
- Hunt for underappreciated quality by scanning a curated pool of 20 high quality undiscovered gems that pair strong fundamentals with quieter market attention.
- Prioritize resilience in tougher markets and filter for companies with stronger finances using the focused list of solid balance sheet and fundamentals (25 results).
- Dial down portfolio swings and target steadier performers by reviewing the targeted 32 resilient stocks with low risk scores before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com