


Is Chudenko (TSE:1941) Undervalued Following Fresh DCF Interest?
Fresh attention on Chudenko (TSE:1941) is coming from a recent Discounted Cash Flow analysis, which suggests the company’s estimated intrinsic value sits well above its current share price.
Short term, Chudenko’s share price has been relatively steady, with a modest 7 day share price return of 1.18%. The year to date share price return of 13.94% and 1 year total shareholder return of 37.84% point to momentum that has been building over several years.
Spot 13 high quality undervalued stocks that, like Chudenko, currently trade below their estimated intrinsic value based on cash flow strength and balance sheet quality.For Chudenko, that steady climb in the share price can look like a cleaner read on the underlying cash engine, or just investors crowding in late. The valuation work helps separate those two stories.
Chudenko’s cash flow value versus the market price
The SWS DCF model currently estimates Chudenko’s future cash flow value at ¥8,668.61, compared with a last close of ¥5,150. Based on that gap, the stock screens as undervalued on this measure.
A discounted cash flow model projects the cash the business is expected to generate over time, then discounts those future amounts back into today’s money. That process puts the focus on the durability and timing of cash flows rather than short term price swings.
For an equipment engineering specialist like Chudenko, with forecast earnings growth of 9.33% per year and annual revenue growth expectations of 6.3%, anchoring on future cash generation can help separate cyclical swings in construction activity from the longer term contract and service profile behind the current numbers.
Look into how the SWS DCF model arrives at its fair value.Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of ¥8,668.61 (UNDERVALUED)
Still, Chudenko’s reliance on construction activity and its focus on the Japanese market make the story sensitive to project delays and domestic spending slowdowns.
Find out about the key risks to this Chudenko narrative.
Another view on Chudenko’s valuation
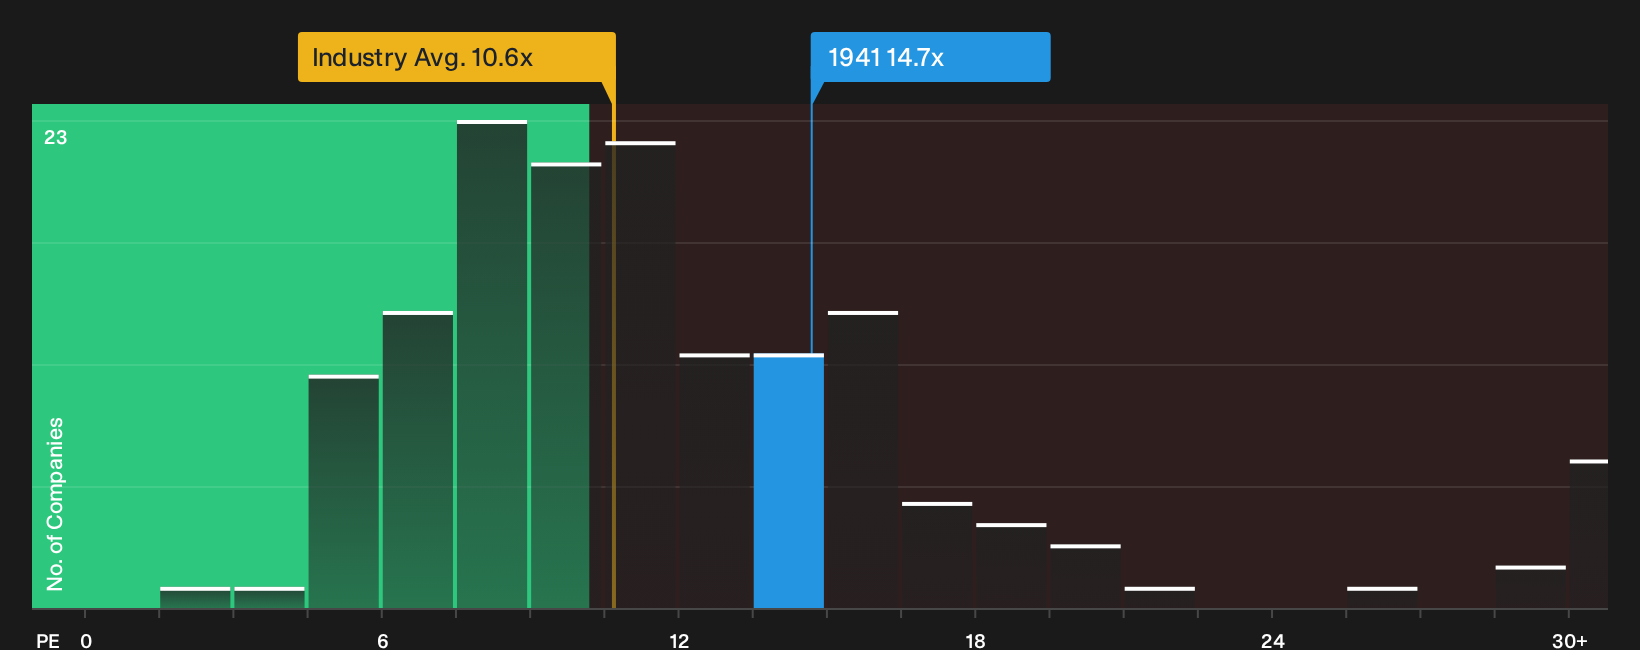
The cash flow story points one way for Chudenko, yet the market’s pricing tells something different. At a P/E of 14.7x, the stock trades richer than the JP Construction group on 10.6x, above peers at 12.9x, and slightly ahead of a 14.6x fair ratio that the market could move toward.
That premium suggests investors are already paying up for quality earnings and past growth, which can leave less room for error if profit trends soften or sentiment cools.
See what the numbers say about this price in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chudenko for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading this, you might sense that sentiment around Chudenko is leaning constructive, yet the only view that matters is the one you build from the data in front of you. To see what the optimism is based on, take a moment to size up the company's 3 key rewards
Looking for more investment ideas beyond Chudenko?
Do not stop at a single stock when you can quickly scan for other opportunities that match your risk profile and income goals using structured screeners.
- Zero in on quality income potential by reviewing a focused set of higher yielding opportunities in the 29 dividend fortresses.
- Spot potential value setups early by running through the 73 high quality undiscovered gems before they land on everyone else's radar.
- Prioritize resilience by filtering companies through the 23 resilient stocks with low risk scores so you are not guessing about downside exposure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com