


Datang International Power Generation (SEHK:991) Backs Nuclear Capital And Loans, Is The Stock Still Cheap?
Datang International Power Generation (SEHK:991) has drawn fresh attention after its board approved additional capital for China Datang Corporation Nuclear Power Company Limited and signed off on special-purpose entrusted loans to certain enterprises.
Set against this board meeting, Datang International Power Generation’s 90-day share price return of 15.04% and year-to-date share price gain of 23.97% indicate that momentum has been building. The 3-year total shareholder return of 185.43% reflects a strong longer-term payoff profile.
Scan beyond Datang International Power Generation and pinpoint other utility and infrastructure plays showing fresh momentum and capital deployment shifts with our hand-picked 42 power grid technology and infrastructure stocks
Datang International Power Generation now couples a strong recent run with fresh capital commitments into nuclear projects and entrusted loans to related enterprises. Is it better to lean into that momentum now, or hold out for a cheaper entry as valuation stacks up next?
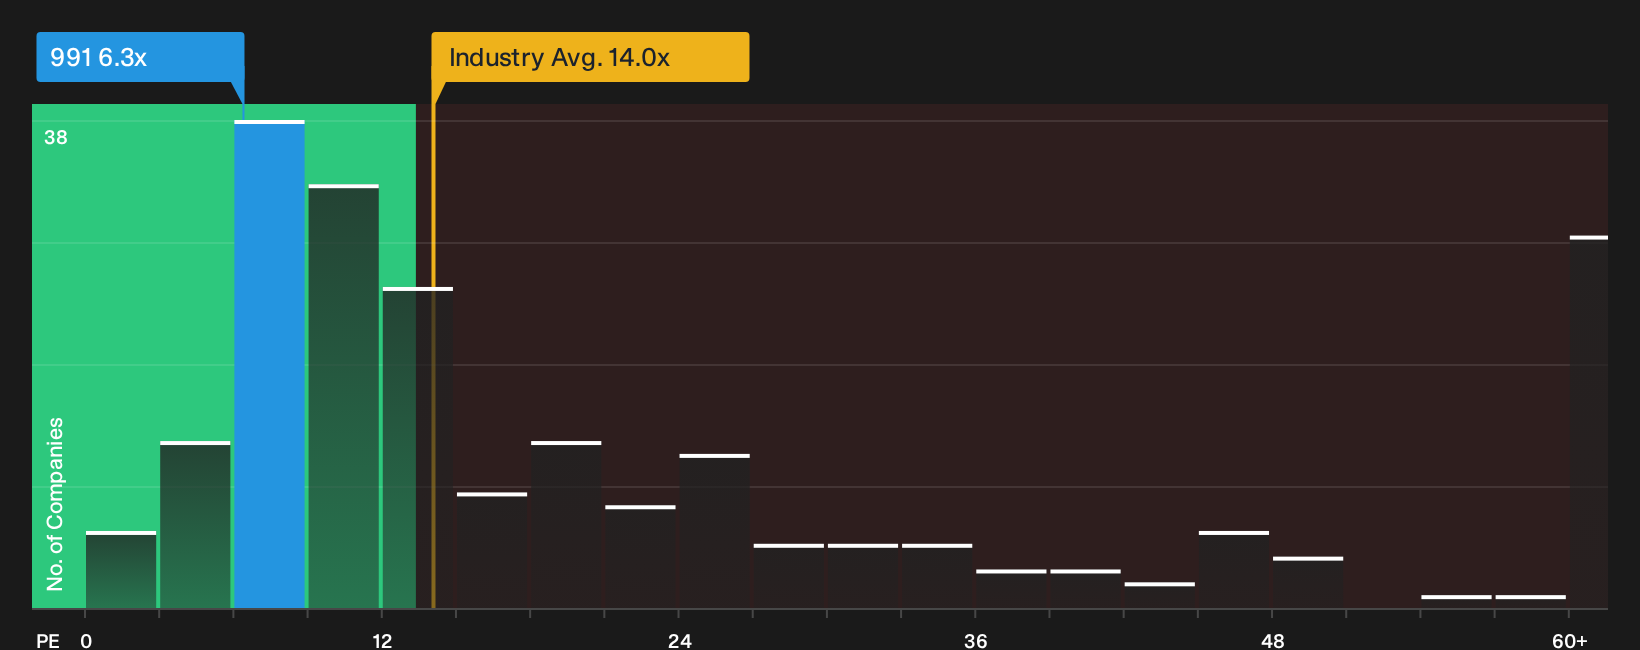
Preferred P/E of 6.3x: Is it justified for Datang International Power Generation?
Based on the latest checks, Datang International Power Generation trades on a P/E of 6.3x, which sits well below both its peer group and the broader Asian renewable energy space that cluster in the low double digits. At a last close of HK$2.72, that gap raises a clear question for you as an investor about whether earnings are being discounted more heavily than similar utilities.
The P/E ratio compares the share price with earnings per share, so a lower figure means you are paying less for each unit of profit. For a power producer like Datang International Power Generation, where cash generation and capital intensity matter, P/E can give a quick sense of how the market is weighing current profitability against the risks around future cash flows and leverage.
- Datang International Power Generation is flagged as good value at a P/E of 6.3x versus the Asian renewable energy industry average of 14x.
- The same 6.3x P/E also screens as cheaper than the peer average of 12.2x.
- Earnings growth over the past year of 50.9% has outpaced the renewable energy industry, which saw a decline of 14.8%.
- Return on equity of 10.4% is described as low compared with a 20% reference threshold.
- The SWS DCF model flags Datang International Power Generation as trading at a very large discount to an estimated future cash flow value of HK$37.93 per share, implying the stock is trading 92.8% below that internal fair value estimate.
That combination is unusual. A P/E that is less than half the industry average, paired with earnings growth that runs far ahead of sector figures and higher net profit margins than last year, suggests the market is applying a steep discount to 991 despite recent profitability metrics. At the same time, the low return on equity, concerns around debt coverage by operating cash flow, and reliance on higher risk external borrowing all provide reasons why some investors may be cautious and keep the valuation depressed.
Against that backdrop, the internal DCF work pointing to a fair value of HK$37.93 per share is far above the HK$2.72 share price and signals that, within that framework, the current level is treated as deeply undervalued relative to projected cash flows. That model rests on projected future cash generation and discounting those cash flows back to today at a required rate of return. This can produce a wide gap to market pricing when the inputs assume robust cash flow support over time for a business with heavy capital needs and earnings already in place across coal, hydro, wind, solar and nuclear assets.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of HK$37.93 (UNDERVALUED)
Still, heavy capital needs for coal and nuclear projects, along with debt and entrusted loan exposure, could quickly challenge the current valuation story for Datang International Power Generation.
Find out about the key risks to this Datang International Power Generation narrative.
Another View On Datang International Power Generation’s Valuation
Price targets tell a different story. Datang International Power Generation last closed at HK$2.72, while the latest analyst target sits at HK$3.57, about 32% higher. That gap suggests the market is pricing in more caution than at least one formal forecast implies. Which signal feels more credible to you right now?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Datang International Power Generation for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Datang International Power Generation’s valuation and risk profile create a real debate, so consider acting promptly, reviewing the underlying numbers yourself, and weighing the 2 key rewards and 2 important warning signs
Looking for more Datang International Power Generation style ideas?
If Datang International Power Generation has caught your attention, do not stop there. Broader idea hunting across sectors often reveals opportunities you did not expect.
- Target potential value plays by scanning companies that combine quality and attractive pricing with the 189 high quality undervalued stocks.
- Strengthen your focus on stability by checking out a list of solid balance sheet and fundamentals (204 results) that can better handle shocks and funding demands.
- Get ahead of the crowd by reviewing 614 high quality undiscovered gems before broader attention pushes them onto everyone else’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com