


Why 1 Analyst Is Cooling Their Stance on Red-Hot DELL Stock
Concerns over elevated hardware valuations and slowing margin expansion are prompting Wall Street analysts to take a more cautious stance on enterprise data infrastructure leaders. As high input costs and profit-taking test investor conviction, market watchers are scrutinizing whether powerful artificial intelligence (AI) server rallies can sustain upward momentum. Reflecting this cooler analyst sentiment, Barclays recently downgraded Dell Technologies (DELL) stock from “Overweight” to “Equal Weight.”
Headquartered in Round Rock, Texas, Dell is a global technology company specializing in personal computers, enterprise servers, data storage, networking, and IT infrastructure. With AI, cloud computing, and digital transformation driving corporate technology spending of late, Dell has been expanding its AI-optimized server business and strengthening its position in the rapidly growing data-center infrastructure market.
Dell Stock Stumbles
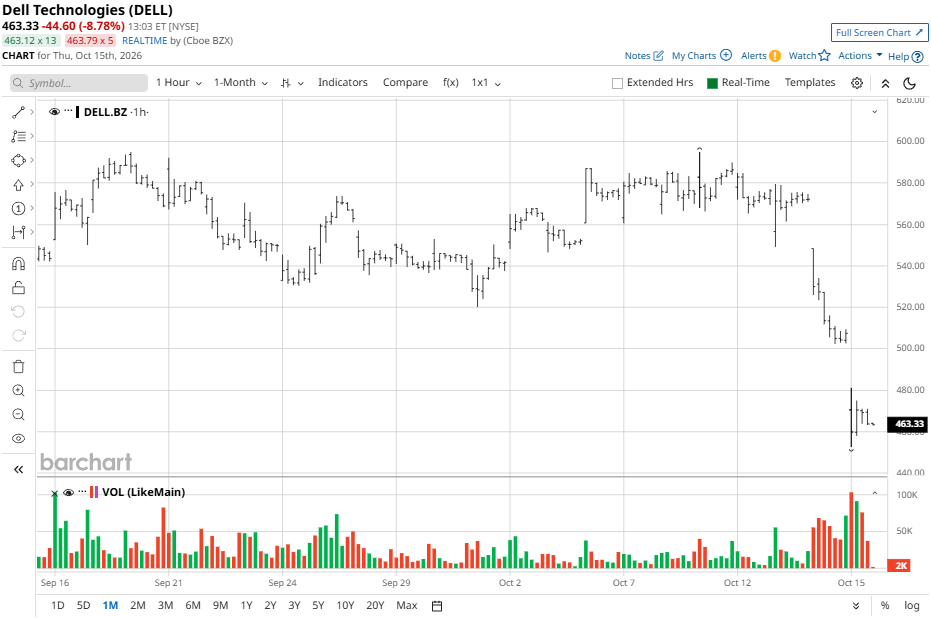
DELL stock has delivered exceptional gains in 2026, supported by rising AI infrastructure demand, strong quarterly earnings, and growing investor interest in data-center spending. However, the rally encountered significant turbulence on Oct. 14, when shares plunged more than 11% to close at $507.93 per share.
Despite the sharp selloff, the stock remains up by 259% year-to-date (YTD), highlighting its substantial outperformance over the broader market.
Dell's Results Outplay Estimates
Dell reported record second-quarter fiscal 2027 revenue of approximately $46.97 billion, representing a 58% year-over-year (YOY) increase. Adjusted EPS reached $7.04, significantly exceeding estimates of $4.97 and marking a substantial 203% improvement from $2.32 a year earlier. Revenue also surpassed analyst expectations of approximately $45 billion, demonstrating stronger-than-anticipated demand for AI infrastructure and enterprise technology solutions. The results reinforced Dell's position as a major beneficiary of growing investment in AI computing capacity.
The company's Infrastructure Solutions Group (ISG) led the quarterly performance, generating record revenue of $31.8 billion, up 89% YOY. AI-optimized server revenue doubled to $16.4 billion, while traditional servers and networking revenue surged 122% YOY to $10.5 billion. Storage revenue increased 26% YOY to $4.9 billion. Meanwhile, the Client Solutions Group (CSG) — which includes commercial PCs and consumer computers — recorded revenue of $15 billion, up 20% YOY. Dell generated $2.2 billion in operating cash flow and returned a record $4.3 billion to shareholders through dividends and share repurchases, reflecting strong cash generation alongside rapid business expansion.
Looking ahead, management raised its fiscal 2027 revenue forecast by $25 billion to $192 billion, implying 69% YOY growth. The company expects full-year GAAP diluted EPS of $24.37 and non-GAAP diluted EPS of $25.50. For Q3, management projects revenue of approximately $49 billion and non-GAAP diluted EPS of $6.50. Dell also reported a record $95 billion AI server backlog, supported by strong demand for AI-optimized infrastructure. Nevertheless, investors will want to monitor memory costs, operating margins, enterprise AI adoption, and valuation risks to assess whether Dell can sustain its growth momentum.
Barclays Downgrades DELL Stock
Dell shares declined on Oct. 14 after Barclays downgraded DELL stock to “Equal Weight” from “Overweight,” citing valuation concerns, rising memory costs, and uncertainty surrounding enterprise spending. Analyst Tim Long lowered his price target to $574 from $603 despite acknowledging the company's strong execution across enterprise technology markets.
Long noted that Dell's fiscal 2027 guidance points to more than 100% revenue growth in enterprise servers, alongside mid-teens growth in storage and CSG. However, Barclays believes much of this expansion reflects higher average selling prices driven by memory inflation rather than underlying demand growth. Long also warned that Dell's revenue growth could decelerate over the next two years as memory prices “normalize and potentially decline.”
The Barclays downgrade highlights growing investor concerns about Dell's AI server growth outlook, valuation, and long-term earnings sustainability.
Should You Buy DELL Stock?
Dell presents a compelling AI infrastructure growth opportunity, but investors should weigh its earnings potential against valuation risks and rising memory costs.
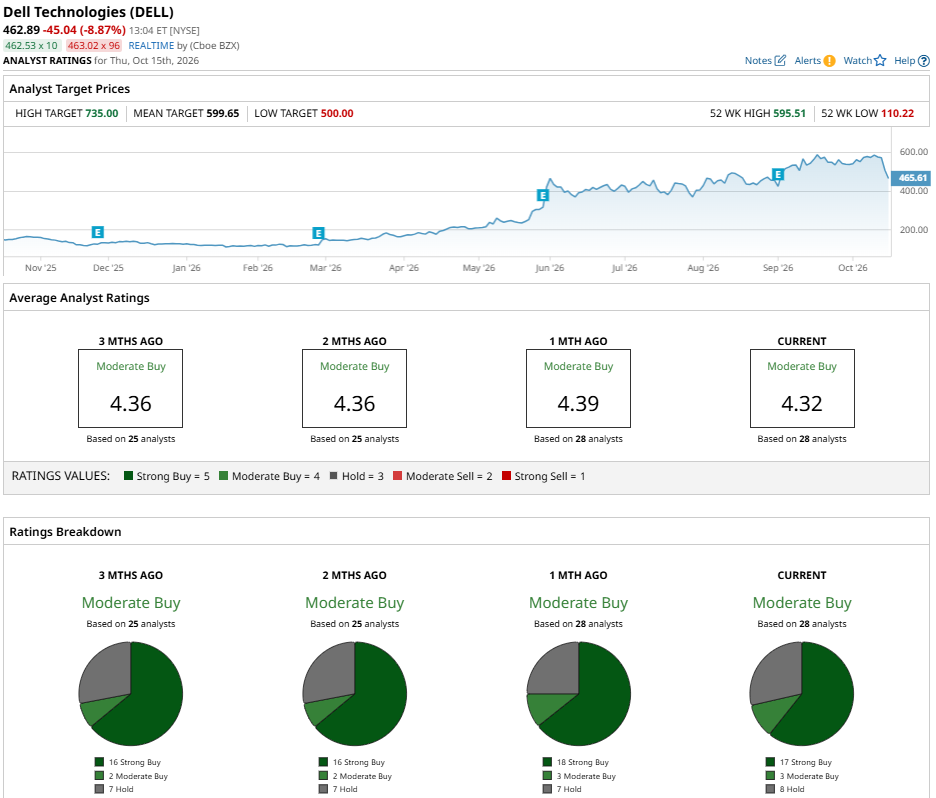
Nevertheless, DELL stock has a consensus “Moderate Buy” rating on Wall Street. Out of 28 analysts with coverage, 17 have a “Strong Buy” rating, three have a “Moderate Buy,” and eight analysts have a “Hold.” The mean price target of $599.65 implies potential upside of roughly 33% from current levels.
Investors should assess upcoming earnings, AI server demand, and profit margins before making a decision.
On the date of publication, Ruchi Gupta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.