


Is Hoshizaki (TSE:6465) Undervalued After Its Stock Split News?
Stock split puts Hoshizaki in focus
Hoshizaki (TSE:6465) has drawn fresh attention after announcing a 1-for-2 stock split scheduled for December 29, 2026. This move reshapes the share count and may influence trading liquidity.
Recent trading suggests interest is picking up around Hoshizaki, with the 1-day share price return of 1.57% and 7-day share price return of 3.34% adding to a 4.57% year-to-date share price gain. The 5-year total shareholder return of 23.31% points to steadier long-run compounding.
Surf 13 high quality undervalued stocks that, similar to Hoshizaki after its stock split news, combine established operations with the potential for sharper liquidity and valuation re-rating.Recent gains and the stock split headline put Hoshizaki firmly on the radar, but the real question now is whether the meaningful upside lies ahead or if most of the easy money already sits in the rear-view mirror.
Price-to-earnings of 19.5x: Is it justified for Hoshizaki?
On simple valuation terms, Hoshizaki trades on a P/E of 19.5x, while our DCF work flags the shares as trading at a 36.3% discount to an estimated cash flow value of ¥8,544.94 against a last close of ¥5,443. That mix of a modestly higher earnings multiple alongside a discounted DCF outcome gives you two very different signals to weigh.
The P/E ratio compares what investors pay today for each unit of current earnings. For an equipment maker like Hoshizaki, which reports revenue of ¥521,008 and net income of ¥38,501, that earnings yardstick can matter a lot because the business is already profitable and analysts expect earnings to grow 10% per year. A 19.5x multiple suggests buyers are willing to pay a reasonable premium for those profits without stretching into extreme territory.
Set against peers, the gap is clear. Hoshizaki trades on 19.5x earnings, while the Japan Machinery industry average sits at 13x, so the stock commands materially richer terms than sector counterparts. Compared to an estimated fair P/E of 17.2x, the current multiple also looks heavy, which is a level the market could move towards if enthusiasm cools or if earnings do not track forecasts.
Explore the SWS fair ratio for Hoshizaki.
Result: Price-to-earnings of 19.5x (OVERVALUED)
Still, any wobble in Hoshizaki’s earnings growth or a shift in kitchen equipment demand could quickly challenge today’s richer P/E and DCF optimism.
Find out about the key risks to this Hoshizaki narrative.
Another view on Hoshizaki’s value
The picture shifts once you look at Hoshizaki through our DCF model instead of just the P/E ratio. On that framework, the shares trade around ¥5,443 against an estimated future cash flow value of ¥8,544.94, which screens as undervalued rather than expensive.
Our DCF work leans heavily on long term cash generation and discount rates instead of headline multiples, so it tends to highlight opportunities where near term sentiment looks cautious. The question is whether those cash flow assumptions prove realistic once the stock split and earnings forecasts meet real world trading conditions.
Look into how the SWS DCF model arrives at its fair value.
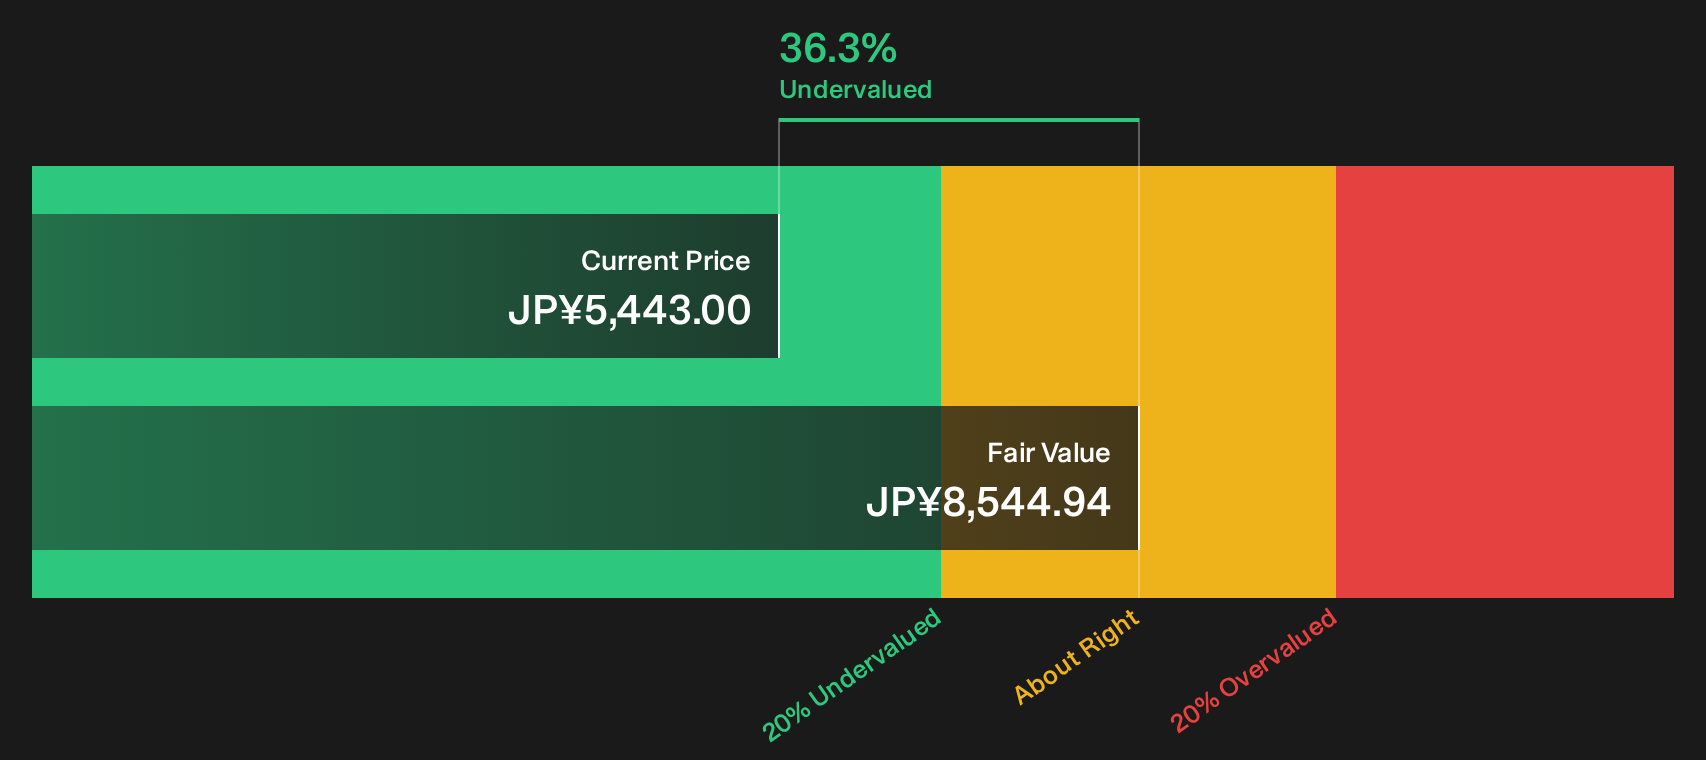
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hoshizaki for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this Hoshizaki story points to optimism, so do not just take the headline ratios at face value and move on. Put the assumptions under your own spotlight, then see how our breakdown of 4 key rewards can help clarify the picture.
Looking for more investment ideas beyond Hoshizaki?
If Hoshizaki has sharpened your interest, do not stop here. Broader idea hunting can help you spot opportunities you may otherwise miss.
- Target potential upside by scanning 73 high quality undiscovered gems that combine solid financial traits with lower market attention.
- Strengthen your downside protection by searching through the 23 resilient stocks with low risk scores that prioritise resilience when conditions change.
- Build a sturdier core for your portfolio with the list of solid balance sheet and fundamentals (22 results) that marry dependable finances with fundamental quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com