


Longfor Group Holdings (SEHK:960) Could Be 72% Below Fair Value After 9 Month Sales Update
Longfor Group Holdings (SEHK:960) just opened its books on the first nine months of 2026, detailing RMB23.14b in contracted sales and RMB20.44b in revenue from property operation and property service.
Investors watching Longfor Group Holdings have seen sharp swings, with a 1-day share price return of 6.21% after the announcement. However, the stock is still down 7.69% over 30 days and 42.28% year to date on a share price basis, while the 1-year total shareholder return has declined 51.07%. This points to fading longer term momentum despite the latest update on contracted sales and recurring service revenues.
Scan beyond Longfor Group Holdings and compare this move with a curated set of 189 high quality undervalued stocks that currently show stronger share price resilience and more balanced track records.
Longfor Group Holdings now trades at a steep discount to both intrinsic value estimates and analyst targets after this rebound. Is that a genuine margin of safety, or a warning that the market’s caution still has teeth?
Preferred Price-to-Sales of 0.4x: Is it justified?
On Simply Wall St’s numbers, Longfor Group Holdings trades on a P/S of 0.4x. This lines up with a share price of HK$5.05 that currently sits well below both its internal fair value estimate and analyst targets, suggesting the market is pricing in a lot of caution compared with peers.
The P/S ratio compares what investors pay for each unit of reported revenue. For a property developer and operator like Longfor Group Holdings, where earnings are currently in the red and profits can swing with project timing, focusing on sales rather than net income gives a cleaner read on how the market values its existing top line.
That 0.4x multiple is materially lower than the Hong Kong real estate industry average of 0.7x and well below the peer average of 1.3x. It also sits under the estimated fair P/S of 0.5x. Taken together, the gap suggests investors are assigning a clear discount to Longfor’s revenue base compared with both the wider sector and what the SWS fair ratio implies the multiple could move toward if sentiment or fundamentals were to improve.
Explore the SWS fair ratio for Longfor Group Holdings.
Result: Price-to-sales of 0.4x (UNDERVALUED)
Still, Longfor Group Holdings carries clear risks if contracted sales soften further or if losses deepen relative to its HK$78.35b revenue base.
Find out about the key risks to this Longfor Group Holdings narrative.
Another View: Longfor Group Holdings Through The SWS DCF Lens
The P/S of 0.4x already points to caution around Longfor Group Holdings, yet the SWS DCF model paints an even starker contrast. On those cash flow assumptions, our DCF model points to a fair value of HK$17.97 per share versus a market price around HK$5.05, implying the stock screens as deeply undervalued. If both models flag a discount this large, the key question is whether the market is overreacting to near term risks or correctly bracing for a tougher road ahead.
Look into how the SWS DCF model arrives at its fair value.
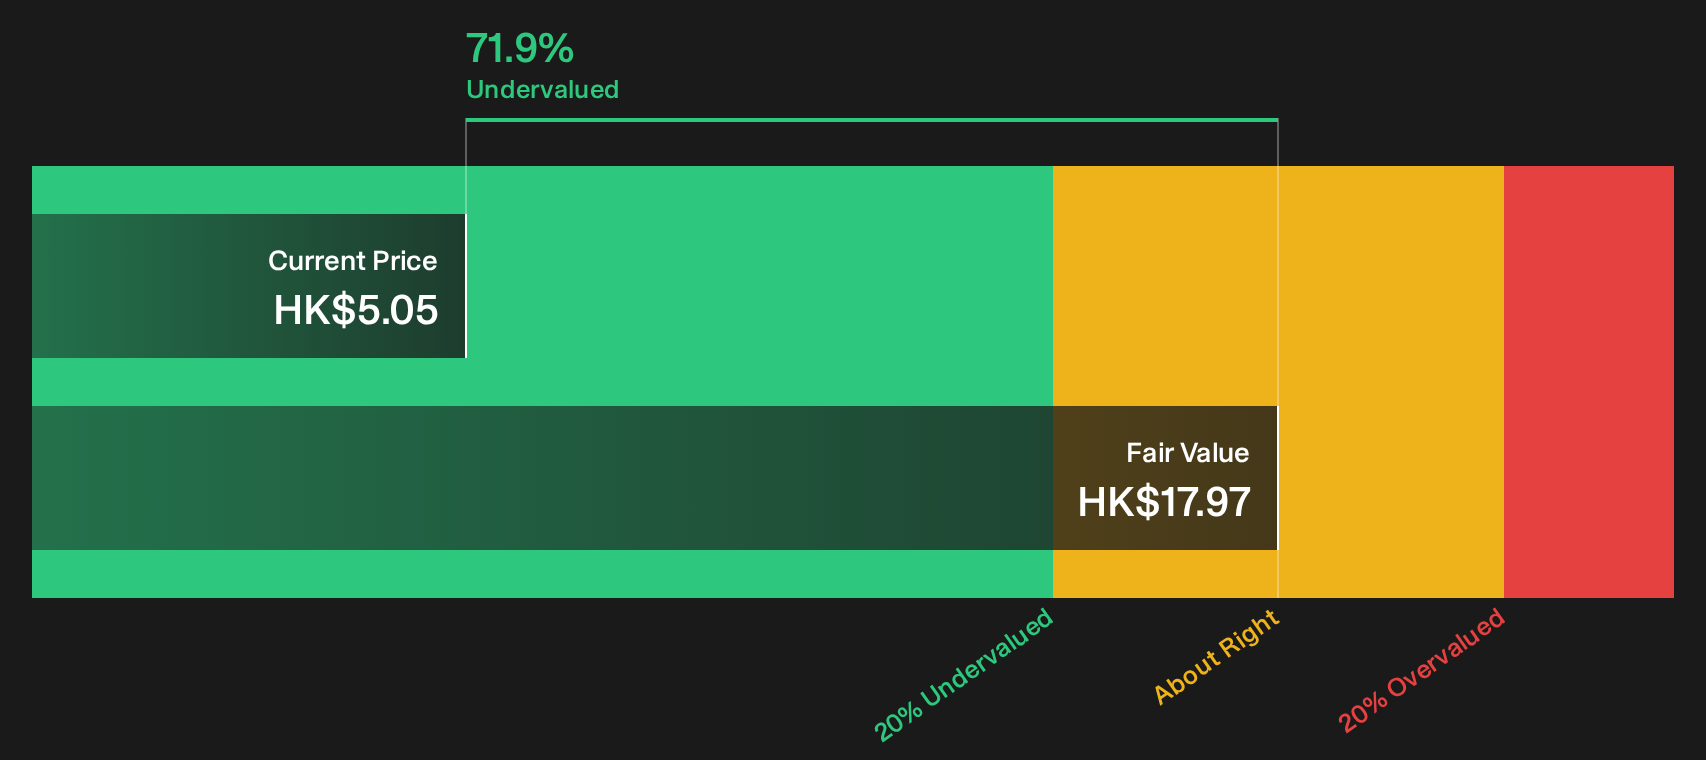
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Longfor Group Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Longfor Group Holdings can feel uncomfortable in real time, so move quickly from headlines to hard numbers and shape your own view using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Longfor Group Holdings?
Do not stop at one setup. Broaden your watchlist with focused stock ideas filtered by quality, value and balance sheet strength using the Simply Wall St screener.
- Target potential mispricing by reviewing a curated set of 189 high quality undervalued stocks that combine stronger financial foundations with more resilient share price histories.
- Strengthen capital preservation by scanning through 234 resilient stocks with low risk scores where the emphasis is on resilient balance sheets and steadier risk profiles.
- Unearth future contenders by checking out 614 high quality undiscovered gems that pair solid fundamentals with lower current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com