


Is Upstart Holdings (UPST) Undervalued After Adding Credit Union Of Denver?
Upstart Holdings (UPST) just added Credit Union of Denver as a lending partner, a move that widens its digital personal loan reach and suggests the potential for more origination volume flowing through the platform.
For context, Upstart Holdings shares trade at US$23.56 and the stock has had a weak run, with the 30-day share price return down 5.76% and the year-to-date share price return down 48.60%. This has contributed to a 1-year total shareholder return decline of 49.33%, which points to fading momentum even as new partnerships like Credit Union of Denver hint at shifting expectations around future origination and risk.
Scan AI-driven lenders with similar partnership stories and see how Upstart Holdings compares across 39 profitable AI stocks that aren't just burning cash in terms of business model, risk profile, and recent share price momentum.
Upstart Holdings is signing fresh partners like Credit Union of Denver while the share price has fallen hard this year. That mix of product traction and weak sentiment creates a clear tension: Is the business strong but the stock still expensive, or has the market already priced in the risks?
Most Popular Narrative: 39% Undervalued
Upstart Holdings last closed at $23.56, while the most followed narrative anchors fair value at $38.38. The gap between price and modeled worth is wide and forces you to weigh funding risk against strong growth assumptions.
Upstart's HELOC product growth, driven by conversion improvements, cross-selling, and state expansion, positions it well for future revenue growth and margins with the potential to leverage its strong relationships with banks and credit unions for cost-effective funding.
Increased automation and personalization in servicing operations have reduced costs and improved borrower outcomes, which will likely improve net margins through operational efficiencies and lower default rates.
See why 143 investors see Upstart Holdings as 39% undervalued.
Result: Fair Value of $38.38 (UNDERVALUED)
Still, if Upstart Holdings faces renewed funding constraints or a spike in default rates, the bullish narrative around its AI lending model could unwind quickly.
Find out about the key risks to this Upstart Holdings narrative.
Another View: Upstart Holdings Through The P/E Lens
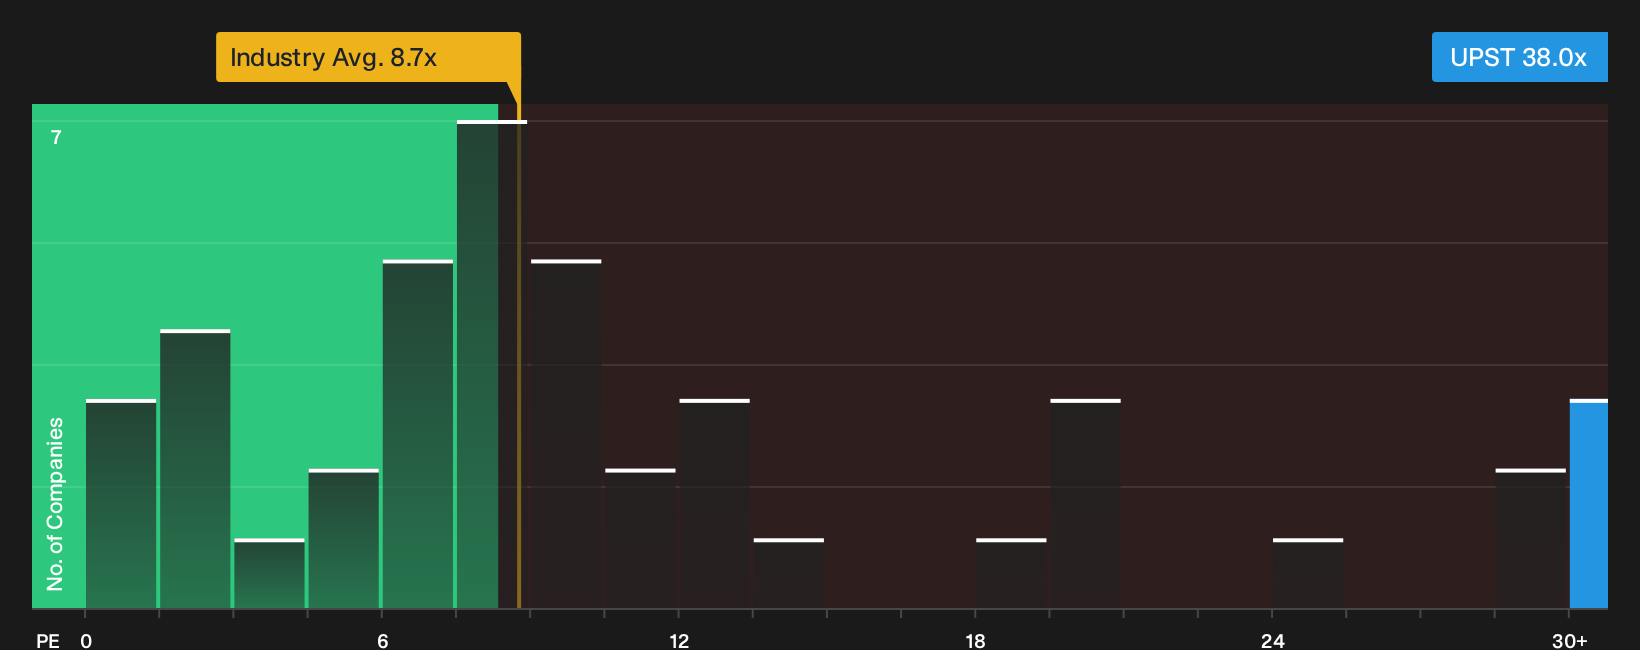
The story looks very different once you step away from fair value models and just look at what Upstart Holdings trades for today. The stock changes hands at a P/E of 38x. That is well above the Consumer Finance industry on 8.7x and above its own fair ratio of 34.9x.
This gap means anyone buying purely on earnings today is paying a richer price than both peers and the fair ratio suggest, and relying on strong future execution to close that distance instead of the multiple compressing. The key question is whether you are comfortable underwriting that kind of valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Upstart Holdings can feel confusing. Consider reviewing the underlying numbers yourself and carefully assess both the potential upside and the concerns around the business by weighing 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Upstart Holdings?
If Upstart Holdings has you thinking harder about risk, valuation, and momentum, the next smart move is widening your watchlist with focused stock ideas.
- Hunt for mispriced quality by scanning companies that show strong fundamentals at appealing valuations through the 33 high quality undervalued stocks.
- Prioritise resilience and sleep-better-at-night positions by filtering for businesses with sturdier finances using the 32 resilient stocks with low risk scores.
- Target future leaders early by reviewing fundamentally sound up-and-comers in the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com