


Global Payments’ Quarterly Earnings Preview: What You Need to Know
Georgia-based Global Payments Inc. (GPN) is a leading payments technology and software solutions provider that enables businesses to accept, process, and manage electronic payments across physical, online, and mobile channels. The company operates globally, serving millions of merchants in more than 100 countries and has a market capitalization of $22.1 billion.
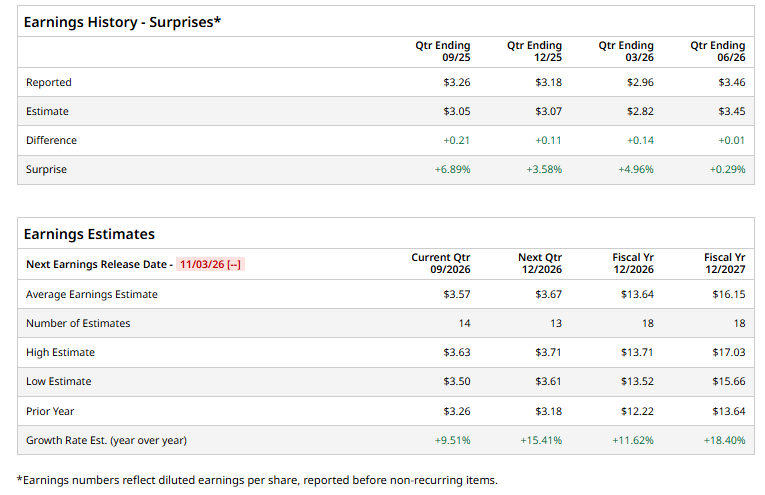
The company is expected to release its Q3 2026 earnings soon. Ahead of this event, analysts anticipate the company will generate earnings of $3.57 per share, up 9.5% from $3.26 per share reported in the same quarter last year. The company has surpassed the Street’s bottom-line estimates in each of the past four quarters.
For fiscal 2026, analysts expect the company to report an EPS of $13.64, indicating a 11.6% increase from $12.22 reported in fiscal 2025. Moreover, its EPS is expected to rise 18.4% year over year to $16.15 in fiscal 2027.
GPN stock has surged marginally over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 15.5% rise and the State Street Technology Select Sector SPDR ETF’s (XLK) 29% return during the same time frame.
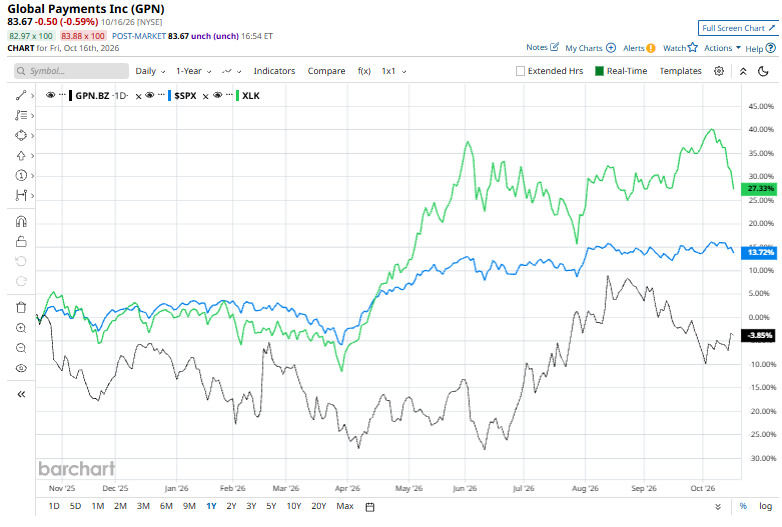
Global Payments has lagged behind the broader market over the past year due to slowing organic growth, concerns about integrating its Worldpay acquisition, and persistent weakness in fintech valuations. Investors remain cautious about elevated debt and relatively low returns on invested capital, while intensifying competition and pricing pressure weigh on growth prospects. The company’s 2026 revenue outlook has also been tempered by prolonged weakness in its travel-related business amid Middle East disruptions, further pressuring sentiment.
Analysts’ consensus opinion on the stock is somewhat optimistic, with a “Moderate Buy” rating overall. Among the 36 analysts covering the stock, 15 recommend a “Strong Buy,” 19 suggest a “Hold,” and the remaining two suggest a “Strong Sell.” GPN’s average analyst price target is $103.41, indicating an upside of 23.6% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.