


AGC (TSE:5201) Just Gave Investors Something To Think About
AGC (TSE:5201) drew fresh attention after recent trading left the share price at ¥5,551, with the stock down over the past week, month, and past 3 months despite positive annual revenue and net income growth.
Over the past year, AGC has delivered a 19.95% total shareholder return, even as recent momentum has faded with a 90 day share price return of 9.52%, and shorter term moves pointing to investors reassessing both growth potential and risk around the current ¥5,551 level.
Scan how AGC compares with other companies investors are watching by reviewing the 13 high quality undervalued stocks that pair solid fundamentals with potential mispricing.
Bulls point to AGC’s revenue and net income growth alongside a 1 year return near 20%. Bears focus on the recent price pullback. Which side does the valuation math support next?
Most Popular Narrative: 15% Undervalued
AGC’s most followed storyline pegs fair value at ¥6,516, which sits above the recent ¥5,551 close, so the narrative leans toward upside that the market has not fully reflected in the price.
Structural reforms and the strategic exit from loss-making U.S. biopharmaceutical operations will eliminate a major drag on profits, while refocusing Life Science on high-growth, single-use bag (SUB) technologies is expected to restore segment profitability and drive new growth from 2026 onward, directly benefitting net income.
See why 4 investors see AGC as 15% undervalued.
The fair value estimate of ¥6,516 is built on revenue growth assumptions of roughly 3.7% and profit margins rising from 4.2% to 4.7%, all discounted at 7.79%. Readers can judge whether those inputs feel reasonable against AGC’s recent earnings rebound and still modest 5.8% return on equity.
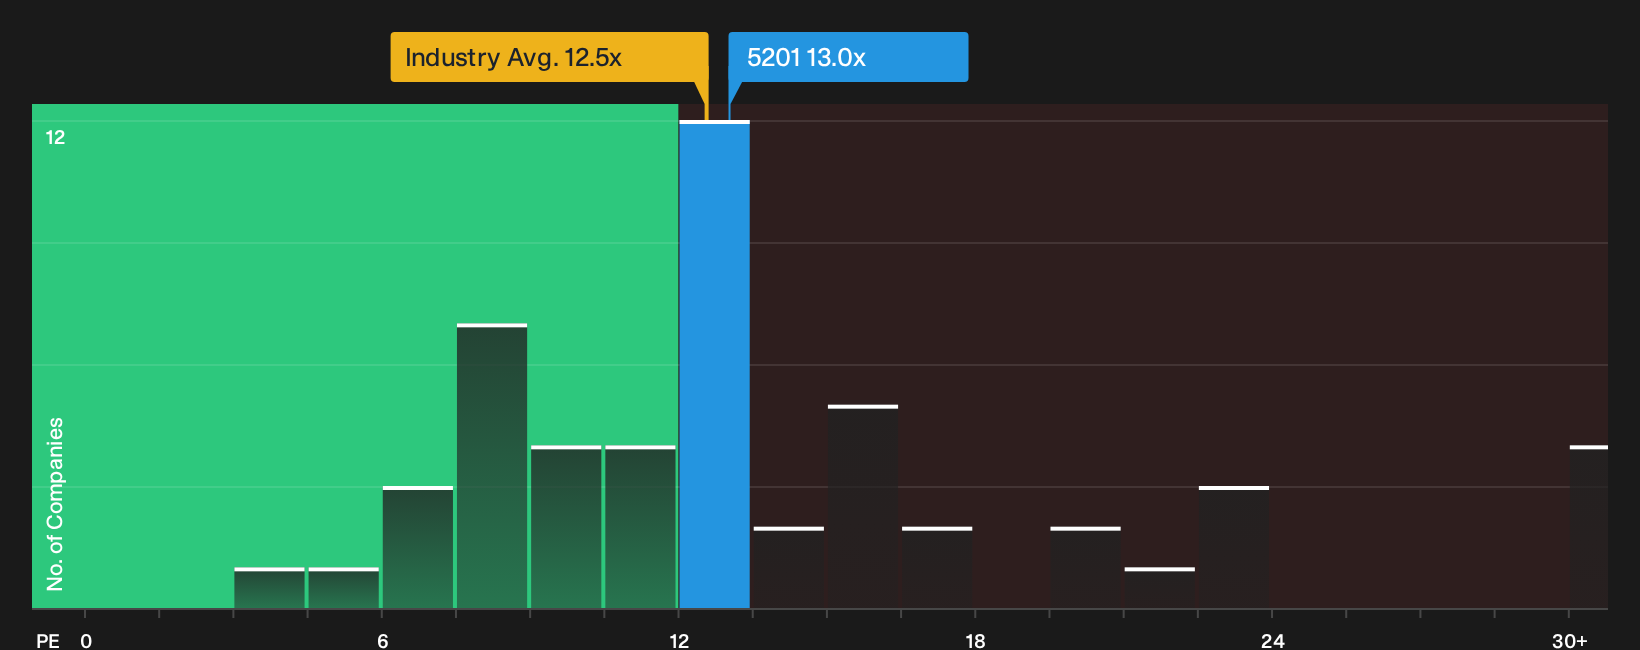
That same narrative leans on AGC’s diversified operations in glass, chemicals, electronics, automotive, and life science, with analysts expecting earnings to reach ¥113.3b and a future P/E of 15.3x. This sits above both the current 13x multiple and the JP Building industry’s 12.5x, implying the story requires belief in improved profitability rather than just multiple expansion from today’s level.
Result: Fair Value of ¥6,516 (UNDERVALUED)
Still, weak demand and pricing pressure in Asia for architectural glass and PVC, along with ongoing Life Science losses, could easily derail that 15% undervaluation story.
Find out about the key risks to this AGC narrative.
Another View: AGC Through The P/E Lens
AGC looks inexpensive against its own fair ratio, with a P/E of 13x compared with an estimated fair ratio of 18.7x, yet only slightly pricier than the JP Building sector on 12.5x. Peers near 36x put that gap in sharp relief. Is this a margin of safety or a value trap in slow growth?
To unpack what this valuation gap could mean in practice for risk and upside, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed views on AGC so far. If you want to move quicker than the crowd, explore the full picture of both concern and optimism through the 3 key rewards and 1 important warning sign.
Looking For More Ideas Beyond AGC?
Do not stop your research with AGC alone, because a broader watchlist can reveal opportunities that better match your risk comfort and return goals.
- Target potential mispricings by scanning financially sound companies that still trade at a discount using the 13 high quality undervalued stocks.
- Strengthen your defence by reviewing a list of solid balance sheet and fundamentals (22 results) that can help steady your portfolio when conditions turn volatile.
- Hunt for future leaders by checking a curated pool of 73 high quality undiscovered gems before the wider market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com