


Did Undervaluation Claims Just Shift Restaurant Brands International's (QSR) Investment Narrative?
- Recent analysis of Restaurant Brands International points to a partnership structure built around recurring franchise royalties and capital light cash generation, with discounted cash flow work suggesting the current unit price sits below estimated intrinsic value.
- The focus on royalty streams over heavy restaurant ownership means Restaurant Brands International can pursue growth while relying less on upfront capital, which shapes how investors think about its long term cash profile.
- We will now look at how Restaurant Brands International's investment narrative is affected by fresh DCF based claims of undervaluation.
Compare Restaurant Brands International's royalty driven model with a curated set of other potential value ideas by scanning 33 high quality undervalued stocks that may also be trading below estimated intrinsic value.
Restaurant Brands International Investment Narrative Recap
To own Restaurant Brands International, you need to believe the franchise engine keeps throwing off dependable royalties while Burger King U.S. and Tim Hortons sustain customer interest. The latest DCF work pointing to undervaluation does not change the operational playbook. It simply puts more focus on whether current cash generation and capital returns are durable.
Near term, the biggest swing factor is execution at Burger King U.S. and Popeyes, where past traffic softness and high beef costs still matter. The key risk is that modest forecast revenue growth and margin pressure persist, which could leave sentiment muted even if the DCF gap appears attractive on paper.
The fresh DCF based claim that Restaurant Brands International trades below estimated future cash flow value is the most relevant update here. That conclusion leans on earnings forecasts of about 9.5% annual profit growth, a P/E of 18.7x versus higher industry and peer averages, and an internal fair value P/E of 22.4x.
For catalysts, that valuation angle only really works if the franchise heavy model keeps converting system wide sales into cash and supporting a roughly 3.48% dividend plus the existing buyback authorization through 2027. Debt coverage by operating cash flow is a watchpoint, so balance sheet progress and consistent free cash flow matter just as much as headline growth.
Restaurant Brands International's narrative projects US$10.1b in revenue and US$2.2b in earnings by 2029. This projection assumes 1.5% yearly revenue growth and an earnings increase of roughly US$800m from US$1.4b today.
Uncover why Restaurant Brands International's fair value indicates a 15% potential upside to its current price that may not last much longer.
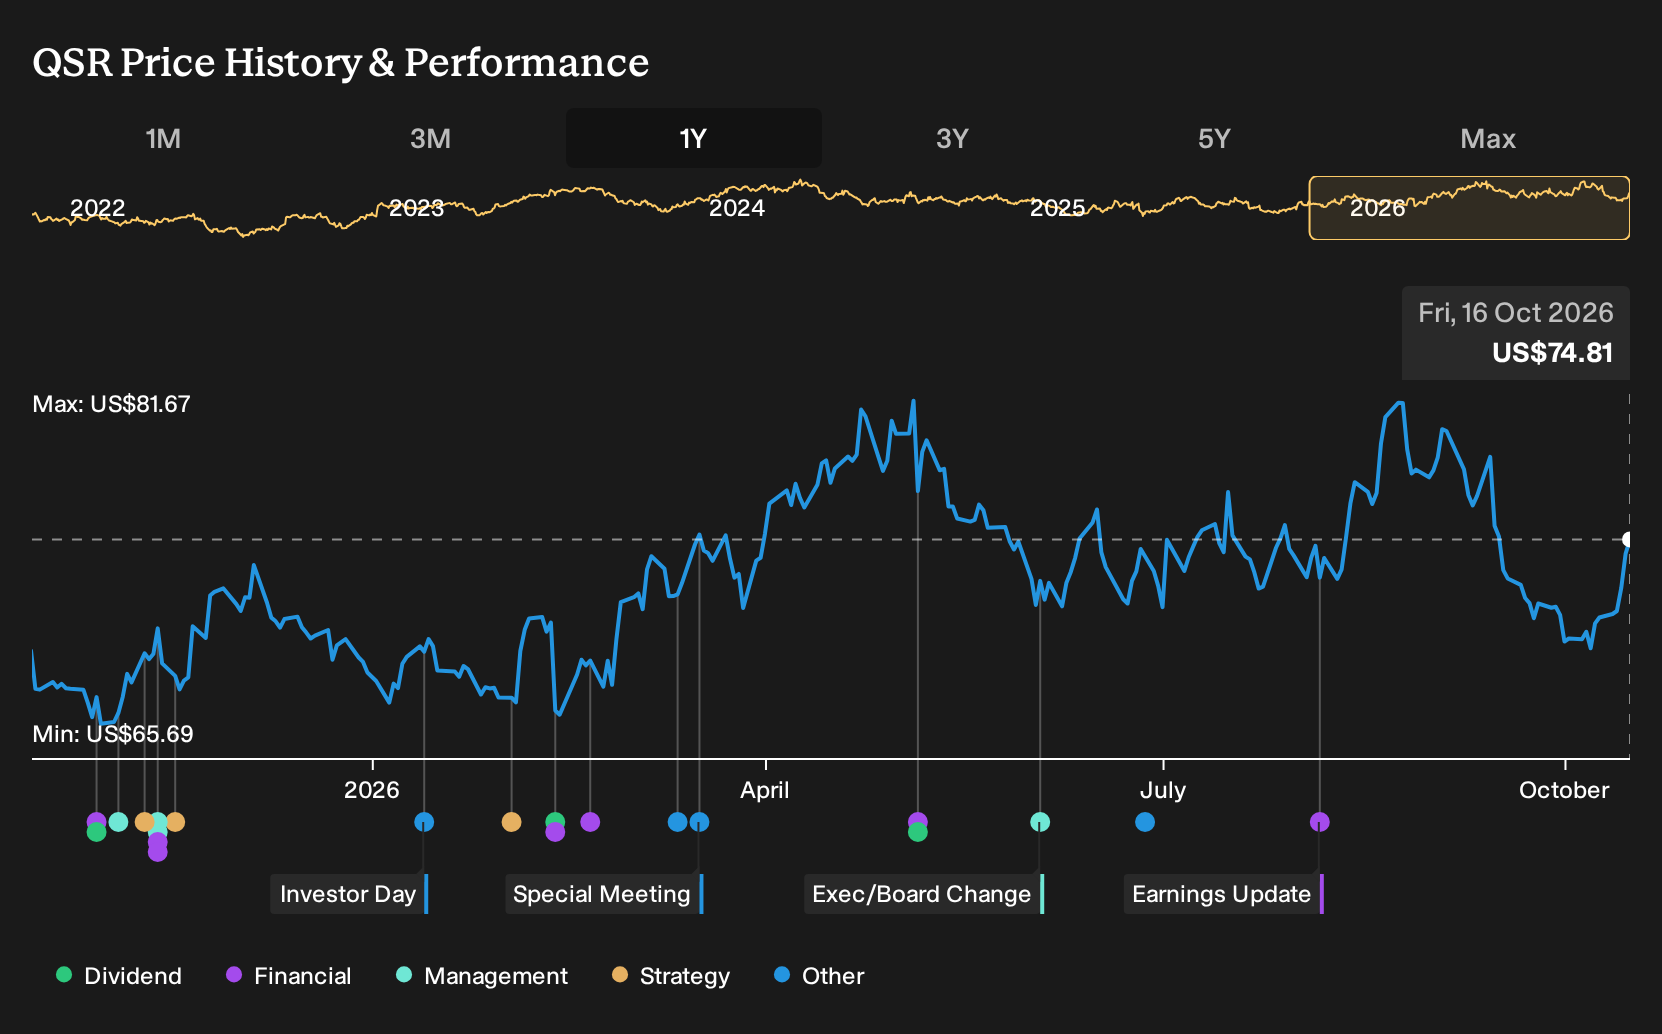
Exploring Other Perspectives
The Simply Wall St Community offers three fair value views for Restaurant Brands International, clustering between US$80.35 and US$86.04 per unit, which already suggests tight but varied expectations. Set those side by side with risks around Burger King U.S. beef costs and Popeyes traffic, and you see how sharply opinions can diverge. Use those contrasting readings as a prompt to explore multiple viewpoints rather than rely on a single model.
Explore 2 other Restaurant Brands International fair value estimates, including one that suggests as much as 15% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Restaurant Brands International research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Restaurant Brands International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Restaurant Brands International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Restaurant Brands International?
Once you have a working view on Restaurant Brands International, it can help to cross check that thesis against opportunities elsewhere. Use the Simply Wall St screener to scan for different types of setups that fit your risk tolerance and income goals.
- If you care about stability first and upside second, start by reviewing 32 resilient stocks with low risk scores that score well on resilience and downside protection.
- If income is the priority, scan for 8 dividend fortresses that offer higher yields with supporting fundamentals to back up those payouts.
- If you want to hunt for potential mispricings, shortlist 20 high quality undiscovered gems with strong underlying metrics that the broader market may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com