


Compass (COMP) Stock Dropped, What Is Driving Attention Now?
Compass (COMP) has been moving on two fronts. Falling bond yields are feeding into lower mortgage rates and renewed housing enthusiasm, and the company’s high profile antitrust fight over listing rules is sharpening attention on its model.
Recent trading has been choppy for Compass. The share price is down about 22% over the past 90 days and about 9% over the last month, even though the 1 year total shareholder return is about 25% and the 3 year total shareholder return is more than 3x.
Short term weakness around the current US$9.13 level has come as investors weigh falling bond yields and lower mortgage rates against fresh legal headlines and a new securities class action linked to the Anywhere merger.
On top of that, Compass is in the middle of a high profile antitrust dispute with California Regional Multiple Listing Service over listing rules. At the same time, the boardroom is reshaping with Charles Phillips stepping down and Sissie Hsiao joining. Those shifts are keeping perceptions of both growth potential and legal risk in flux.
Scan how Compass compares with housing peers by reviewing a hand picked list of list of solid balance sheet and fundamentals (25 results) built to weather legal and rate driven volatility.
For Compass, the drop back toward US$9 has arrived just as revenue and net income growth look healthier and legal headlines get louder. Is this slide about business reality, or is it a sharp swing in sentiment as housing enthusiasm cools?
Most Popular Narrative: 39% Undervalued
Compass is trading at $9.13, while the most followed narrative pegs fair value at about $14.92. This frames the current pullback as a potential valuation gap rather than just legal noise.
Rapid adoption and continuous improvement of Compass's AI-powered, end-to-end technology platform is increasing agent productivity, driving higher transaction volumes, improving retention, and is expected to widen margins as AI-driven process efficiencies scale throughout the organization, positively impacting revenue, EBITDA, and net margins.
See why 16 investors see Compass as 39% undervalued.
Result: Fair Value of $14.92 (UNDERVALUED)
Still, the Compass thesis starts to wobble if commission focused revenue faces pressure from regulatory changes, or if ongoing antitrust and class action cases reshape brokerage economics.
Find out about the key risks to this Compass narrative.
Another View: What Compass’s P/E Is Telling You
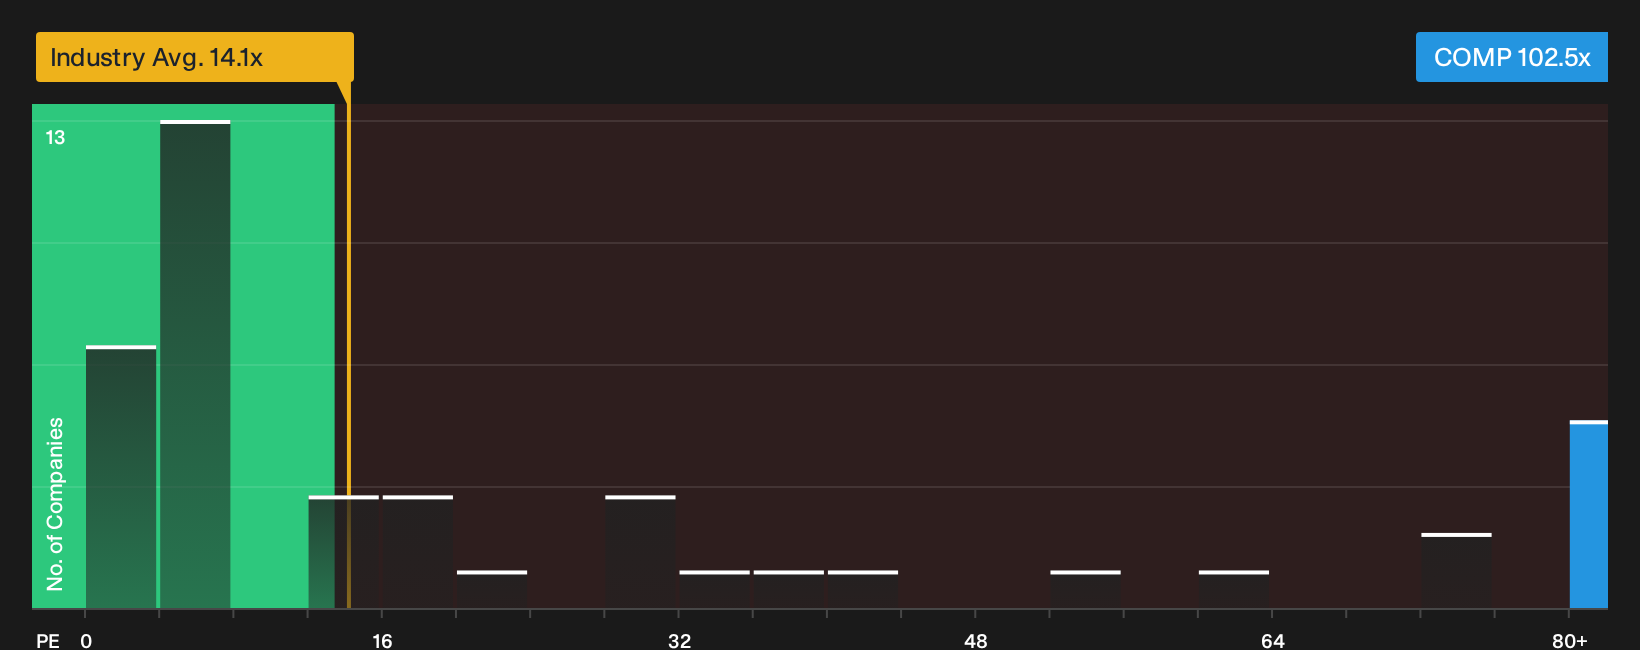
That $14.92 fair value narrative leans heavily on long term earnings growth. Zoom out to the current multiples and the story feels very different. At a P/E of 102.5x, Compass trades far above the US Real Estate industry at 14.1x, its peer group at 84x, and even its own fair ratio estimate of 45.3x.
This kind of gap points to valuation risk if expectations cool or litigation and commission pressure bite harder than bulls expect. It also raises a simple question for you as an investor: Is the current price rewarding Compass’s progress, or pre paying too much for what has not happened yet?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Debate around Compass has plenty of fuel, with legal risks on one side and clear upside arguments on the other. Move quickly, review the numbers yourself, then weigh the 3 key rewards and 3 important warning signs.
Looking for more Compass investment ideas?
If Compass has your attention, do not stop here. Broaden your watchlist now or you risk missing other high quality opportunities lining up today.
- Target resilient potential by scanning companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality with the 33 high quality undervalued stocks that filters for robust fundamentals at prices that may not fully reflect them.
- Stack income opportunities by checking out the 8 dividend fortresses that focuses on yields above 5% with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com