


Oil Stocks Rising With Iran Risk and Higher Crude Prices
Oil markets have been jolted by fresh Iran, U.S. and Israel conflict risk, attacks near key shipping lanes and crude benchmarks trading above $100, and that kind of stress test often reshuffles which integrated energy stocks look resilient and which look fragile. For investors, moments like this can quietly reset the odds. This article explains how these shocks connect to three Global Integrated Oil & Gas Producers that appear positively exposed to the current headlines and why their stories now merit closer examination.
These three integrated energy stocks are just a starter set, and the full screen surfaced 25 more companies that share similarly compelling narratives but fall outside the scope of this article. To see the wider field and identify which ones best fit your own thesis, head straight to the Global Integrated Oil & Gas Producers screener.
Tullow Oil (LSE:TLW)
Tullow Oil plugs directly into the Global Integrated Oil & Gas Producers theme as a London headquartered upstream developer that gives you pure exposure to crude-linked production, with about $968 million of business revenue from Ghana, smaller contributions elsewhere, and a market value around £179 million.
"Tullow has secured a memorandum of understanding to extend Ghana production licenses to 2040 and gained the right to drill up to 20 additional Jubilee wells. This supports a material uplift in reserves and production capacity, with a likely positive impact on long-term revenues and earnings."
What really matters now is how one less visible pressure on cash generation and flexibility resolves against that higher volume potential.
If that trade off is what you are really trying to size, the full narrative for Tullow Oil maps how reservoir upside, leverage and execution risk could be decoupling right now.

SM Energy (SM)
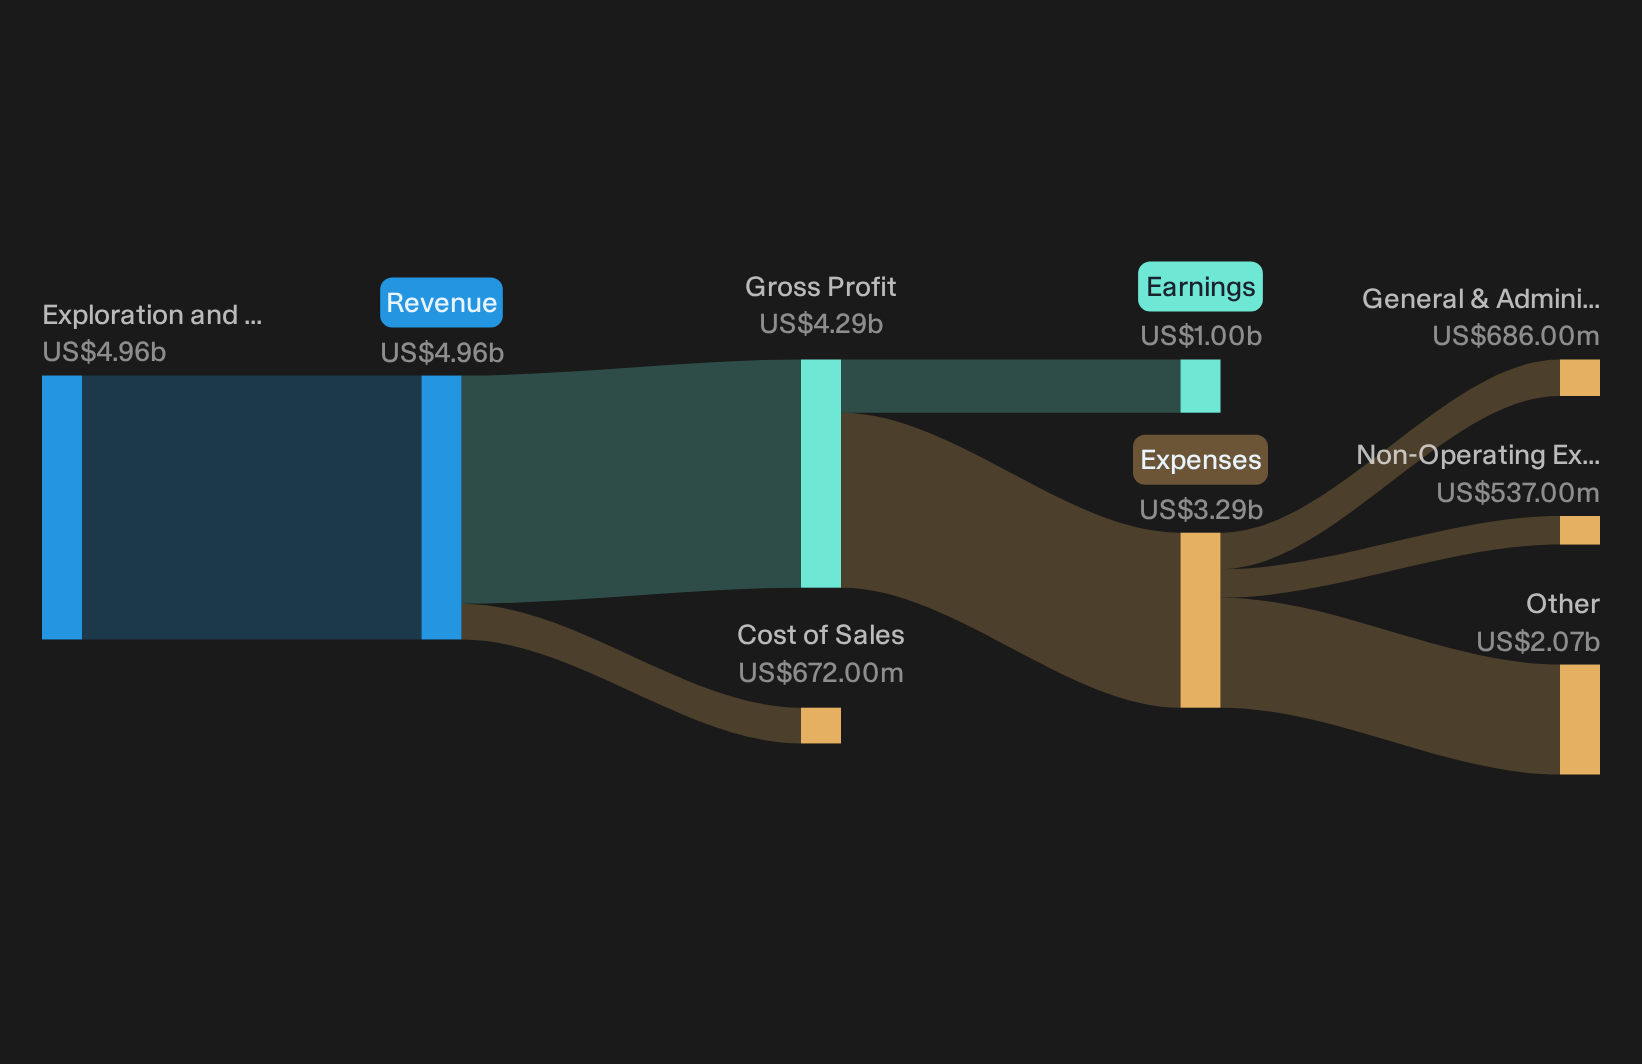
SM Energy plugs into the Global Integrated Oil & Gas Producers theme as a large U.S. oil and gas producer, generating about US$5.0b from its exploration and production activities and carrying a market value close to US$9.4b.
SM Energy gives you pure play U.S. volumes inside a large cap filter that prizes scale, liquidity and balance sheet thresholds. It is that combination that makes the next part of its story worth paying attention to.
"Merger driven scale and the actioned portion of the US$375 million run rate synergy target, with an estimated US$1.8b present value and lower recurring G&A guidance, points to a structurally lower cost base for SM Energy that can support higher net margins and earnings over time."
What happens if a single assumption in that cost and capital return plan bends under pressure from commodity prices or the debt stack?
If that pressure point is what keeps catching your eye, the full narrative for SM Energy shows where SM Energy’s synergy math could be accelerating or quietly stalling.
Mach Natural Resources (MNR)
Mach Natural Resources brings pure upstream exposure to the Global Integrated Oil & Gas Producers theme as an Oklahoma based driller and acquirer of oil, gas and NGL reserves across key U.S. basins, generating about $1.3b from exploration and production and carrying roughly $1.8b in market value.
Mach Natural Resources provides theme pure exposure to U.S. hydrocarbons at scale, with operations anchored in prolific basins and a model built around buying and developing producing assets. This is where today’s geopolitically charged oil tape is focusing investor attention.
"Anticipated substantial growth in U.S. natural gas demand driven by expanding LNG export capacity, data center build-out, and power generation needs positions Mach's growing, flexible gas production portfolio, particularly low-cost, high-rate assets in the San Juan and deep Anadarko Basins, to benefit from improved long-term pricing and increased revenue as demand accelerates through 2026 and beyond."
What matters for Mach Natural Resources now is how one quiet variable in that growth path bends future cash generation and distribution maths.
That quiet variable is exactly what the full narrative for Mach Natural Resources unpacks, showing where Mach Natural Resources’ gas optionality could be accelerating or quietly capped by reinvestment and payout choices.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes gain momentum while slow movers get caught holding stocks that already flew. Scan these under the radar lists while it matters and get in early.
- Spot cash rich companies that hold up when conditions turn. Then narrow that universe using the curated list of solid balance sheet and fundamentals (9 results) before stronger balance sheets are fully priced.
- Ride structural shifts in energy and infrastructure by targeting curated 42 power grid technology and infrastructure stocks while many investors still overlook grid technology and transmission upgrades.
- Target future facing automation themes by filtering through hand picked 91 robotics and automation stocks before robotics and factory AI adoption move from niche story to crowded trade.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com