


What Coca Cola FEMSA Stock Upgrade Means For Shareholders
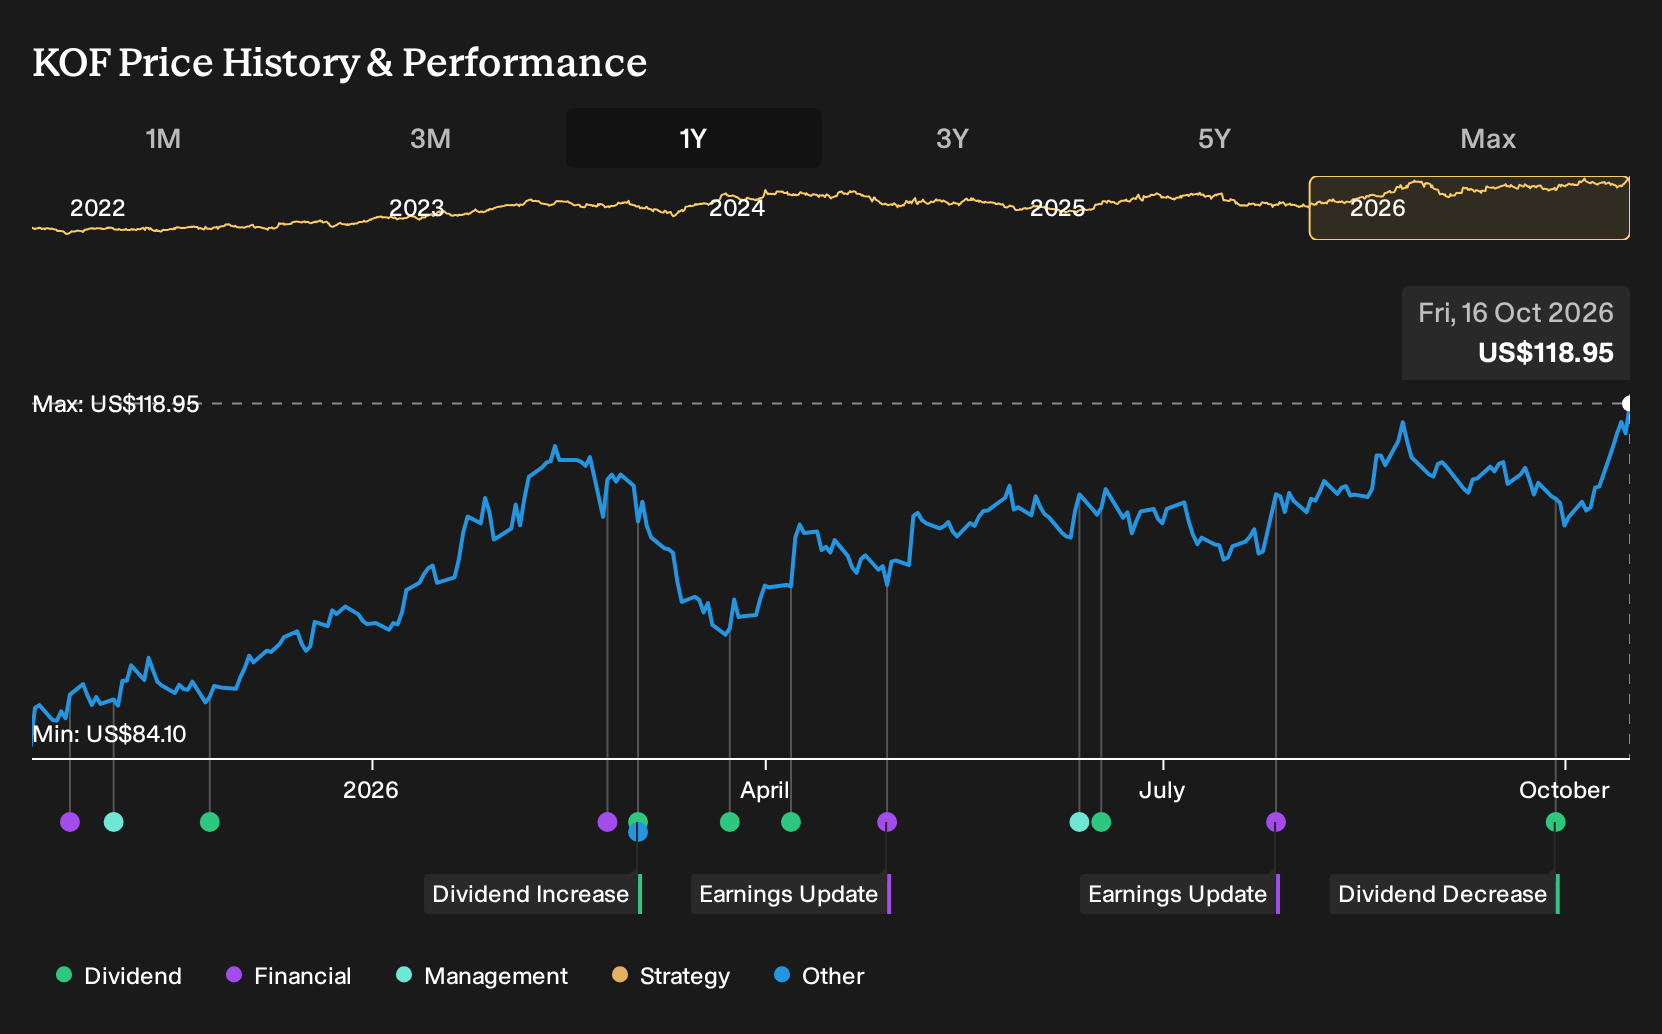
- JPMorgan recently upgraded Coca-Cola FEMSA from Neutral to Overweight, reflecting increased confidence in how the bottler is running its beverage operations across key Latin American markets.
- The upgrade leans heavily on operational themes like portfolio mix, digital execution and margin resilience, rather than short term trading factors or sentiment alone.
- We will now look at how this JPMorgan upgrade could reshape Coca-Cola FEMSA's broader investment narrative for long term holders.
See how Coca-Cola FEMSA's upgrade compares with other potential long-term compounders by reviewing our curated list of 33 high quality undervalued stocks that are poised for stronger fundamentals and healthier balance sheets.
Coca-Cola FEMSA. de Investment Narrative Recap
Coca-Cola FEMSA. de appeals to long term holders who believe its mix of digital execution, affordability formats and zero sugar beverages can keep consumer reach resilient across Mexico, Brazil and the rest of Latin America. The key short term swing factor is how well volumes and pricing hold up against a still cautious Mexican shopper and higher operating expenses.
Operating costs already pressured margins in Mexico and Central America when marketing and freight rose faster than raw material savings. That remains the biggest risk. The JPMorgan upgrade does not change this operational reality in a material way. It mostly reframes existing strengths rather than introducing a new near term catalyst.
With no fresh corporate announcements tied directly to the JPMorgan call, the relevant reference point is how existing initiatives like Juntos+ and Juntos+ Advisor line up with the thesis. These tools are already associated with better outlet coverage and execution in Brazil and Mexico, which sits squarely in the middle of the operational story investors are watching.
The upgrade effectively shines more light on those ongoing projects rather than pointing to a new event. For you as a shareholder, the key question is execution. Can Coca-Cola FEMSA. de keep using these digital platforms, hedging on inputs like PET and sugar, and a focus on affordability to offset softer consumers and cost pressure without eroding margins further?
What The JPMorgan Call Implies About Coca-Cola FEMSA. de's Forecasts
Coca-Cola FEMSA. de is being judged by analysts on whether its digital toolkit and margin work can support a clear set of numbers rather than a loose story. The earnings bridge from today to the outer year target is quite specific, which gives you something concrete to compare with your own assumptions on pricing power and consumer demand.
Coca-Cola FEMSA. de's narrative projects MX$376.2b revenue and MX$31.3b earnings by 2029. This assumes 8.3% yearly revenue growth and an earnings increase of MX$7.4b from MX$23.9b today.
On the income line, consensus expects profit margins to move from 8.1% today to 8.3% over the next three years. That is a relatively small shift in percentage terms, yet it still asks the business to keep a tight grip on input hedging and overheads while rolling out more zero sugar and still beverages, which often need heavier marketing support.
The gap between current earnings of MX$23.9b and the MX$31.3b figure in 2029 also assumes that share count stays flat. That puts the focus squarely on operating execution rather than financial engineering. If volumes disappoint or if marketing and freight stay elevated for longer in Mexico and Central America, the earnings bridge becomes harder to close on this timetable.
Analysts link their upgrade case to a future P/E of 19.4x on those 2029 earnings, compared with 17.5x today and a reported 26.4x for the broader US beverage peer group. For you, that frame is less about predicting the exact multiple and more about testing whether the combination of digital sales tools, price mix and cost discipline is enough to justify Coca-Cola FEMSA. de trading closer to the sector than it does right now.
Uncover why Coca-Cola FEMSA. de's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One area where the most optimistic analysts break from the baseline view is earnings power from Coca-Cola FEMSA’s digital rollout. Before this JPMorgan upgrade, the bullish group was already mapping MX$370.6b revenue and MX$34.3b earnings by 2029. You now need to decide whether this upgrade nudges those already ambitious expectations even higher or pushes some analysts to reassess.
Explore 4 other Coca-Cola FEMSA. de fair value estimates, including one that suggests potential upside of as much as 42% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Coca-Cola FEMSA. de research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Coca-Cola FEMSA. de. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coca-Cola FEMSA. de's overall financial health at a glance.
Looking for more investment ideas beyond Coca-Cola FEMSA. de?
Once you have a view on Coca-Cola FEMSA. de, it can help to benchmark that conviction against other opportunities that fit different risk and income profiles. Use the Simply Wall St Screener to scan for stocks that line up with your goals rather than relying on headlines alone.
- If capital preservation is top of mind, start with a basket of companies screened for resilience through a 32 resilient stocks with low risk scores that focuses on steadier fundamentals.
- For those who care most about income, use a tool that targets reliable payers by filtering for 8 dividend fortresses that might suit a yield focused approach.
- If you are hunting for quality that is not widely followed, cast a wider net with a curated pool of 20 high quality undiscovered gems that combine solid financials with lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com