


Is Pennon Group (LSE:PNN) Cheap On Deutsche Bank’s Downgrade To Hold?
Why Deutsche Bank’s downgrade matters for Pennon Group
Deutsche Bank’s downgrade of Pennon Group (LSE:PNN) to hold from buy, and its comments on returns sitting below the cost of equity, pushed investors to reassess the water utility’s near term appeal.
Pennon Group’s downgrade lands after a tough run for holders, with the share price falling 27.7% over the last month and 38.6% year to date, while the 1 year total shareholder return is down 24.7% and longer term returns remain weak. This points to fading momentum as investors reassess earnings visibility and regulatory returns.
Scan alternative utilities and regulated assets facing similar return pressures with our curated list of 4 resilient stocks with low risk scores. This list may offer a different balance between earnings visibility and downside risk.Pennon Group now trades after a sharp reset rather than a gentle drift, so the real issue is whether most of the pain is reflected or most of the potential already used up as valuation comes under the microscope next.
Most Popular Narrative: 39% Undervalued
Pennon Group’s most followed valuation storyline points to a fair value of about £5.32 against a last close of £3.26. This places significant emphasis on future execution and regulatory outcomes.
Pennon's accelerated capital investment in water network resilience, advanced treatment works, and leakage reduction positions the company to benefit from increased demand for water infrastructure upgrades, regulatory incentives, and long-term asset base growth, which may support a more stable trajectory in regulated revenues and future earnings.
See why 6 investors see Pennon Group as 39% undervalued.
Result: Fair Value of £5.32 (UNDERVALUED)
Still, that storyline can be knocked off course if environmental issues trigger higher compliance costs or if Pennon Group’s relatively high gearing tightens financial flexibility.
Find out about the key risks to this Pennon Group narrative.
Another view on Pennon Group’s valuation
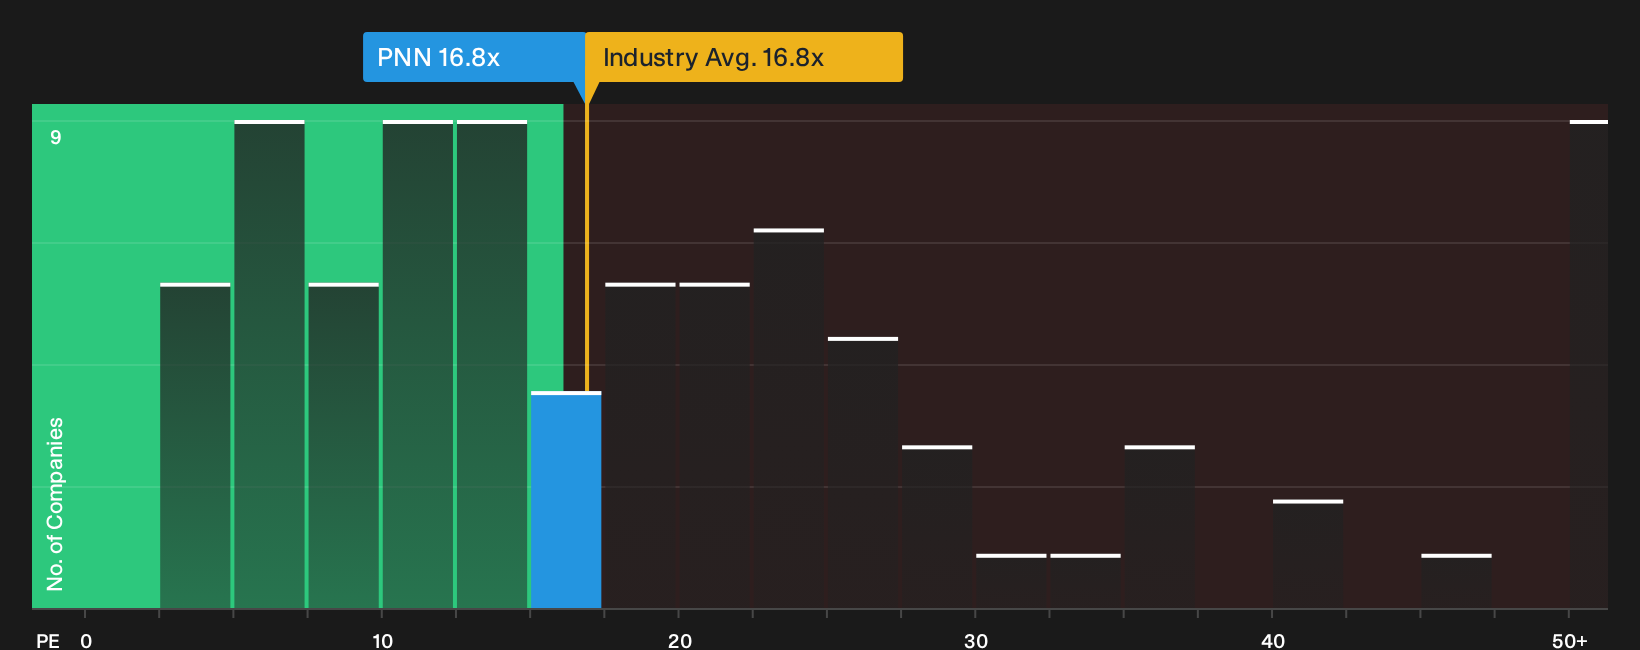
The fair value storyline leans on long range earnings forecasts, yet Pennon Group’s current P/E of 16.8x tells a more restrained story. That multiple is below the Water Utilities industry average of 20.9x, below the peer average of 48.2x, and slightly above a fair ratio of 14.8x. This points to limited margin for error rather than a clear bargain. If sentiment or earnings slip, the share price could move toward the fair ratio or back toward richer peer levels.
See what the numbers say about this price in our valuation breakdown, and how they compare across peers, by going to See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all feels finely balanced between risk and opportunity, that is exactly the point. Move quickly to do your own research and pressure test the figures by weighing up the 3 key rewards and 3 important warning signs
Looking for more Pennon Group sized investment ideas?
If Pennon Group has sharpened your focus on valuation, do not stop here. Use targeted screeners to spot fresh opportunities before they move without you.
- Target potential mispricing by scanning companies flagged as higher quality yet priced as if they are struggling through the 7 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with sturdier finances using the list of solid balance sheet and fundamentals (9 results).
- Hunt for lesser known opportunities with strong fundamentals that are not yet widely followed through the 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com