


What Dentsu Group Holders Got Right
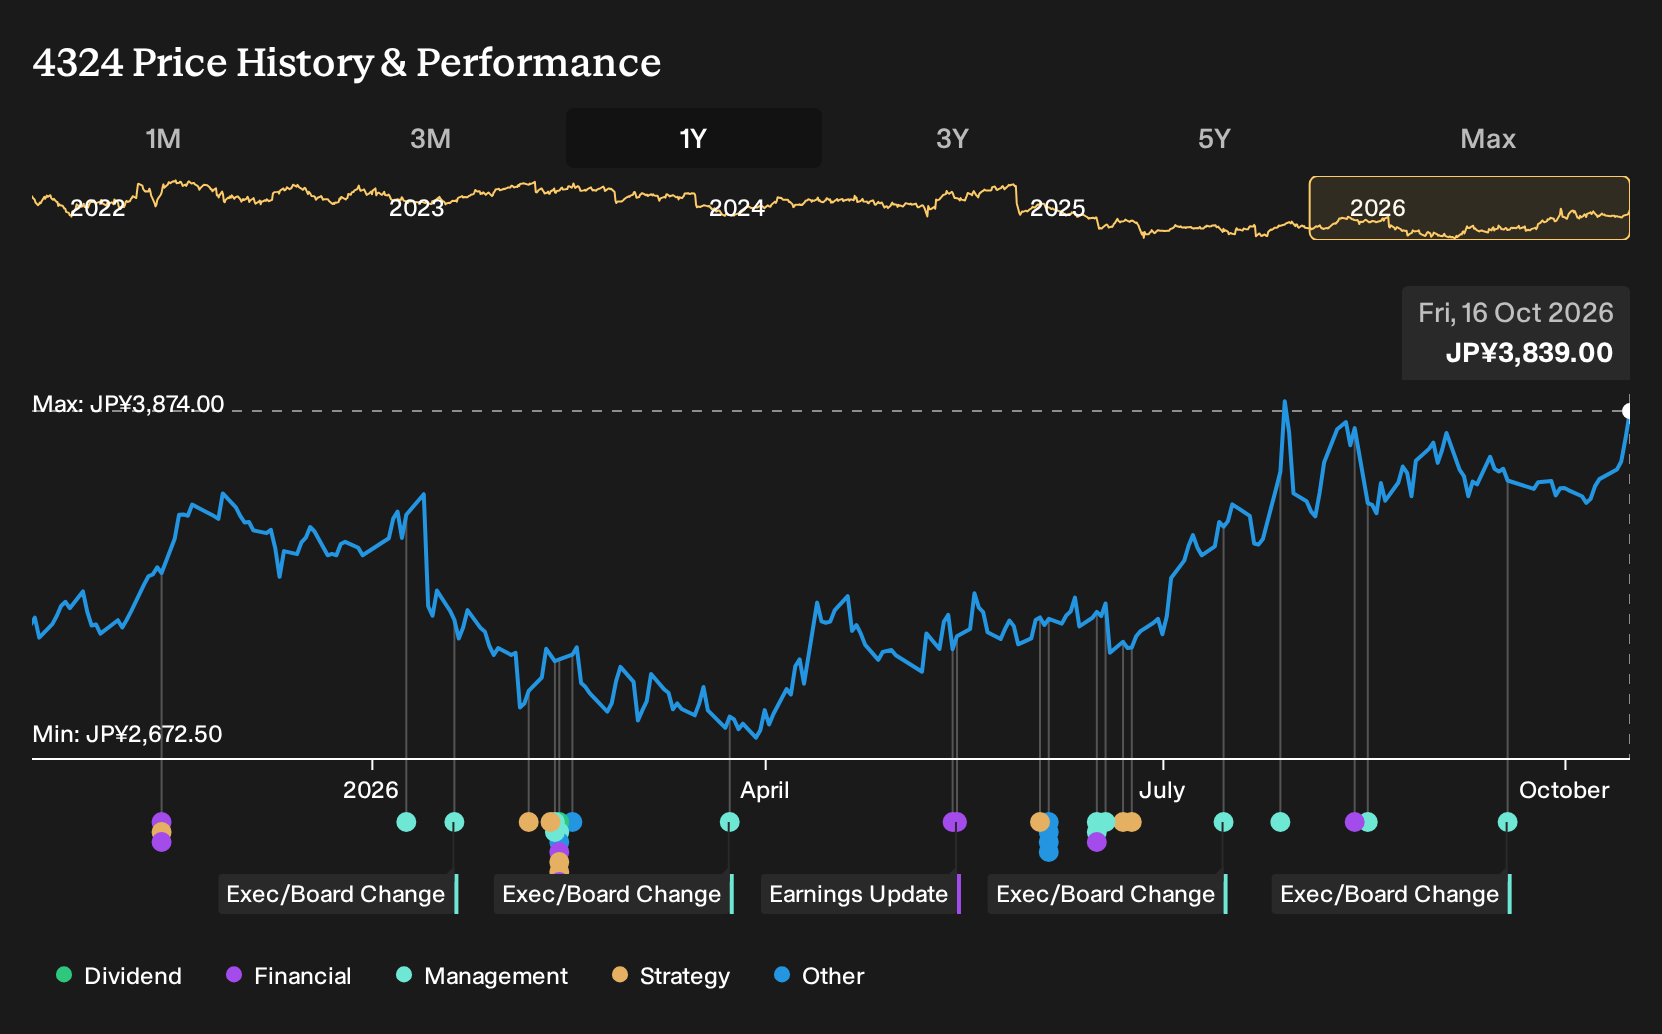
If you had bought Dentsu Group on 16 October 2025, the decision looked finely balanced between bullish hopes for AI driven margin repair and worries about privacy rules and in-housing eroding its position. For Dentsu Group shareholders, the return over the past year was 26.7%, including dividends. With fresh headlines on taking Dentsu Soken private and new media partnerships, the question now is simple: Which of those early concerns should carry more weight today?
If the move has made Dentsu Group harder to judge, start where the gap is still open and scan 13 high quality undervalued stocks.
The Argument Investors Had To Weigh On Dentsu Group
The shares cost ¥3,100 at the start of the period, which left investors pulled between two very different stories about what Dentsu Group could become.
On the bullish side, the “Digitalization And AI Integration Will Fuel APAC Expansion Globally” narrative pointed to a Fair Value of ¥4,600, a price level implied by assumptions of stronger outcomes. Supporters leaned on AI tools like Dentsu.Connect and AIQQQ Studio and expected revenue to rise 2.1% a year with margins recovering from a loss to 9.2% by 2028.
The bear camp, framed as “Rising Privacy Regulations Will Cripple Digital Advertising,” saw a Fair Value of ¥2,400 based on more cautious expectations. This view worried that tougher privacy rules and in-housing would squeeze data access and pricing, with revenue rising only 1.5% a year and profit margins reaching just 4.6% over the same period.
What The Evidence Did To The Dentsu Group Argument
The move to take Dentsu Soken private with Fujitsu and a trading house pointed toward the bullish case, since it tightened control of core tech capabilities. Reported results then gave harder numbers to weigh. Revenue reached ¥360,223 million in Q2 2026 and net income shifted from a loss of ¥79,916 million in Q2 2025 to a ¥6,124 million profit, lifting net margin from -23.6% to 1.7%. The evidence cut both ways because profitability remained modest.
The lesson for readers is simple. When an investment story leans heavily on margin repair, focus on net margin, not just revenue and profit. Check whether the percentage margin is actually turning positive and moving toward the targets in the original thesis before treating early gains as confirmation.
What Dentsu Group's Price Now Asks You To Believe
Dentsu Group now trades at ¥3,839, with this Narrative’s Fair Value sitting below that level. The Narrative argues that today’s quote already incorporates a cleaner restructuring story and a slower rebuild in overseas profitability.
You are really judging whether multi year cost cuts and AI tools can lift international margins without Japan’s higher returns doing all the heavy lifting.
"The main thing that has to go right is that Dentsu Group turns its multi-year restructuring, cost reductions and AI deployment into a sustained margin rebuild, while reinvesting enough to stabilise media and CXM growth outside Japan."
One Narrative disagrees with today's price. → See where this Narrative says Dentsu Group should trade
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 37% below our estimate - connects job seekers and employers through large scale hiring and lifestyle platforms.
- Company 2 - 36% below our estimate - focuses on higher skilled and management placements across multiple specialist recruitment service lines.
- Company 3 - 32% below our estimate - supplies bundled digital marketing software and office IT support tailored to smaller enterprises.
That is three of the list. See the full list of 22 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com