


NHK Spring (TSE:5991) Draws Value Attention As DCF Review Puts Fair Value In Focus
A fresh discounted cash flow review of NHK Spring (TSE:5991) has put valuation in the spotlight, with the analysis suggesting intrinsic worth above the current ¥3,467 share price.
Recent trading has been choppy. The 1-day share price return of 1.91% and 30-day share price gain of 4.97% come after a 7-day share price decline of 8.40%. Even so, NHK Spring still shows a 35.17% year-to-date share price return and a 5-year total shareholder return of 381.29%, which keeps the fresh DCF valuation in sharp focus for long-term investors.
Scan how NHK Spring compares with other potential value opportunities by reviewing the hand picked 13 high quality undervalued stocks that share a mix of solid cash flows and balance sheet strength.
NHK Spring now trades at what looks like a steep discount to both DCF fair value and analyst targets after a sharp multi year run. Is that a pricing mistake or a reasonable safety margin given the risks?
Price-to-Earnings of 20.3x: Is it justified?
On a plain P/E yardstick, NHK Spring looks expensive. The shares closed at ¥3,467, which equates to a 20.3x P/E that sits above both the wider JP Auto Components industry and the level suggested by its own fair ratio model.
The P/E ratio compares what investors pay today for each unit of current earnings. For a diversified auto parts group like NHK Spring, which spans suspension, seating, precision components and disk drive suspensions, that lens shows how the market is weighing its earnings profile across cyclical auto demand and more specialised electronics exposure.
Compared with the JP Auto Components industry average of 9.4x, the current 20.3x multiple is more than double. That indicates the market is already assigning a rich earnings tag versus sector peers. Set against an estimated fair P/E of 19.8x, the traded level also sits above where the regression based fair ratio suggests the valuation could gravitate, which may point to a premium that could be difficult to justify if expectations soften.
Explore the SWS fair ratio for NHK Spring.
Result: Price-to-Earnings of 20.3x (OVERVALUED)
Still, the wide mix of auto and electronics businesses at NHK Spring means any hit to global car production or hard drive demand could quickly challenge this rich P/E narrative.
Find out about the key risks to this NHK Spring narrative.
Another view on NHK Spring’s value
The rich 20.3x P/E suggests NHK Spring is expensive, yet the SWS DCF model points the other way. On that cash flow view, the shares at ¥3,467 trade about 43% below an estimated ¥6,087.68 fair value. Which signal should carry more weight in your process?
Look into how the SWS DCF model arrives at its fair value.
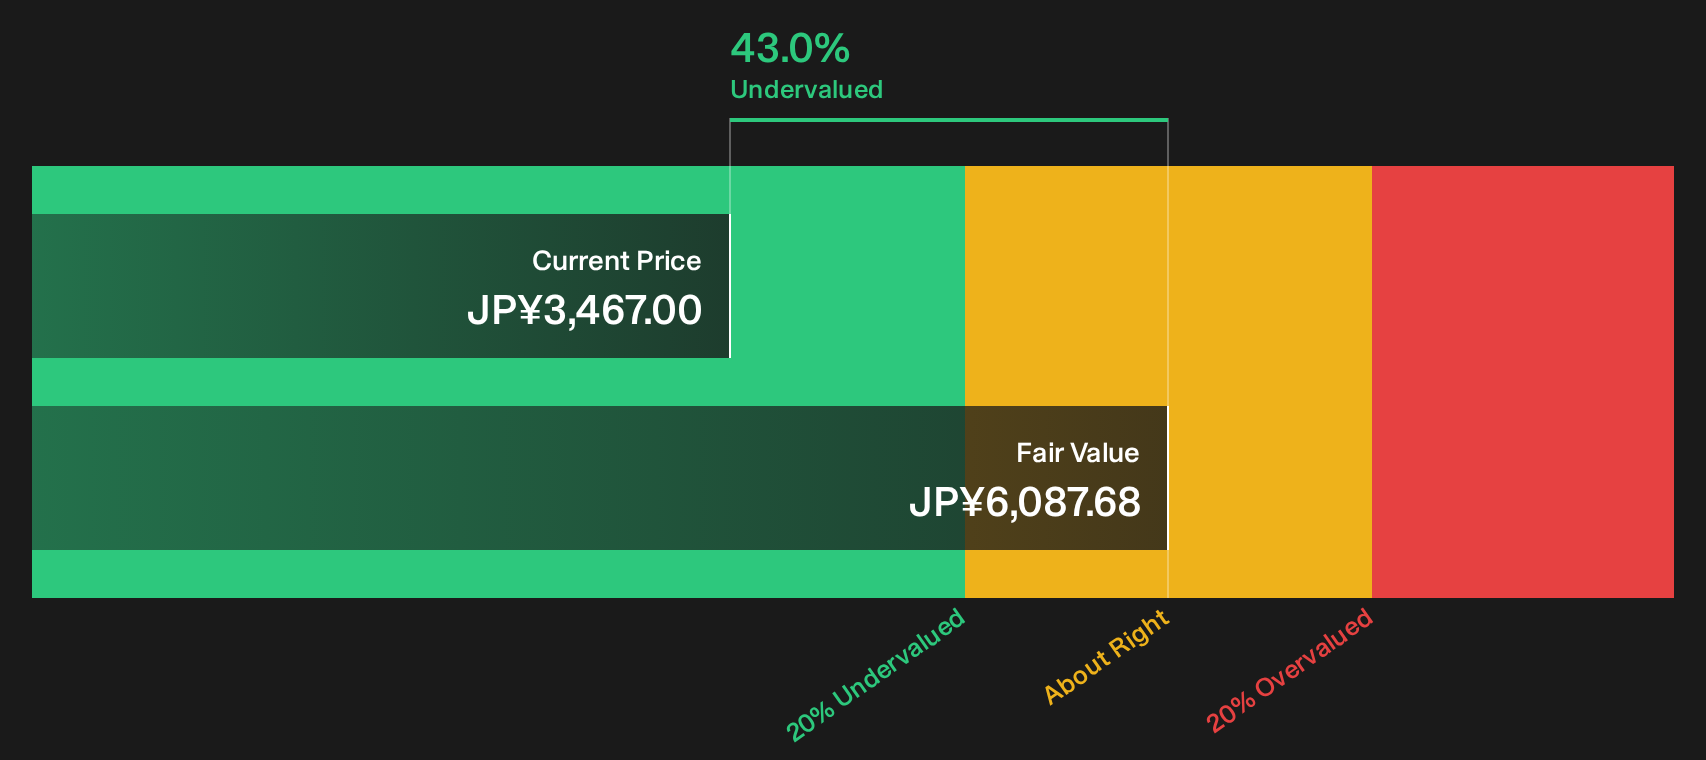
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NHK Spring for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on NHK Spring’s value story so far. Act while the data is fresh, review the full picture and weigh the 3 key rewards and 2 important warning signs.
Looking for more NHK Spring investment ideas?
If NHK Spring has sharpened your focus on value and risk, now is the moment to broaden your watchlist with a few targeted idea sources.
- Spot potential turnarounds early and review the 1 elite penny stocks with strong financials that already pair tiny market caps with stronger financial underpinnings.
- Strengthen your foundation by scanning a list of solid balance sheet and fundamentals (22 results) that can support operations when conditions get tougher.
- Stay one step ahead by tracking 73 high quality undiscovered gems before they attract wider market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com