


How Investors Are Reacting To Couche Tard Stock After Quarterly Results
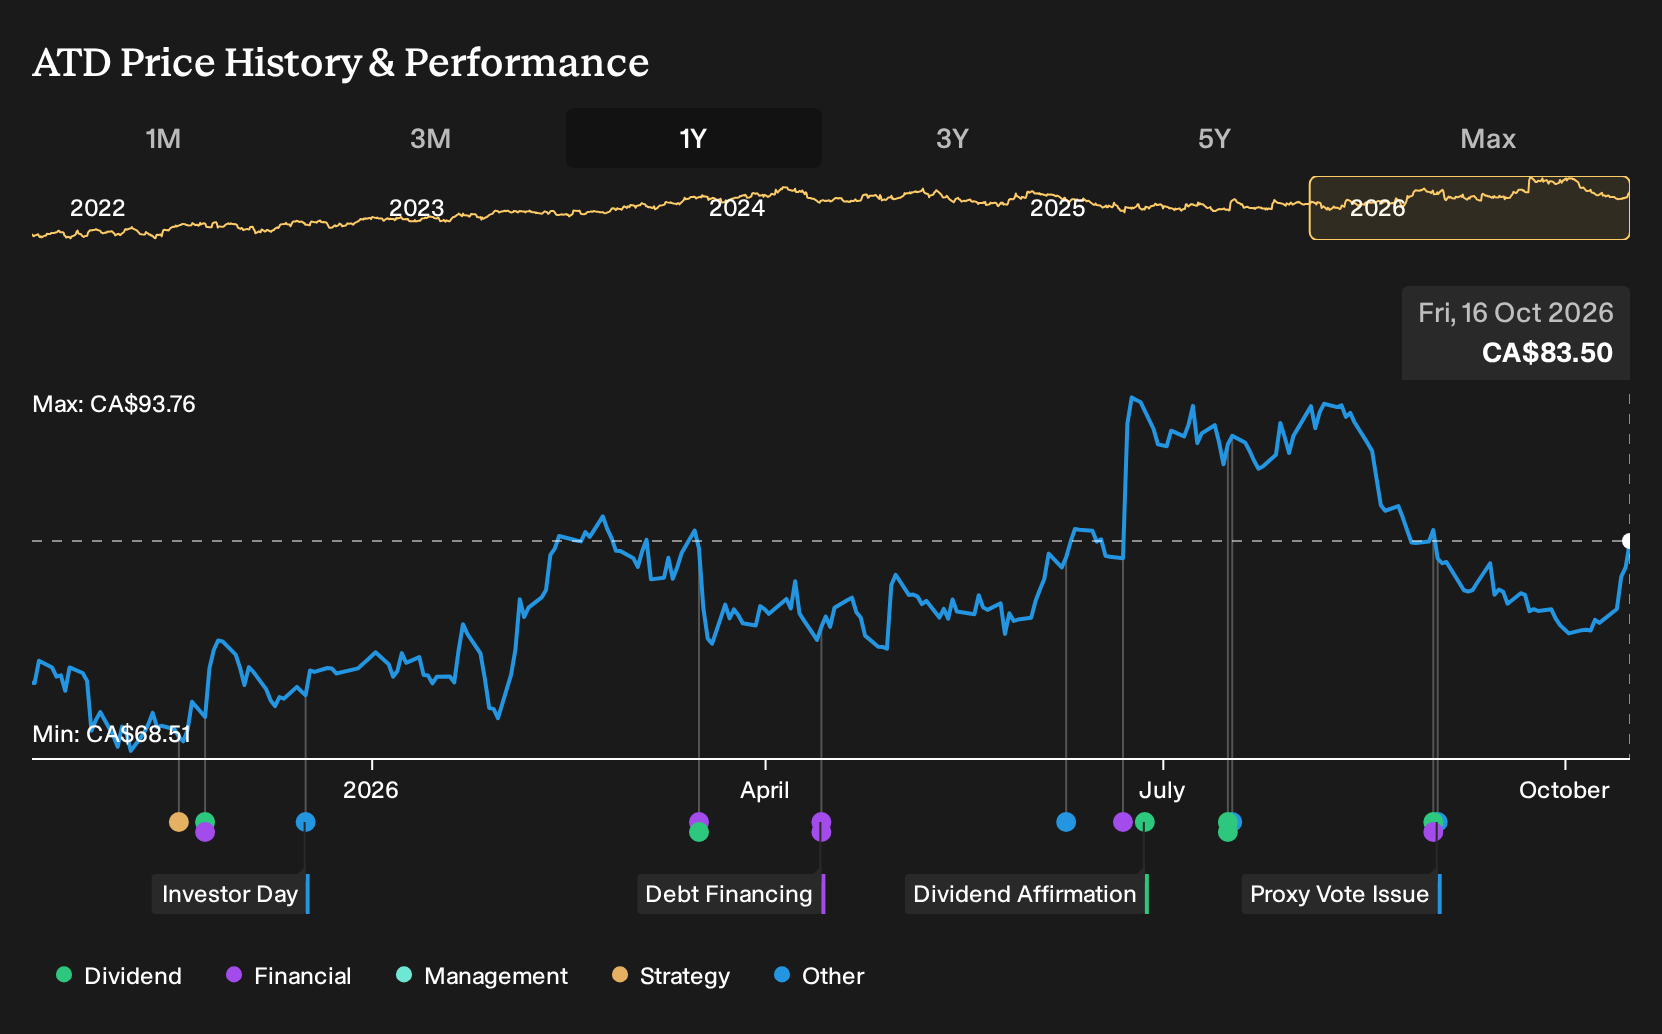
- Alimentation Couche-Tard has been in focus after its first quarter fiscal 2027 update, as investors review same-store merchandise trends, fuel volumes and margins, operating costs, and cash generation across its global convenience and fuel retail network.
- The key storyline is how small shifts in fuel and in-store margins, scaled across Couche-Tard’s large store base and ongoing acquisition program, could materially influence profitability and capital allocation decisions.
- We will now see how Alimentation Couche-Tard's investment narrative could shift as investors scrutinize fuel margins and same-store performance more closely.
Scan how Alimentation Couche-Tard stacks up against other resilient operators by running the 8 resilient stocks with low risk scores as you reassess fuel margins, store productivity, and balance-sheet strength across your watchlist.
Alimentation Couche-Tard Investment Narrative Recap
To own Alimentation Couche-Tard, you really need to believe its mix of global fuel retail and convenience formats can keep generating healthy cash even as fuel demand and tobacco face structural headwinds. The immediate swing factor after the latest quarter is still fuel margins and volumes. Small shifts per litre, multiplied across a huge footprint, matter more to near term earnings than anything else.
The biggest operational risk right now is that declining road fuel demand and tobacco pressure collide with rising labor and other operating costs. If cost control and in store merchandise growth do not keep pace, margin compression becomes the key concern. The recent Q1 update does not change that core risk reward equation in a material way.
With no fresh company specific announcements disclosed alongside this trading interest, the most relevant reference point remains Alimentation Couche-Tard's first quarter fiscal 2027 result for the period ended 19 July 2026. That update put a spotlight on same store merchandise trends, fuel volumes, fuel pricing spreads, and how effectively management is handling operating expenses and new store productivity.
For catalysts, that Q1 snapshot gives you the operational checklist. Watch merchandise mix and foodservice, the Inner Circle and broader digital programs, capital expenditures on new sites and EV charging, and cash conversion that can fund acquisitions or shareholder returns. On the risk side, keep an eye on any further softening in U.S. and European road fuel usage, plus wage and integration costs, because those are the pressure points that could test the current investment narrative.
Alimentation Couche-Tard's current analyst storyline points to $84.7b in revenue and $3.5b in earnings by 2029, based on consensus estimates. That implies 1.5% yearly revenue growth and an earnings increase of about $0.3b from $3.2b today.
Uncover why Alimentation Couche-Tard's fair value indicates a 23% potential upside to its current price, creating a gap that could narrow quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between about $102 and $159 per share, which is a wide span for Alimentation Couche-Tard. That range reflects risks around fuel demand, tobacco regulation, and rising operating costs. Use these contrasting opinions as a prompt to test your own thesis from multiple angles.
Explore 2 other Alimentation Couche-Tard fair value estimates, including one that suggests it could be worth just CA$102.08!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Alimentation Couche-Tard research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alimentation Couche-Tard. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alimentation Couche-Tard's overall financial health at a glance.
Looking for more investment ideas beyond Alimentation Couche-Tard?
If you want to stress-test your thesis on Alimentation Couche-Tard, it can help to line it up against other businesses with different risk, income, and balance sheet profiles using the Simply Wall St Screener.
- For potential mispriced opportunities with strong fundamentals, compare what you see here with a curated set of 10 high quality undiscovered gems that might not be on everyone's radar yet.
- If income resilience matters most to you, weigh Couche-Tard against issuers in the 3 dividend fortresses and see how yield, payout ratios, and coverage stack up.
- For a focus on financial resilience, broaden your watchlist by scanning a list of solid balance sheet and fundamentals (8 results) and test how Couche-Tard's leverage and liquidity compare.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com