


How Utility Stability And Dividend Resilience Will Impact AltaGas (TSX:ALA) Investors
- AltaGas is under review as investors weigh the stability of its regulated utility rate base, midstream export volumes, project spending and regulated returns ahead of the next earnings update.
- Attention has shifted to whether AltaGas’ recurring cash flows, capital plans and financing flexibility can support its indicated 2.42% dividend yield through different market conditions.
- Next, the focus is on how AltaGas’ utility stability and dividend resilience shape the broader investment narrative around the business.
Scan how AltaGas stacks up on balance-sheet strength and cash flow against a hand-picked list of solid balance sheet and fundamentals (8 results) to pressure test your income ideas beyond a single 2.42% yield.
AltaGas Investment Narrative Recap
To own AltaGas, you need to be comfortable with a simple idea. A relatively steady utility rate base and a fee based LPG export platform can keep supporting cash generation while the firm keeps spending heavily on pipes, terminals and rail. The current review of its stability really circles around project execution and how reliably those assets can run.
The key near term swing factor is still operational delivery at Ridley and the export chain, alongside maintaining dependable utility earnings through rate cases. The biggest risk is that cost inflation, weather issues or tighter regulation weaken returns just as interest costs and dividend expectations keep pressing on cash flow.
With no fresh company announcement tied directly to this review, the earlier update on the Ridley Island Energy Export Facility remains the most important reference point. That project already absorbed a 12% capital cost increase to about $1.5b and a later in service date after more than 450 lost marine rig days from weather, ocean swells and marine mammal activity.
Those issues turned Ridley from a clean growth story into a real execution test, and they still frame the current debate. Any further delay or cost pressure would increase capital intensity. This could squeeze returns from AltaGas’ LPG export platform and leave less room to comfortably fund utilities capex, interest payments and the indicated 2.42% dividend yield.
AltaGas' narrative points to CA$16.4b in revenue and CA$1.0b in earnings by 2029, based on analysts' estimates that revenue can grow by 6.2% a year. That projection assumes earnings today of CA$615.0m and implies an earnings increase of about CA$385.0m by the 2029 forecast year.
Discover why AltaGas' fair value indicates a 6% potential upside to its current price, a discount that could close faster than many income investors expect.
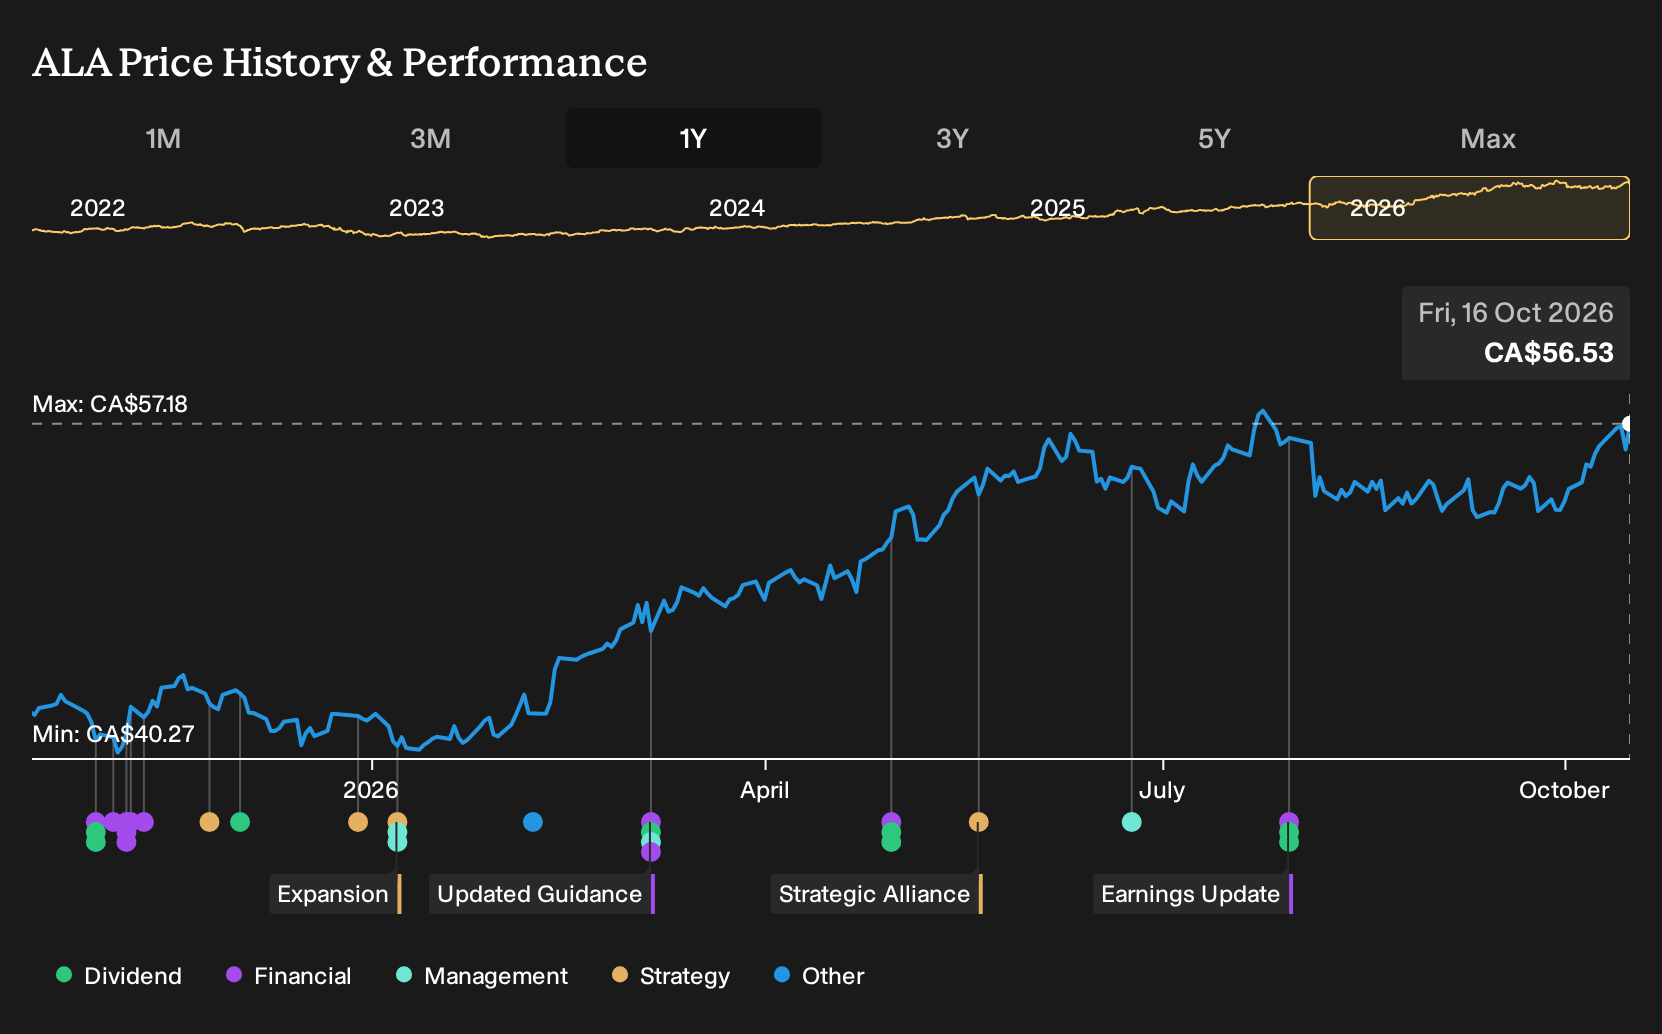
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community bracket AltaGas between about 60x and 92x, which is a wide span for one ticker. Those private investors are clearly not aligned. When you set that spread against policy risk around decarbonization and heavy capex needs, you get a richer mix of potential outcomes to explore.
Explore another AltaGas fair value estimate, including one that suggests it could be worth just CA$60.18.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AltaGas research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AltaGas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AltaGas' overall financial health at a glance.
Looking For More Ideas Beyond AltaGas?
Once you have formed a view on AltaGas, it can help to compare that thesis with other opportunities that match your income, value or risk appetite. The Simply Wall St Screener lets you quickly filter the market so you can stress test your AltaGas decision against a broader watchlist.
- If you are hunting for mispriced quality, line up your AltaGas view against a wider field of companies screened as 5 high quality undervalued stocks to see what else fits a value driven checklist.
- For investors who care more about steady cash flows than headline growth, compare AltaGas' income profile with a curated set of 3 dividend fortresses that may offer different payout levels and business models.
- If capital preservation is the priority, weigh AltaGas' risk profile against a universe of 8 resilient stocks with low risk scores that score well on financial strength and volatility metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com