


Elbit Systems (TASE:ESLT) In Focus As Israeli Election Results Put Fair Value Back In Play
Elbit Systems (TASE:ESLT) has drawn increased investor attention following the recent Israeli elections, as any change in defense spending priorities can directly affect its government contracts and future order flow.
The share price of Elbit Systems has moved sharply in the past week, with a 7 day share price return of 13.9% and a year to date share price gain of 23.62%. Longer term investors have seen a 44.9% 1 year total shareholder return and a very large 5 year total shareholder return that points to momentum building rather than fading.
Scan other defense and security contractors showing similar momentum by reviewing the hand-picked 234 resilient stocks with low risk scores, which combine resilient balance sheets with recent share price strength.
Elbit Systems now carries the profile of a robust, globally diversified defense contractor, yet the past week’s surge has sharpened the real issue for investors. Does the current price still reflect fair value after that move, or has enthusiasm run ahead of the numbers?
Most Popular Narrative: 22% Undervalued
On the most followed narrative, Elbit Systems screens as undervalued, with a fair value of ₪2,965 against the last close of ₪2,302. That comparison puts the recent price spike in a different light.
Record $25.2 billion backlog, with close to 70 percent from customers outside Israel and multi year contracts such as the 8 year, 2.3 billion dollar strategic program, provides high visibility on sustained top line growth and supports operating leverage and earnings compounding.
See why 6 investors see Elbit Systems as 22% undervalued.
On this view, the discount rate of 9.6% and the modeled path for revenue and earnings combine to support a narrative fair value of ₪2,965. That sits meaningfully above the current ₪2,302 market level, so the debate shifts to whether you agree with the assumptions baked into that story.
Result: Fair Value of ₪2,965 (UNDERVALUED)
Still, any normalization in global defense budgets or weaker demand from key segments such as Aerospace and Elbit Systems of America could quickly challenge that undervaluation story.
Find out about the key risks to this Elbit Systems narrative.
Another View: What Elbit Systems’ P/E Is Telling You
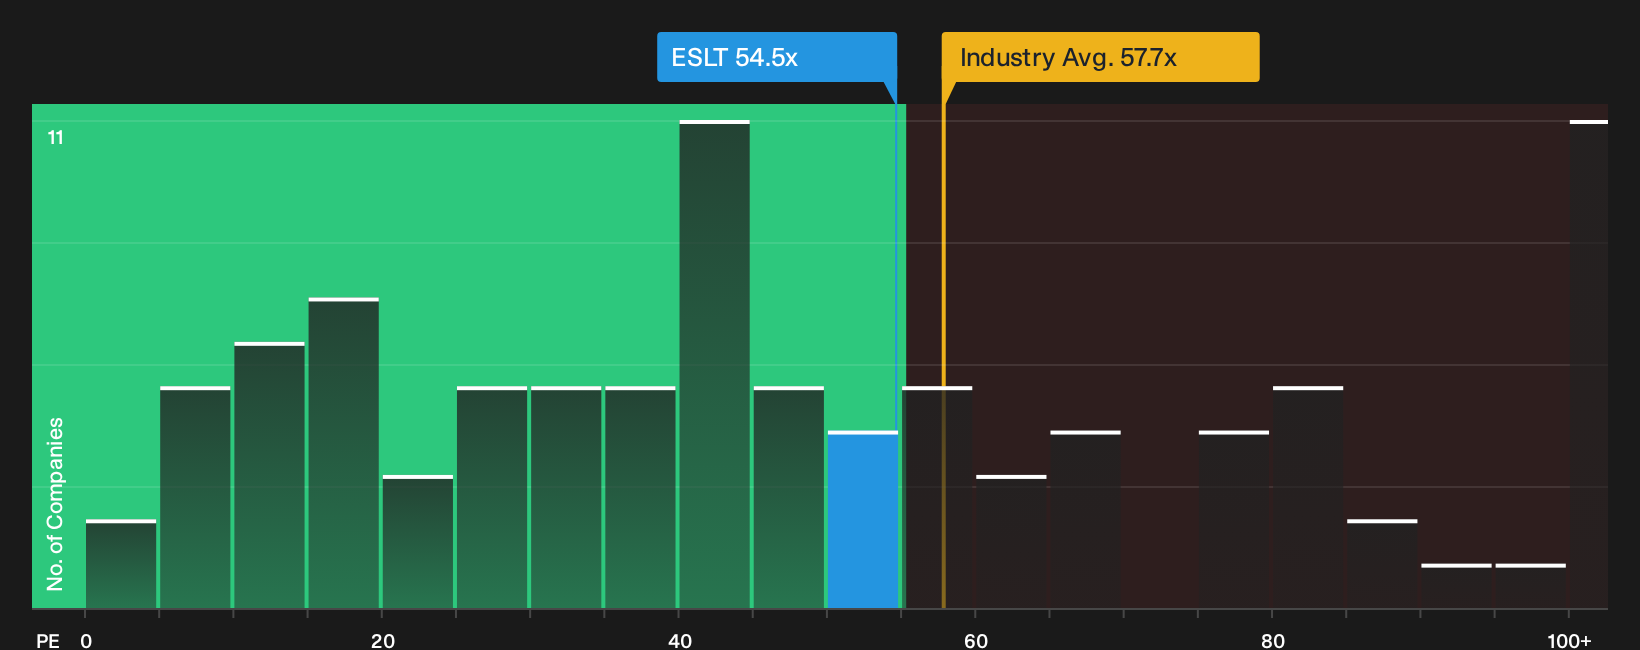
The fair value story built on future cash flows is only one side of Elbit Systems. On simple earnings multiples, the picture changes. The current P/E is 54.5x, above the peer average of 36.4x, yet still below a fair ratio estimate of 107.2x that the market could ultimately move toward. That gap leaves you weighing whether this premium feels like overpayment today or headroom for sentiment to stretch further.
To see how that earnings multiple stacks up in more detail against peers and the fair ratio, and what that might mean for valuation risk, check the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If sentiment around Elbit Systems feels strongly influenced by recent gains and valuation debates, consider that a prompt to look earlier and examine the data yourself. Start by reviewing the 2 key rewards
Looking for more Elbit Systems style investment ideas?
If Elbit Systems has sharpened your focus on pricing and risk, do not stop here. Broaden your watchlist with a few targeted idea shortcuts.
- Target resilient performance by scanning companies on the 234 resilient stocks with low risk scores that pair lower risk scores with balance sheets built to handle tougher conditions.
- Hunt for potential mispricings using the 614 high quality undiscovered gems to surface underfollowed stocks that still show strong fundamentals and quality markers.
- Build a cash flow focused watchlist by reviewing the 216 dividend fortresses that highlight higher yielding businesses with an income tilt.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com