


International Petroleum (TSX:IPCO) Stock Looks Overvalued Against Its Current Earnings Power
International Petroleum has delivered a powerful run over the past few years, which naturally puts the spotlight on what investors are paying for its earnings today. With the share price now far above where it traded five years ago, the key issue is how closely that market value lines up with the profits the business is generating.
- Over 5 years, International Petroleum has produced a return of 436.4%, which raises the question of how much future earnings strength is already built into the current share price.
- The business relies heavily on converting hydrocarbon production into stable cash flows, which can support its ability to fund investments and return capital without stretching its balance sheet. That profile is central to how investors judge its earnings power.
- The analysts covering International Petroleum have run their own numbers. See what analysts think International Petroleum's shares could be worth.
For investors, the debate is whether International Petroleum's recent share price level is appropriately grounded in the earnings it is currently producing.
If you are considering whether International Petroleum's earnings support its current share price, it can be helpful to compare that question across 5 high quality undervalued stocks.
Is International Petroleum Getting Expensive on Earnings?
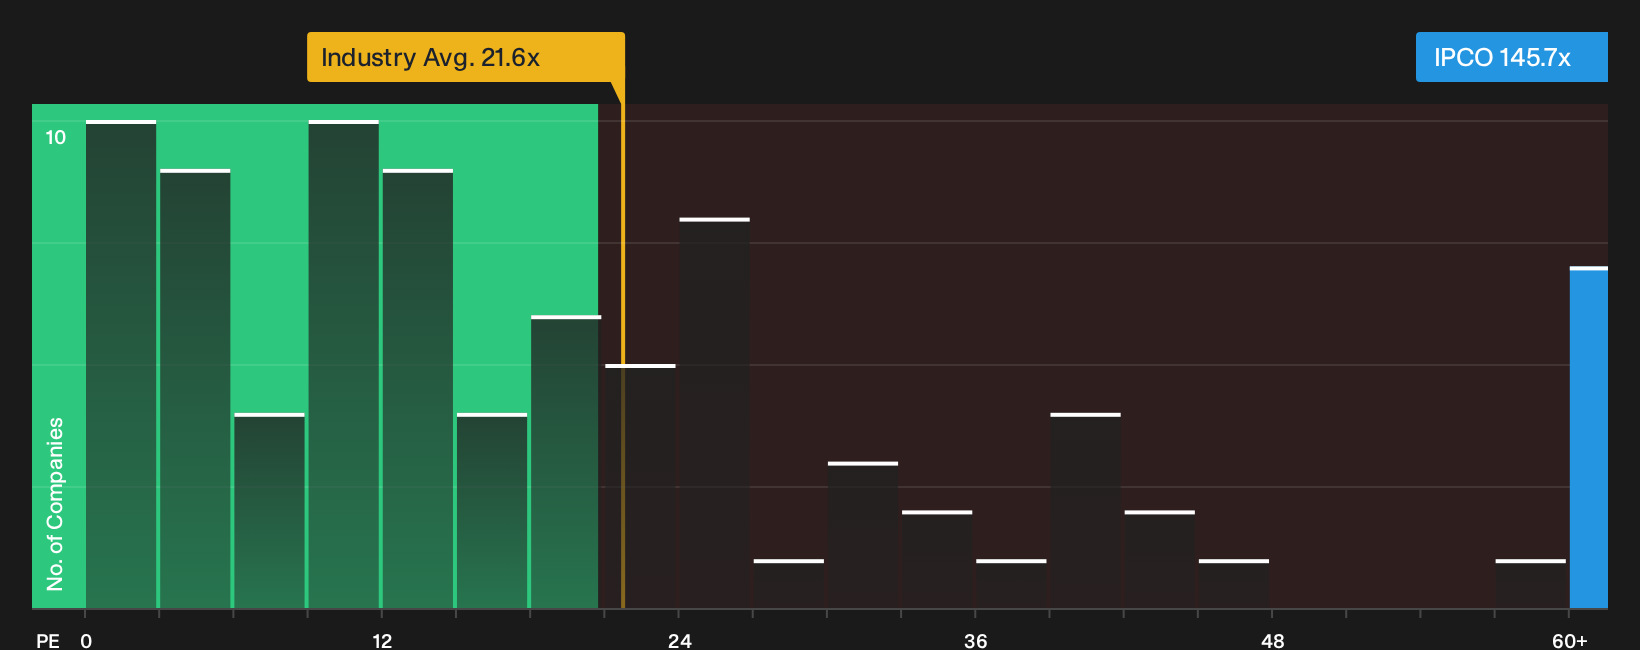
The P/E ratio is a useful lens for International Petroleum because it links what you pay today directly to the profits already on the books. On this measure, the stock trades on roughly 145.7x earnings, which is far above the Oil and Gas industry average of about 21.6x and also well ahead of the broader peer group near 22.4x. That gap suggests buyers are willing to pay a premium price for each dollar of current profit compared with many other producers.
The tailored fair multiple for International Petroleum, which adjusts for the firm’s growth profile, margins, size and risk, sits meaningfully lower than where the shares currently trade, and the model is heavily penalising recent losses in free cash flow and perceived risk. Rather than reading that output as a precise target, it is better viewed as a flag that the stock screens as overvalued on earnings on this framework, and that a lot of optimism already sits in the current share price. Explore the numbers behind International Petroleum's P/E valuation.
The International Petroleum Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for International Petroleum pick up where the P/E puzzle leaves off and set out what kind of future earnings path, margin profile and reinvestment outcome would need to play out for the stock to look meaningfully cheaper or richer than today’s valuation on the Community page. Rather than giving a single headline ratio, they break that number into concrete assumptions that you can watch over time and judge whether they continue to hold.
Community views on International Petroleum split between those who see disciplined projects and buybacks as support and those who focus on execution risk and debt.
Bull case: 6% undervalued
"Ongoing share buybacks, currently funded by operating cash flow and anticipated to continue as Blackrod cash generation ramps up, should provide continued support to EPS growth and overall equity value..."
Discover why this Narrative puts International Petroleum at 6% undervalued.
Bear case: 9% overvalued
"The business exited 2025 with net debt of US$484 million after a year where free cash flow, after all growth capital, was a loss of US$153 million..."
Explore why this Narrative puts International Petroleum at 9% overvalued.
Before focusing only on International Petroleum's valuation, look at what else the checks are flagging
Price and earnings tell only part of the International Petroleum story, since the broader fundamental checks have raised specific concerns that deserve attention before you act. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com