


Guidance Upgrade Will Impact Takeuchi Mfg Stock Investors
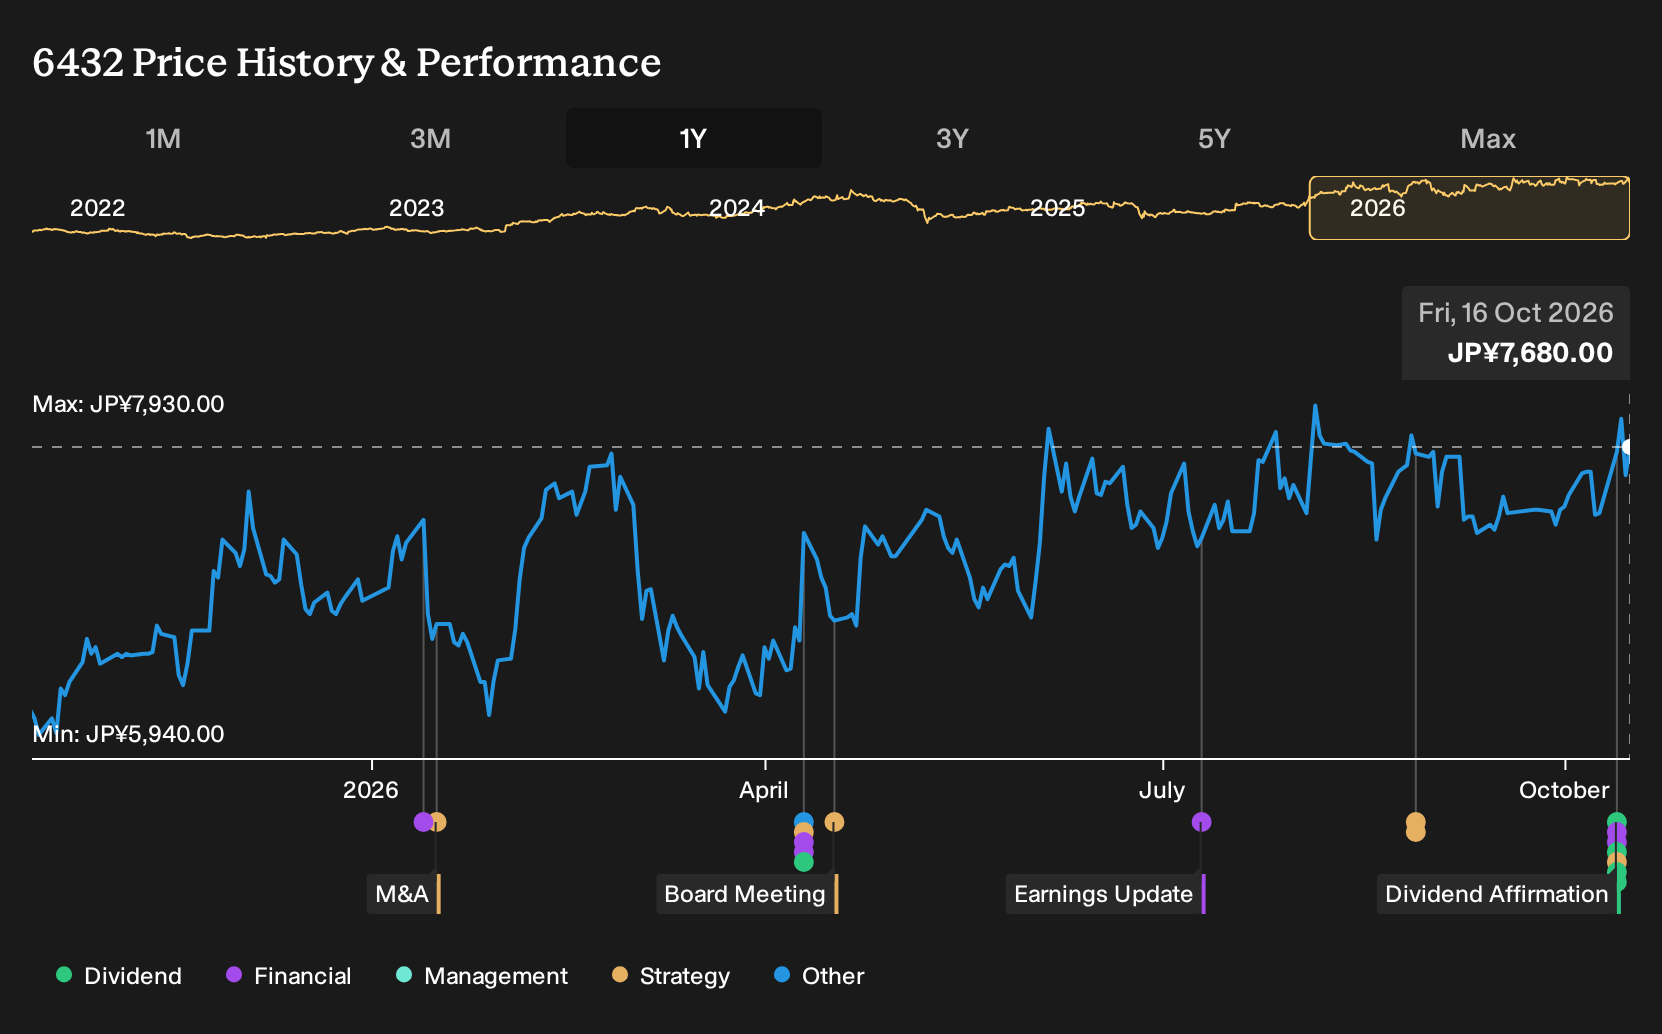
- Takeuchi Mfg announced on 13 October 2026 a share repurchase program of up to 2,000,000 shares for ¥15,000 million, alongside higher full year guidance, stronger half year results and an upgraded year end dividend forecast to ¥135 per share.
- The package of tariff refunds, weaker yen tailwinds and a sizeable buyback indicates Takeuchi Mfg is using current cash generation to both support operations and increase direct capital returns to shareholders.
- The focus now shifts to how Takeuchi Mfg's increased full year guidance and capital return plans may reshape the broader investment narrative.
What Is Takeuchi Mfg's Investment Narrative?
To own Takeuchi Mfg, you need to be comfortable with a fairly traditional industrial story. The business is about selling mini excavators and other machinery into construction markets, managing capacity, and pricing through cycles. The raised full year guidance, higher dividend forecast and new buyback all point to management leaning into current earnings power and cash generation. In the near term, tariff refunds and a weaker yen are important tailwinds, while higher freight costs and heavier US discounts show how fragile parts of the cost and demand picture can be.
The key operational swing factors now sit around execution on the upgraded sales plan, controlling logistics costs, and keeping capital intensity in check as volumes evolve. Takeuchi Mfg is choosing to return more cash through a bigger year end dividend and up to ¥15,000 million of repurchases, which tightens the link between profits and payouts. That makes the quality and consistency of future free cash flow, not just reported earnings, the real test of this new shareholder friendly stance.
Yet there is a less comfortable angle to this higher payout and buyback story if ...
There's only one way to know the right time to buy, sell or hold Takeuchi Mfg. Head to Simply Wall St's company report for the latest analysis of Takeuchi Mfg's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between ¥8,757 and ¥8,933, yet those retail investors already disagree on where Takeuchi Mfg should trade. You now have raised guidance, tariff refunds and a heavier capital return plan in the mix, so it makes sense to compare several fresh viewpoints.
Explore another Takeuchi Mfg fair value estimate, including one that suggests there could be as much as 16% upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Takeuchi Mfg research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Takeuchi Mfg. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Takeuchi Mfg's overall financial health at a glance.
Looking For More Investment Ideas Beyond Takeuchi Mfg?
If the updated guidance and capital return story at Takeuchi Mfg has sharpened your focus on quality, you can use that same filter as you look at other opportunities. The Simply Wall St Screener can help you quickly surface companies that match the kind of balance sheet strength, income potential, or risk profile you want to back with your own capital.
- For investors who want a focus on resilient businesses with conservative finances, you can start with a 23 resilient stocks with low risk scores that may better align with your risk tolerance.
- If consistent income matters more to you than headline growth, you can scan a curated set of 29 dividend fortresses that combine yield with fundamental strength.
- For those hunting for underappreciated opportunities, you can filter the market for 73 high quality undiscovered gems that currently sit off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com